How to Play the Property Meltdown in Five Charts
Savvy buyers made a fortune after the 2008 crash, picking up real estate at distressed prices. Investors hoping to spot bargains in the latest slump can watch these trends.

 4 min

Is the pain over yet for U.S. commercial real estate? The answer might be yes for stocks but no for the assets they own.
A record $205.5 billion of cash is earmarked for investment in U.S. commercial real estate, according to dry-powder data from Preqin. But good deals may not be available for another six to 12 months. Here are some trends investors can watch for signs of when it is the right time to buy.
How Much Are Values Down Already?
U.S. commercial property prices have fallen 16% on average since their peaks in March 2022, according to real-estate research firm Green Street. Unlike the 2008 crisis, when a lack of credit hurt the value of all real estate, today’s downturn has hit some types of properties much harder than others.
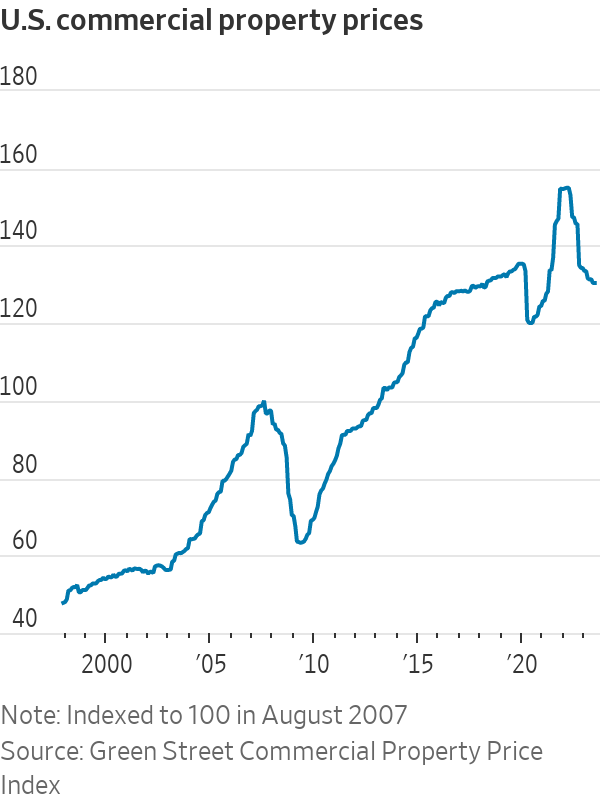
Unsurprisingly given remote working, offices are the worst performers, having lost 31% of their value since the Fed first began raising interest rates. The discount isn’t as enticing as it sounds, as troubled buildings need heavy investment to bring them up to a standard that will attract tenants, or to be redeveloped for new uses.
Meanwhile, prospects for snapping up America’s e-commerce warehouses at knockdown prices look slim. Warehouse values are down just 8% from peaks to reflect higher financing costs, and top industrial stocks like Prologis don’t look cheap either, trading close to net asset value.
Apartments might be a better bet for those hunting for distressed assets. Prices for multifamily apartment buildings have fallen by a fifth since March 2022. Some owners who paid top dollar for properties during the pandemic using short-term, floating-rate debt may be forced to sell if mortgage repayments become unmanageable when their interest rate hedges expire.
Property Sellers Are Still Demanding Yesterday’s Prices
Sellers are holding out for prices that are no longer realistic. MSCI’s bid-ask spread reflects the difference between what U.S. property owners are asking for and what buyers are willing to pay.
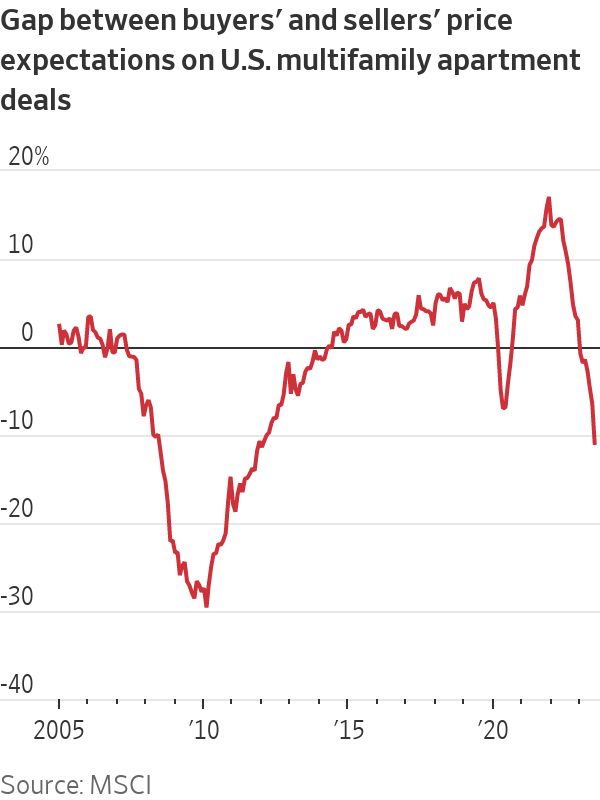
As of July, the gap for multifamily apartments was 11%, the widest it has been since early 2012, when the property market was still recovering from the 2008 crash. The gap for office and retail is a bit narrower at around 8%. Price expectations are closest for industrial warehouses, where sellers want just 2% more than buyers are willing to pay.
The market will be sluggish until one side caves. In the second quarter of 2023, investment in U.S. commercial real estate was down 64% compared with a year earlier, according to data from CBRE.
As the bid-ask gap narrows, it will signal that valuations are approaching more sustainable levels. But this will take some time. It was five years after the 2008 crash before buyers and sellers saw eye to eye on prices on the hardest-hit assets like apartments—although the adjustment should be much faster this time.
What Could Force Sellers to Slash Prices?
The number of properties that slip into distress will be key for bargain-hunters.
So far, there haven’t been many forced sales. Only 2.8% of all office deals in the U.S. in the second quarter were distressed, according to MSCI.
This may be because loans haven’t matured yet. “Owners don’t want to take a loss but once there are refinancing issues, they will have that come-to-Jesus moment with lenders,” says Jim Costello, chief economist at MSCI Real Assets.
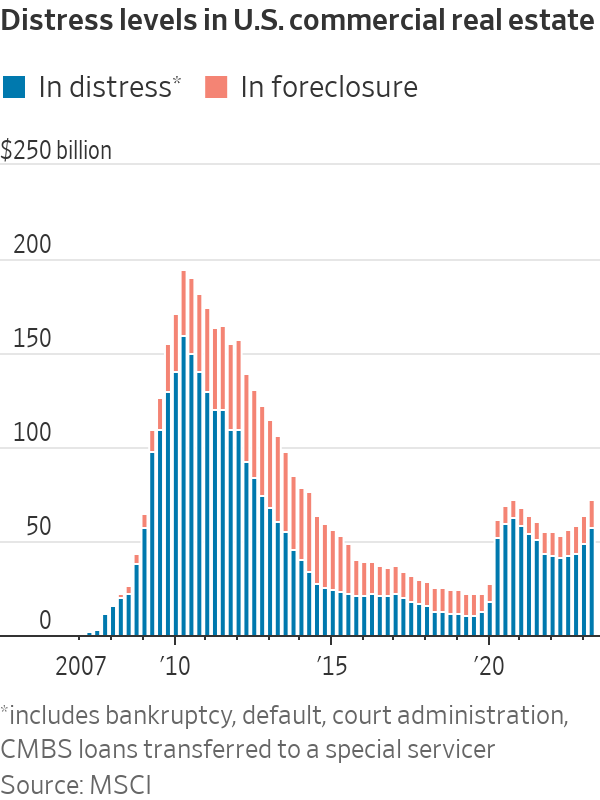
Even if forced sales are still rare, the value of U.S. property in distress—in default or special servicing—is rising. In the second quarter, an additional $8 billion of assets got into distress, bringing the total to $71.8 billion, according to MSCI. Including properties that look at risk, the pool of potentially troubled assets is more than double this amount.
Investment-grade corporate bond yields suggest that property prices have further to fall
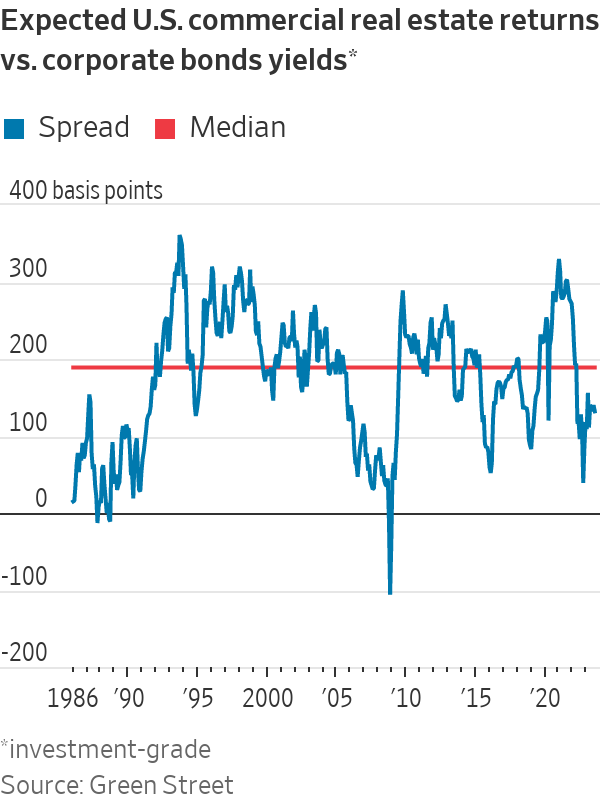
Owning commercial property is a bit like owning a corporate bond, only slightly riskier: You bet on the solvency of a tenant, with more uncertainty about the value of the capital you’ll get back. For at least the past 20 years, investors in U.S. real estate have required a return premium of 1.9 percentage points over the yield on investment-grade corporate debt, according to Green Street’s director of research, Cedrik Lachance.
Right now, real estate only offers a 1.3 percentage point premium. For the relationship to return to normal and make property attractive again, U.S. real-estate prices need to fall a further 10% to 15%.
The share prices of listed property companies also point to further falls
Publicly traded real-estate stocks provide a live read of sentiment toward property markets. In the U.S., listed property companies currently trade at a 10% discount to gross asset values, based on Green Street data. This is a good proxy for the size of the price falls that investors still expect in private real-estate values.
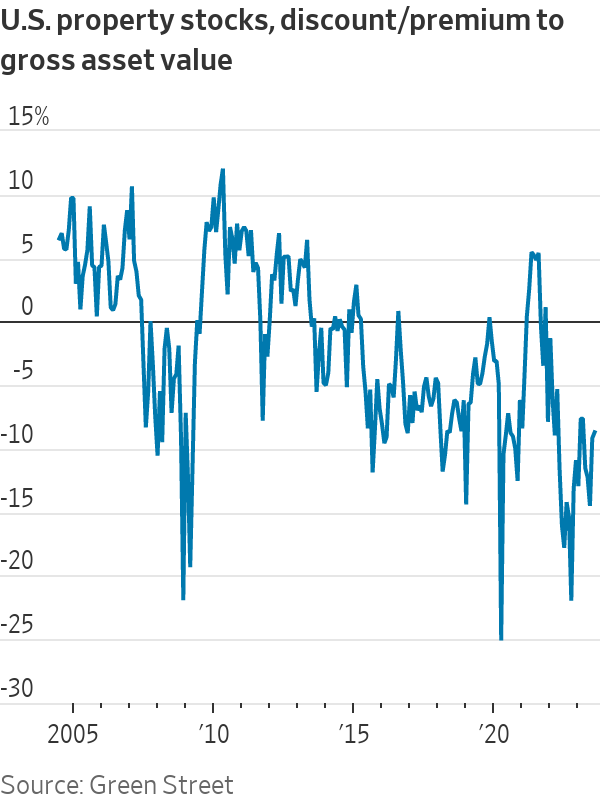
Investors can also keep an eye on property stocks for signs of improvement. “Listed real estate is a leading indicator for private in downturns and also recoveries,” says Rich Hill, head of real estate strategy and research at Cohen & Steers, who points out that there are already green shoots. At the end of June, REITs had risen in value for three consecutive quarters and were 13% above their lowest point in the third quarter of last year. Based on how long it usually takes for a recovery to feed through to the private market, property values could hit the bottom within six to 12 months.
All this suggests the best strategy is to buy property stocks but to wait to purchase physical real estate. “If you want to bottom fish in real estate now, do it in the public markets,” says Green Street’s Lachance.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min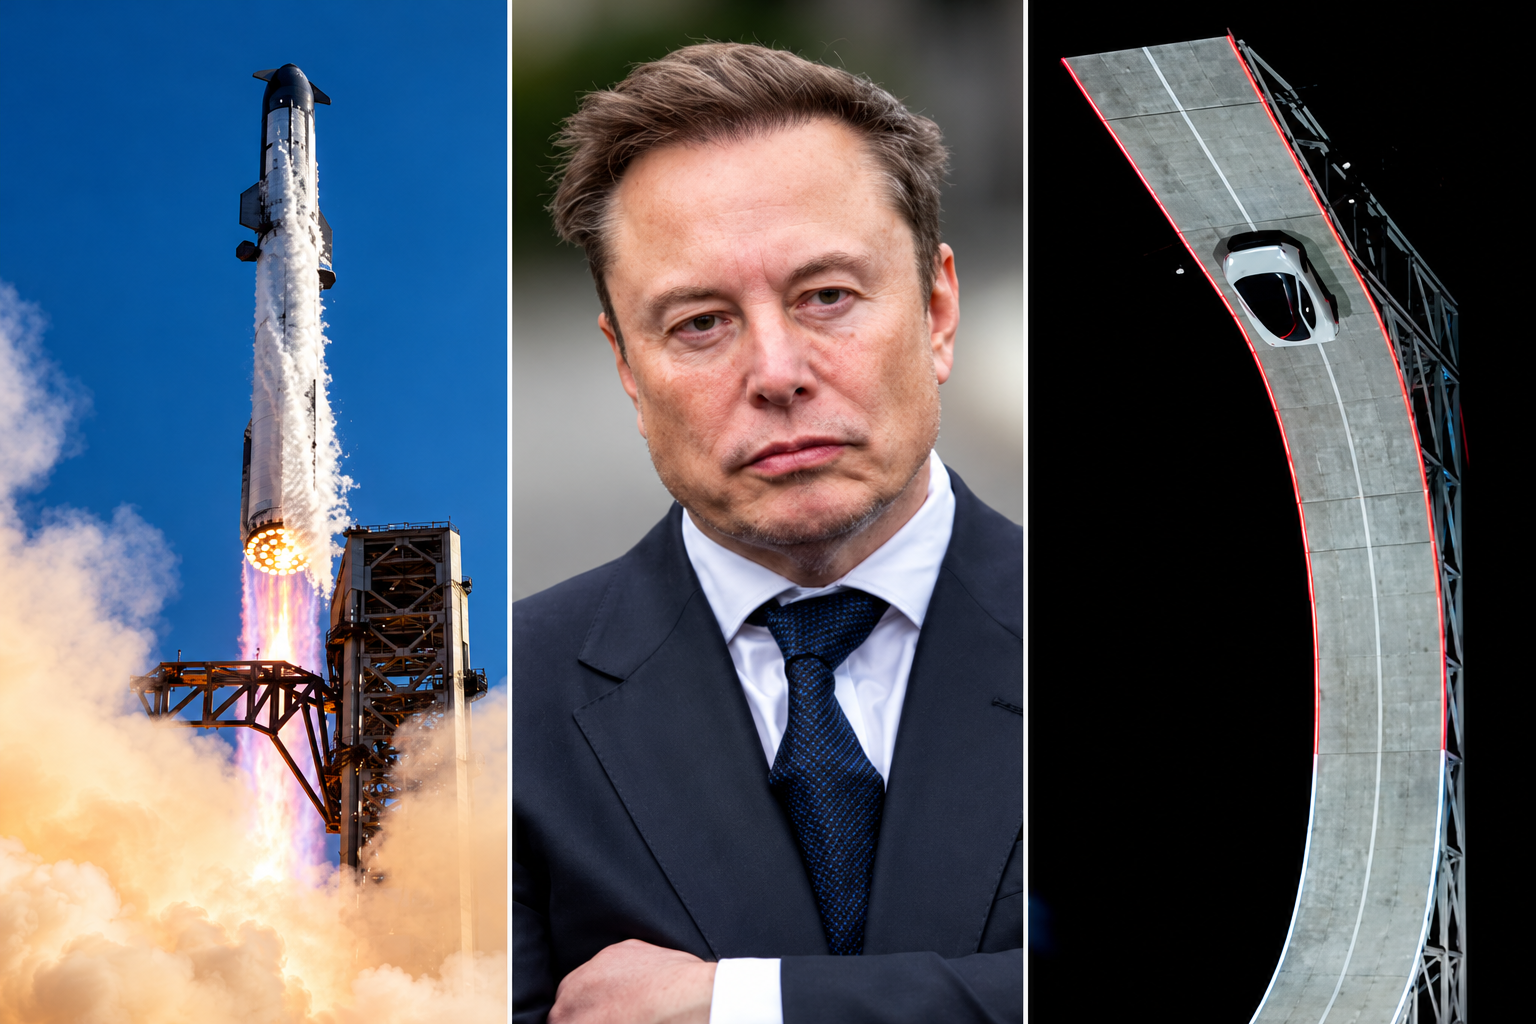
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.