

Natural disasters are changing attitudes to long term property values
Australian property values usually rebound quickly after natural disasters, but not this time
 2 min
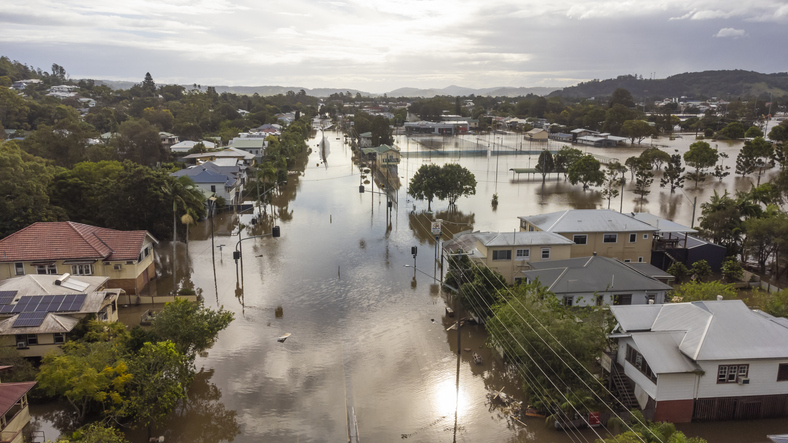
Flooding is beginning to have long term effects on property values, a new report from CoreLogic reveals.
The East Coast Floods – One Year One report examined the impacts of the extreme weather events on the Richmond-Tweed area (also known as the Northern Rivers region) on the far north coast of NSW, as well as the Brisbane region in early 2022, which some described as a ‘rain bomb’.
The report, authored by Corelogic economist Kaytlin Ezzy, said while residential values were historically fairly resilient following flooding events, recovering within three to five years, the 2022 disaster had changed perceptions among homeowners and potential buyers.
“Attitudes towards flood-prone areas, and climate risk in general, are changing,” the report said. “Homeowners, lenders and insurers are becoming more cautious of the risks associated with climate change and are adjusting their risk premiums accordingly. For some impacted homeowners, the risk of another flood is likely to be top of mind, and we could see a number of residents accept government buy-back offers where they are available.
“For others, the increased costs of insurance could price out existing owners and dissuade new buyers from areas vulnerable to flooding.”
The report noted that while the Insurance Council of Australia had closed 80 percent of claims from the events, which are estimated to have cost $5.7 billion – Australia’s most expensive natural disaster on record – that was only part of the story.
“A sizable number of people are still waiting for building repairs to start, while other uninsured residents have been left with limited resources to undertake repairs,” the report said. “Government intentions around buy backs are still playing out and the number of post flood home sales is still low.
“The full impact of the floods won’t be known until these factors have played out.”
Using satellite imagery, CoreLogic has zeroed in on areas most affected by floods. Perhaps unsurprisingly, flood-prone areas such as South Lismore and North Lismore recorded flooding across 80.8 percent and 70.1 percent of properties respectively. The news was similarly grim in West Ballina, where 56 percent of properties were impacted.
However, areas considered low risk, such as Girards Hill (35.1 percent) and East Lismore (22.4 percent) were also heavily affected.
In the Byron Bay region, Mullumbimby experienced the highest numbers, with 17.4 percent of properties impacted by flooding.
The impact on values has been immediate, and not just in those areas directly affected by floods, CoreLogic data reveals.
“Mullumbimby recorded the largest 12-month decline nationally, down -30.1 percent, roughly equivalent to a $432,000 decline in the median value, followed by South Lismore (-27.0 percent), Ocean Shores (-26.8 percent) and Byron Bay (-25.4 percent). The other impacted suburbs saw values fall between -22 percent and -25 percent,” the report said.
“Interestingly, a number of suburbs that were relatively unimpacted by flooding also recorded significant declines. Values across Bangalow, Lismore Heights and Suffolk Park fell by -28.4 percent, -25.7 percent, and -24.3 percent, respectively, and East Ballina and Alstonville recorded slightly smaller declines of -20.2 percent and -19.6 percent.”
While it noted that reduced economic activity across the whole region was a likely contributing factor, the report said that the decline had been less in Lismore’s elevated suburbs of Goonellabah which recorded a milder -7.2 percent drop in values, as well as a number of surrounding farming communities where declines were less severe.
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.
Located steps from Crows Nest Metro, the near-complete development brings luxury living to Sydney’s Lower North Shore.
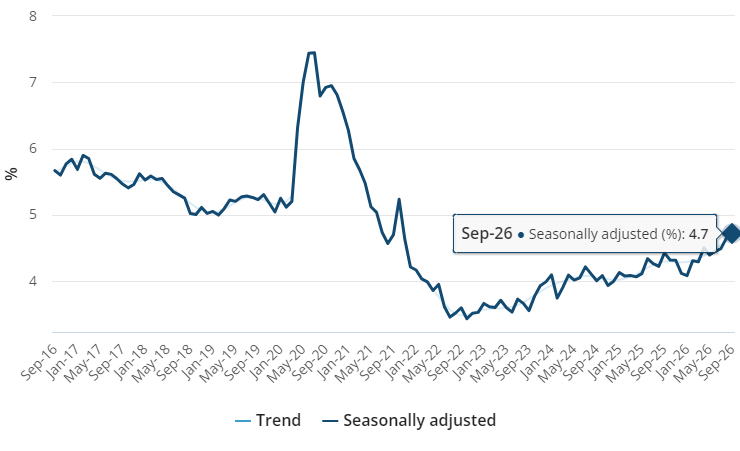
Employment fell by 39,300 and unemployment held at a revised 4.7 per cent, giving the RBA more room to pause in November.
2 min
Australia’s labour market weakened in September, reducing—but not eliminating—the case for another Reserve Bank rate rise in November.
The seasonally adjusted unemployment rate was 4.7 per cent, according to the Australian Bureau of Statistics. August was revised to the same level, while September employment fell by 39,300 people. The number of unemployed Australians increased by 8,900 to 732,000.
The weakness extended beyond the headline rate. The employment-to-population ratio fell 0.3 percentage points to 63.6 per cent, participation declined 0.2 points to 66.8 per cent and underemployment edged up to 6.3 per cent. Part-time employment fell by 73,700, partly offset by a 34,400 increase in full-time work.
For the RBA, this is a clearer sign that restrictive monetary policy is cooling demand. Higher unemployment and falling employment reduce wage pressure over time and increase the risk that another rate rise would push the economy harder than necessary.
That makes a November increase less certain. It does not make a hold inevitable. The RBA must balance labour-market softness against inflation, and the September-quarter consumer price index due later in October will carry more direct weight in the decision.
For mortgage holders and property investors, the practical conclusion is not to trade one data release. Borrowers should continue testing repayments at higher rates, preserve liquidity and avoid basing a purchase on an assumed near-term reversal. Refinancing decisions should be assessed against total cost, not simply the advertised rate.
Property markets may initially welcome a reduced probability of another increase because borrowing capacity and sentiment are highly rate-sensitive. But a weakening labour market is not unambiguously positive for housing: job security supports mortgage serviceability, rental demand and buyer confidence.
The September numbers have given the RBA a credible reason to wait. Inflation will determine whether it can use it.
Australia’s housing market defies forecasts as prices surge past pandemic-era benchmarks.
A haven for hedge-fund titans and Hollywood grandees, Greenwich is one of the world’s most expensive residential enclaves, where eye-watering prices meet unapologetic grandeur.