Australian mortgage holders defying predictions and managing debt
However, there is one group spending their savings at a faster rate than the rest
 3 min
The number of home loans in arrears are less than one percent of all borrowers, defying predictions of dire outcomes from a ‘mortgage cliff’ and the impact of high interest rates and cost of living pressures.
Most borrowers are making their home loan repayments on time, and although the number of loans in arrears has increased since late 2022, they represent only a tiny portion of the market, according to the Reserve Bank (RBA). Less than 1 percent of all housing loans are 90 or more days in arrears, which is lower than the pre-pandemic peak.
In its latest Financial Stability Review released this month, the RBA said households remain under pressure from high inflation and interest rates, with consumer sentiment very weak. More Australians than usual are seeking support from community organisations, and lenders have a small but rising number of borrowers on temporary hardship arrangements.
“Based on their latest assessment of the economic outlook, banks expect arrears rates to increase a bit further from here but remain low relative to history,” the RBA said.
The RBA notes that since the start of 2022, real disposable income has fallen by about 7 percent to be near its pre-pandemic level in per capita terms. Most mortgagors have seen 30-60 percent increases in their minimum home loan repayments since rates began rising in May 2022. However, only about 5 percent of variable-rate owner-occupier borrowers today have expenses exceeding incomes, giving them a cash flow shortfall.
Households are coping well due to a strong labour market, which is allowing them to increase their hours or get a second job if necessary. They are also drawing on large savings buffers, partly created by pandemic stimulus and lower spending during lockdowns, and have reduced their discretionary spending as necessary.
The loan arrears rate is highest among highly leveraged borrowers, however it is still very small at less than 2 percent. The share of mortgagors estimated to have a cash flow shortfall combined with low savings has risen over the past two years but still represents less than 2 percent of variable-rate owner-occupier borrowers. Unusually, the arrears rate among recent first home buyers is lower than average, possibly reflecting the Bank of Mum and Dad enabling young buyers to purchase properties with less debt.
The arrears rate among borrowers who rolled over from low fixed rates to variable rates in one hit – an event labelled ‘the mortgage cliff’ which was expected to hit hardest late last year – are managing their repayments just as well as other borrowers. “This resilience partly reflects that these borrowers were able to build up savings buffers over a longer period of unusually low interest rates,” the RBA said.
High income earners are depleting their pandemic savings at the fastest rate because they tend to be servicing greater debt. But they still have the highest savings and are likely using some of it to support continued discretionary spending. Conversely, the lowest-income mortgaged households grew their savings in 2023.
The RBA says nearly all borrowers should be able to service their loans even if inflation is more persistent than expected and interest rates remain higher for longer. While the RBA expects a rise in unemployment, it noted that historically mortgagors are less likely to lose their jobs. Many mortgagor households also have multiple incomes, and about half of all borrowers have enough savings to service their debts and essential expenses for at least six months. Lenders can also offer temporary support to borrowers who lose their jobs.
The RBA said most borrowers also have strong equity positions, which protects them from default and limits risk for lenders. Rising property prices last year gave homeowners more equity and banks have been issuing fewer high loan-to-value (LVR) loans since 2021. These types of loans are now at near-historical low levels.
“The share of loans (by number or balances) estimated to be in negative equity at current housing prices remains very low,” the RBA said. “While usually a last resort and very disruptive for owner-occupier borrowers, this would allow almost all borrowers to sell their properties and repay their loans in full before defaulting.”
Hypothetically, in a severe economic downturn during which housing values fell 30 percent, the RBA estimates that the share of loans falling into negative equity would increase to about 11 percent. The RBA said significant losses for lenders would only materialise if more borrowers became unable to service their loans.
The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
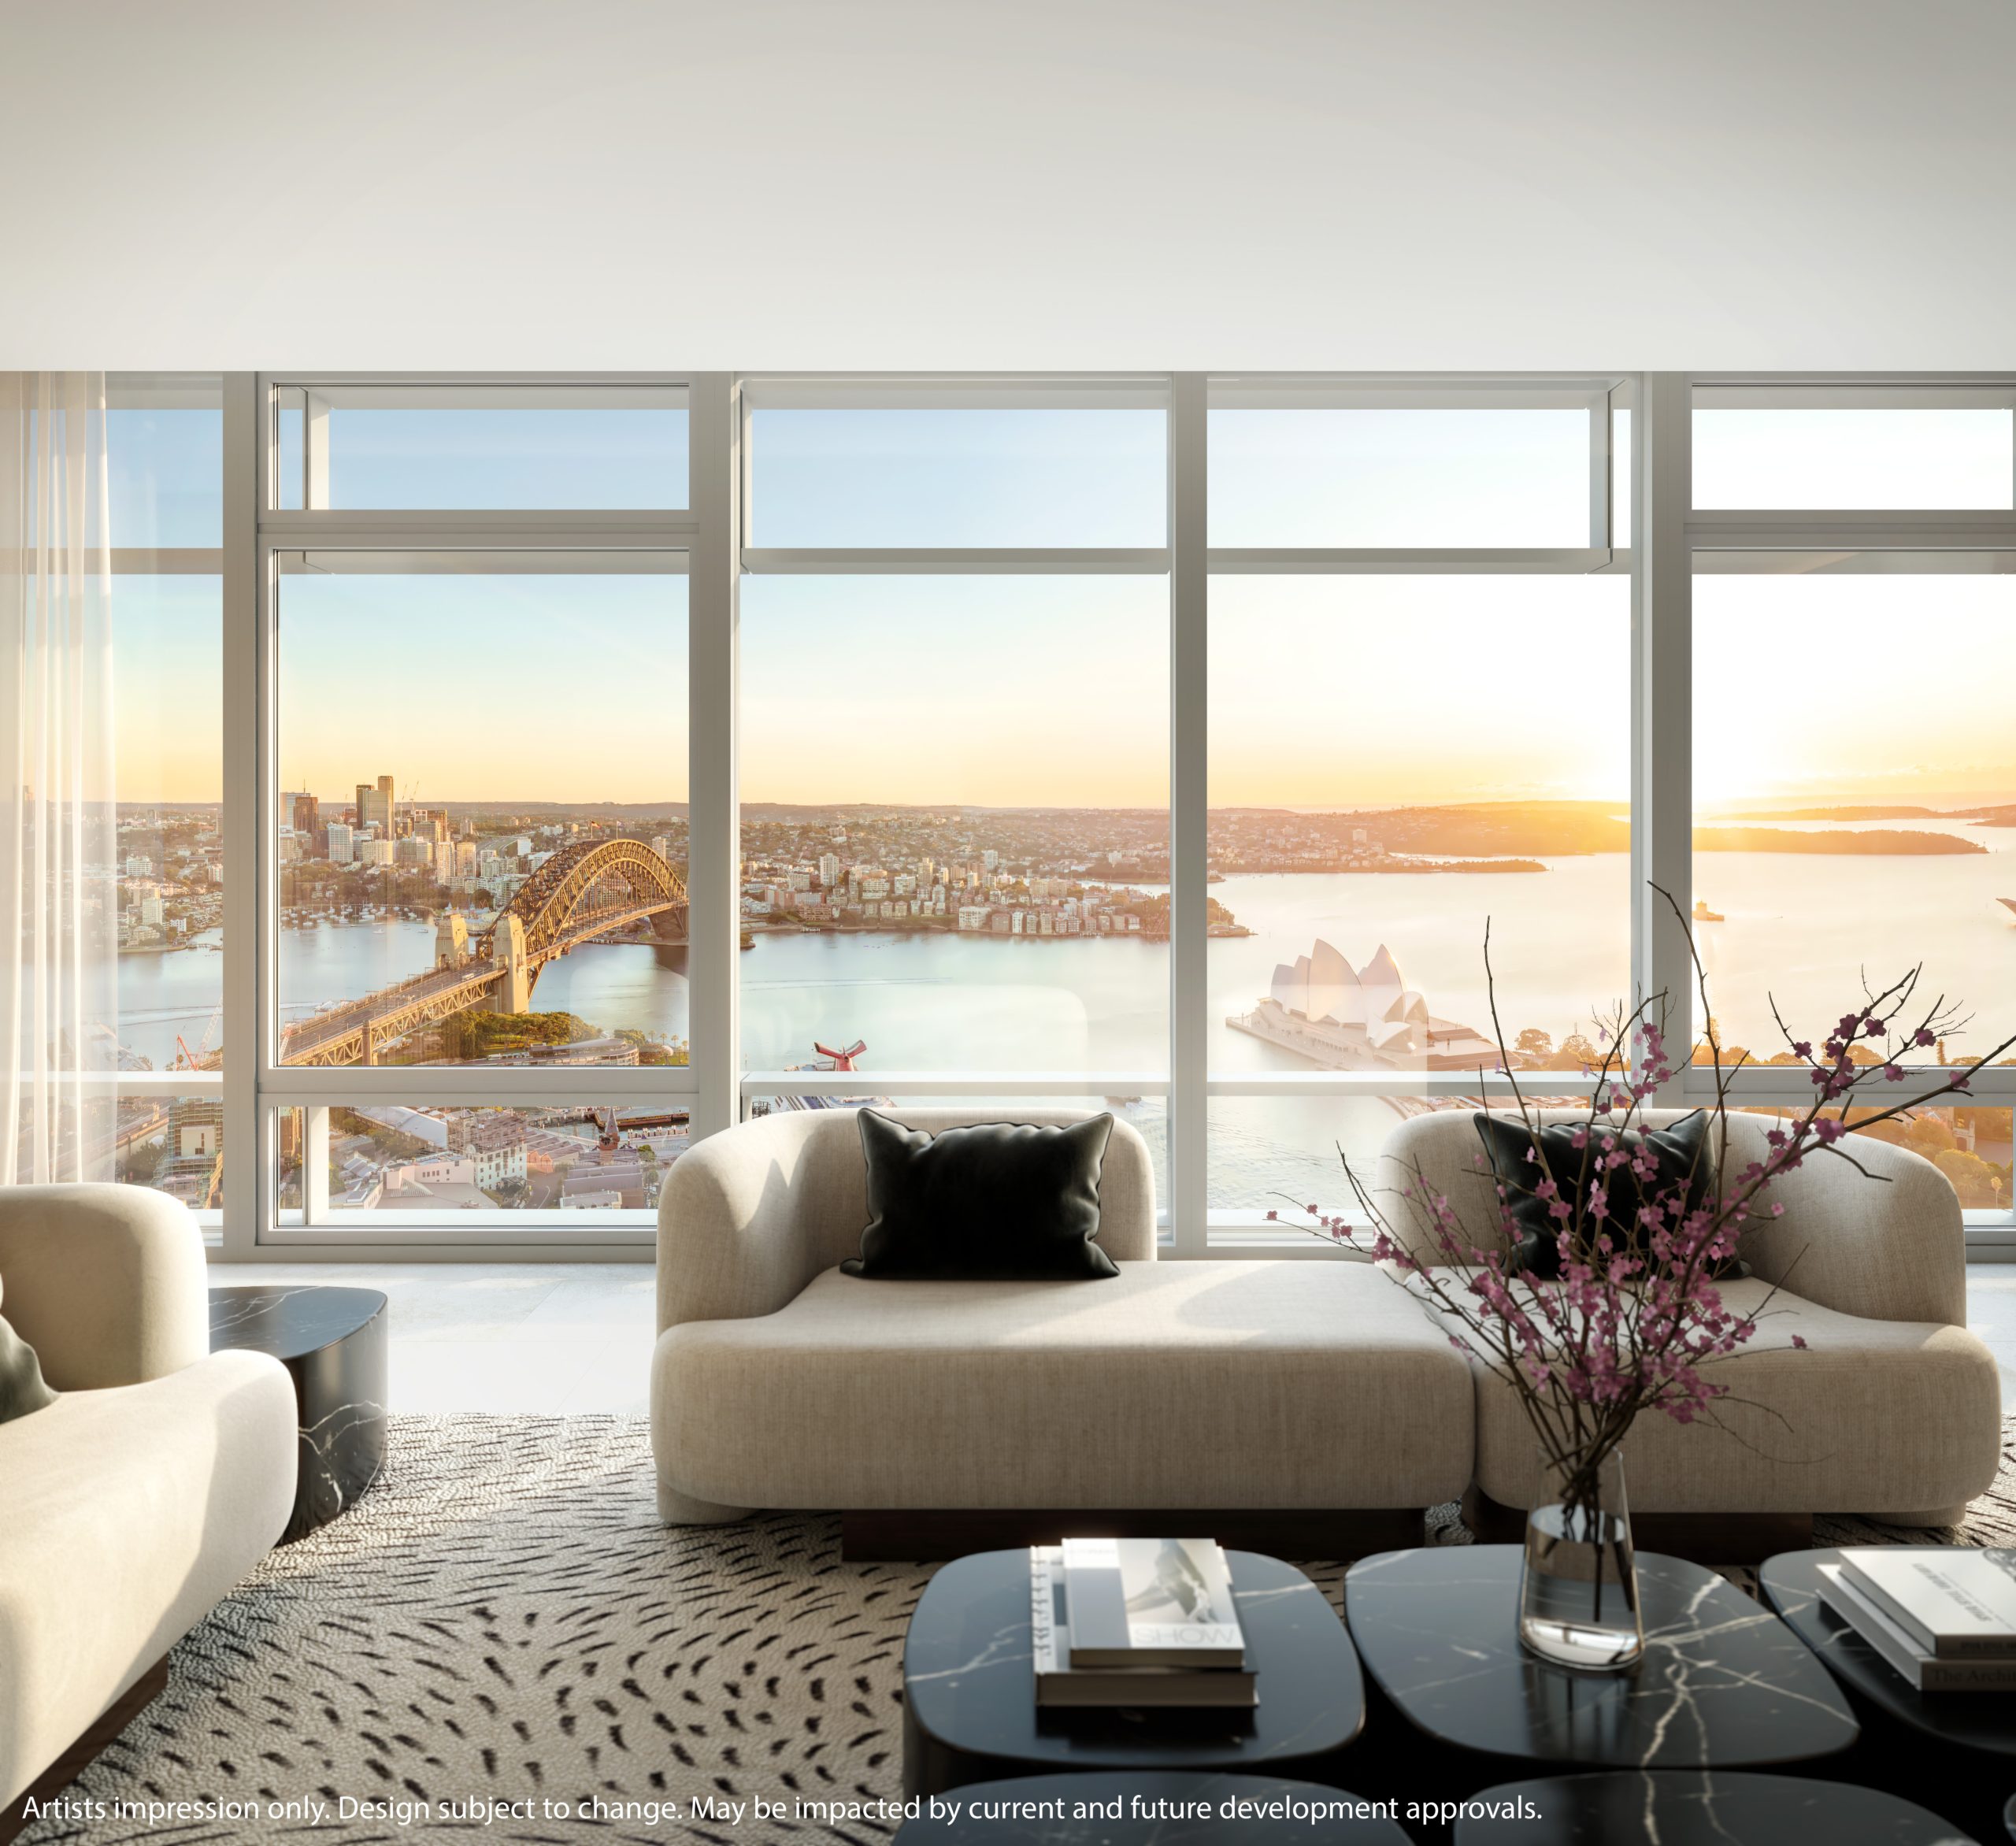
More than 10,000 homes, an expansive central park and a mix of hospitality, retail and wellness facilities will form Azizi Developments’ first master-planned community in the emirate.
2 min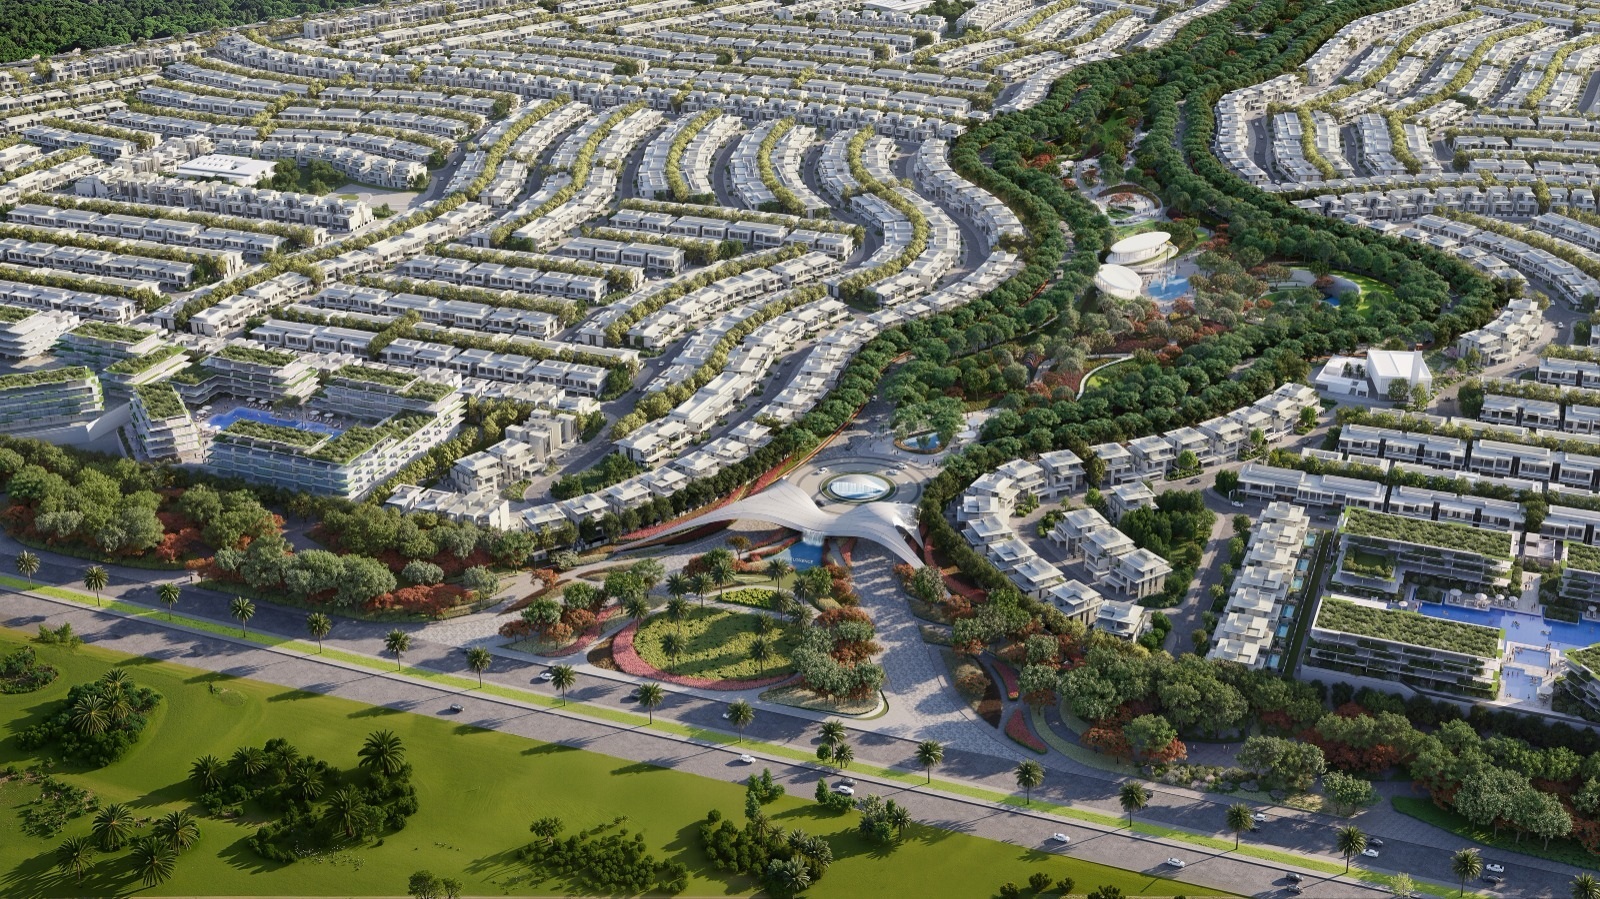
Sharjah is set to receive one of its largest new residential communities, with Azizi Developments unveiling plans for a US$8.1 billion master-planned precinct containing more than 10,000 homes.
Named Azizi Florence, the freehold development will comprise 1,130 villas, more than 6,000 townhouses and 3,500 apartments. Three-bedroom townhouses will start from US$515,000, with an indicative rate of US$231 per square foot of saleable space.
The project marks the Dubai-based developer’s first move into Sharjah, expanding a portfolio that includes the planned Burj Azizi skyscraper and the Azizi Venice community in Dubai.
A park at the heart of the community
Rather than treating landscaping as an afterthought, Azizi Florence will be organised around a 1.7 million sq ft central park.
The wider precinct is planned as a self-contained neighbourhood combining homes with retail, hospitality, education, leisure and wellness facilities.
Six residential clusters will sit within the development, each with its own park, clubhouse, community centre and landscaped gardens. The approach reflects a broader shift across large Middle Eastern developments, where greenery, recreation and everyday convenience are increasingly central to the residential proposition.
The scale of Azizi Florence suggests it is intended to function as a neighbourhood rather than a collection of housing estates. Its mix of housing types should also give the project broader appeal, accommodating apartment buyers alongside families seeking townhouses or standalone villas.
Azizi expands beyond Dubai
Azizi Developments has delivered more than 45,000 homes to buyers from over 100 countries and says it has approximately 150,000 units under construction.
Much of its growth has been concentrated in Dubai, where its portfolio extends across Palm Jumeirah, Mohammed Bin Rashid City, Dubai South, Sheikh Zayed Road and Downtown Jebel Ali.
Its most prominent current project is Burj Azizi, which is intended to become the world’s second-tallest building. Azizi Florence represents a different type of undertaking: a low-rise, family-oriented community built around public space and daily amenity.
For company founder and chairman Mirwais Azizi, the Sharjah project also carries a personal connection. The emirate was his first home in the UAE more than three decades ago, adding a symbolic dimension to the developer’s expansion.
Sharjah’s residential ambitions grow
Although Dubai and Abu Dhabi have traditionally captured much of the international attention directed at the UAE property market, Sharjah has been steadily broadening its residential offering.
Large freehold communities such as Azizi Florence have the potential to attract both local families and international purchasers looking for comparatively accessible entry points into the Emirates’ property market.
At a starting price of US$515,000, the project’s three-bedroom townhouses will sit well below the cost of equivalent family homes in many of Dubai’s more established luxury communities.
The ultimate appeal, however, will depend on execution. At this scale, the quality of the public realm, connections between residential clusters and delivery of the promised supporting infrastructure will be as important as the homes themselves.
If those elements come together, Azizi Florence could help establish a new benchmark for large-scale residential development in Sharjah—and give buyers another option beyond the UAE’s better-known property markets.

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.

A survey of people with at least $1 million in investable assets found women in their 30s and 40s look nothing like older generations in terms of assets and priorities