The best suburbs for investment opportunities in Australia in 2025
There’s money to be made in the property market — if you know where to look.
 2 min
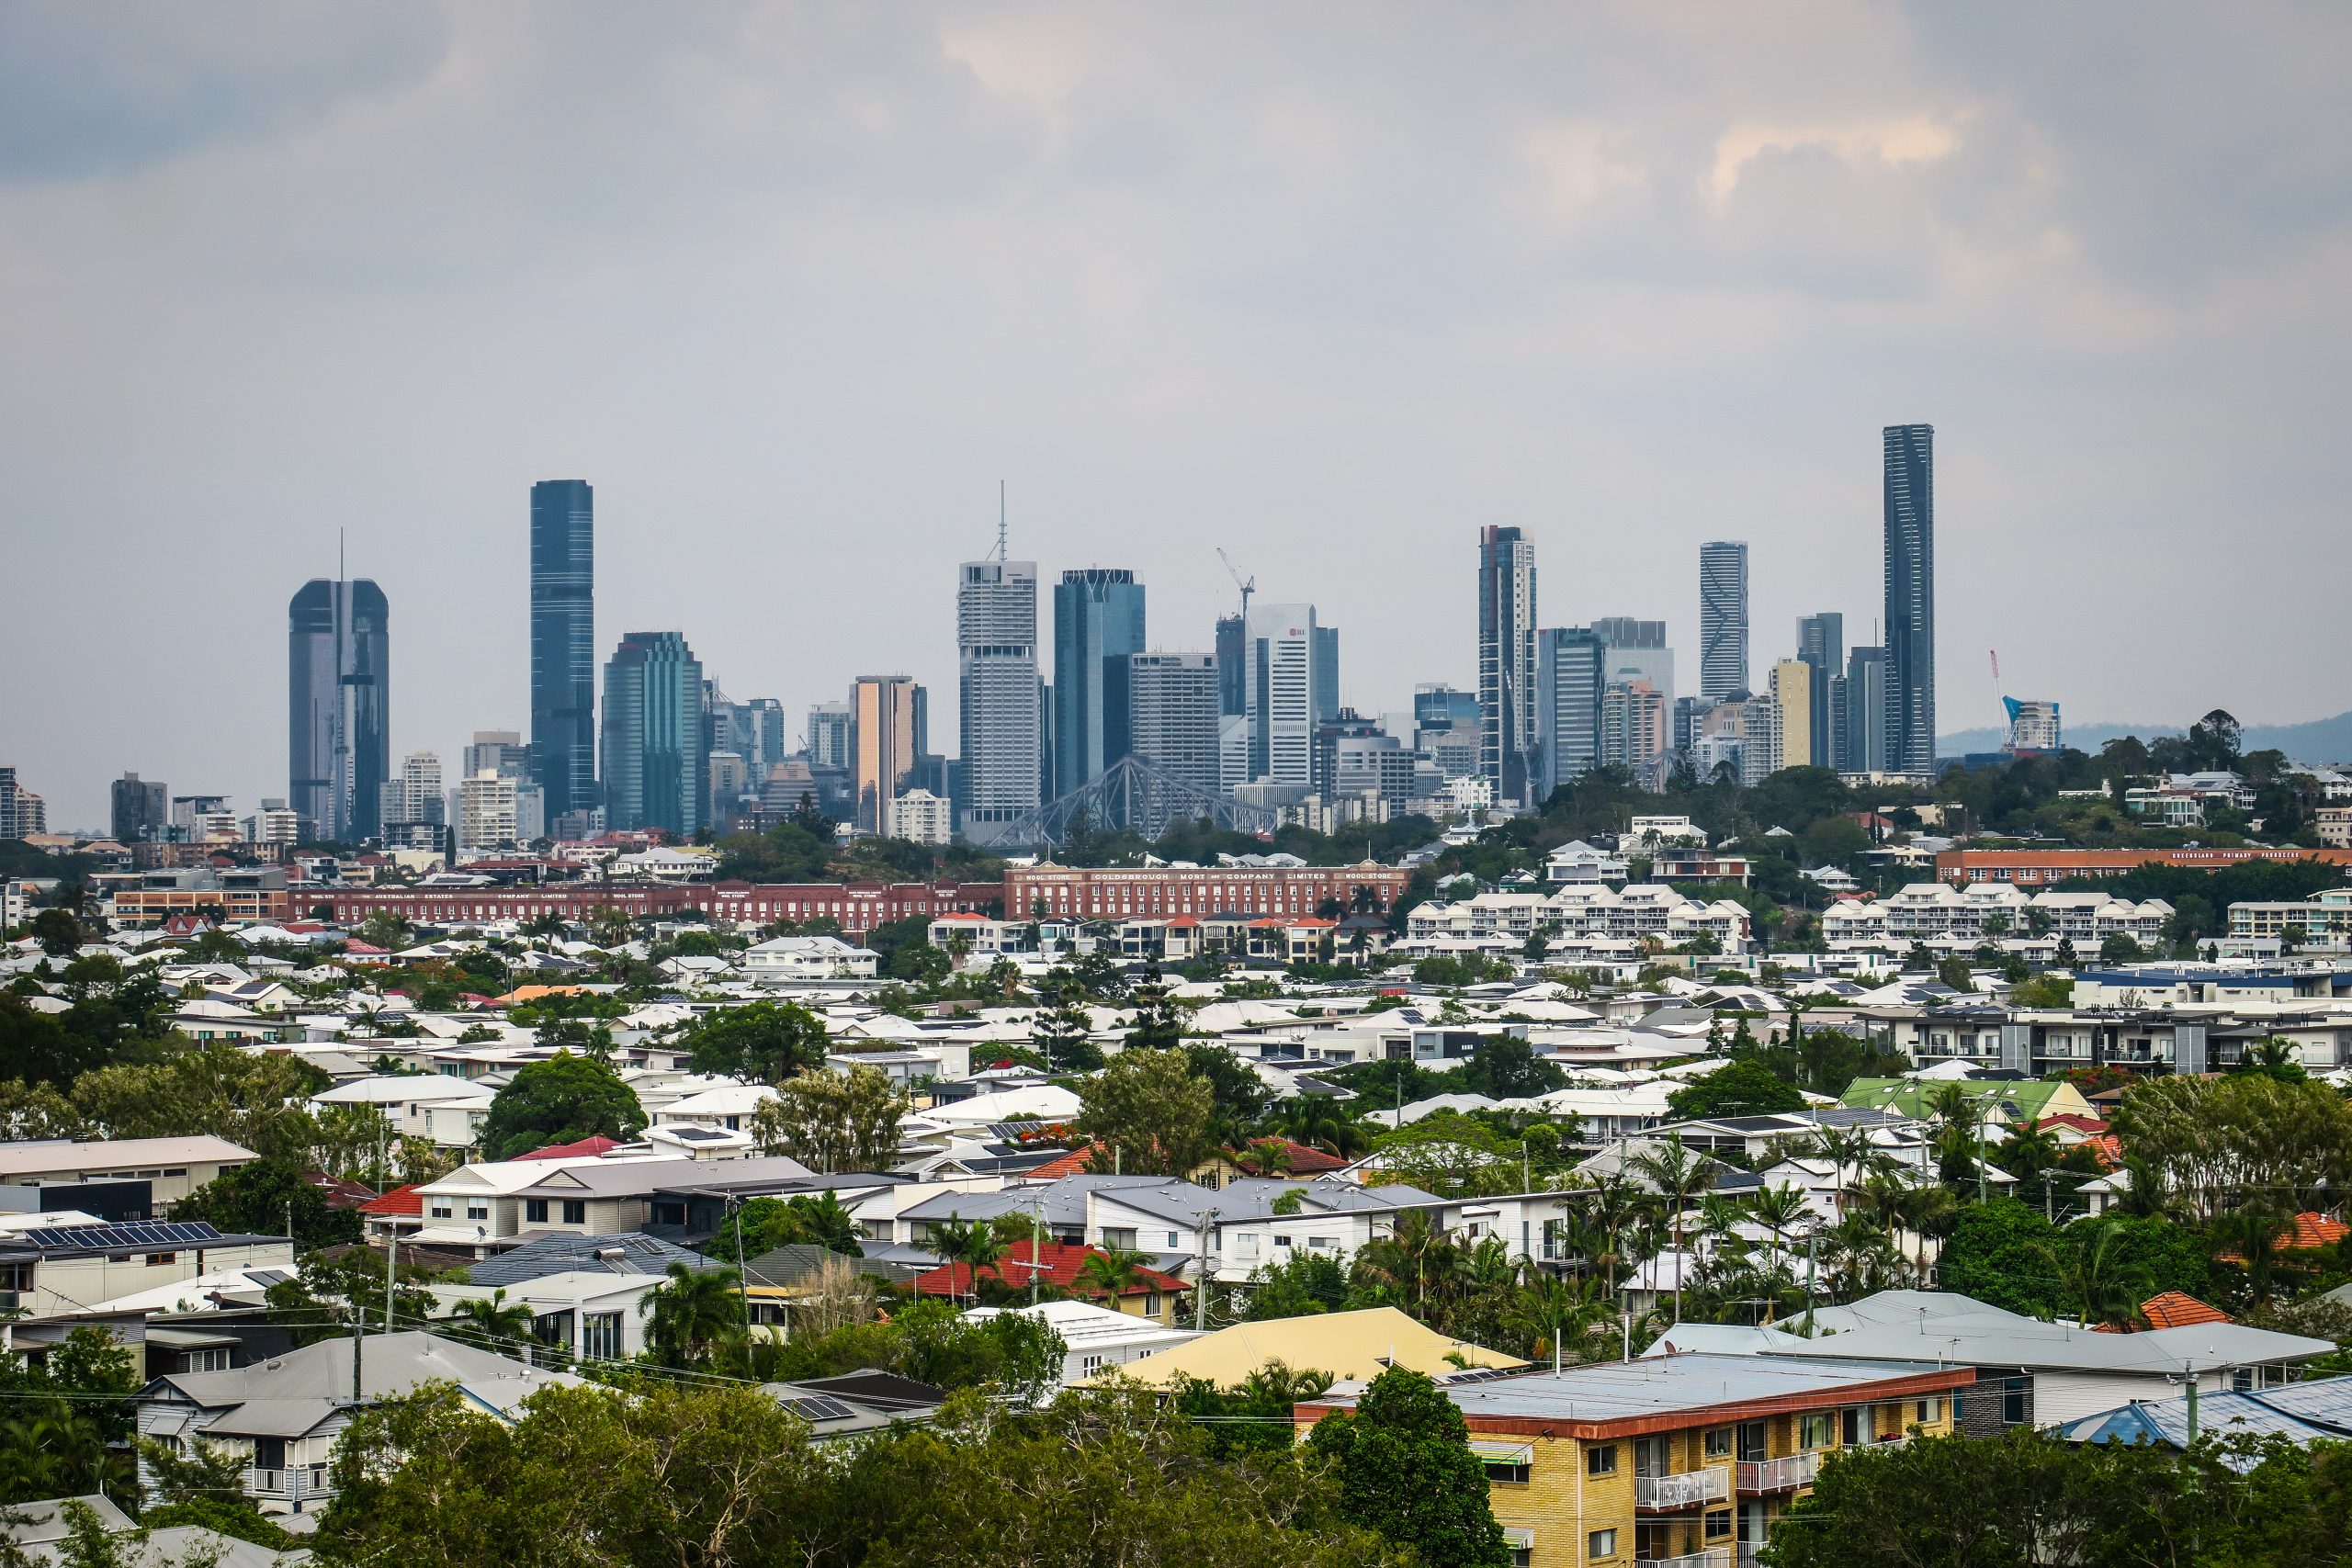
If you’re a first homebuyer, owner/occupier or investor, you might feel that the property market is slim pickings in some of your favourite city suburbs. Either there’s no supply or the reserve is well above your budget threshold. However, for those property-savvy individuals prepared to look harder, there’s a growing number of suburbs in Australia’s major cities that are proving to be great investment opportunities…
—…you just need to know where to find them.
Independently-owned real estate agency, Little Real Estate, has released its annual report for the best Australian suburbs for investing. Investors searching for affordability, cash flow, and capital growth potential are being encouraged to consider regional locations, including four in Queensland.
“In 2024, we anticipate a surge in property prices fuelled by the relentless demand for housing outpacing the available supply,” says Little Real Estate executive general manager of sales, James Kirkland. “An exceptionally strong rental market, coupled with a shortage of housing, continues to exert upward pressure on house prices nationwide.”
Real estate analyst Hotspotting’s National Top 10 Positive Cashflow Hotspots echoes the findings of Little Real Estate’s annual report. Its analysis found that Queensland locations showed exponential capital growth, with the Sunshine State securing half of the top 10 locations.
“Cash flow has become increasingly important over the past two years, given the much higher mortgage repayments in play,” says Hotspotting director, Terry Ryder. “It is imperative that investors seek out areas that also offer capital growth prospects, often due to their booming local economies across a diverse range of industries.”
—
Which location is best for a property investment?
It depends! According to Little Real Estate, in 2024, the Sydney suburbs of Wiley Park and Kensington come out on top, along with Caloundra West and Southport in South East Queensland, and Carlton and Moonee Ponds in Melbourne.
What is the most in-demand suburb in Sydney?
The property market is certainly inflated in Sydney in comparison to other states but investors can still find some gems in certain pockets of the city. Take Penrith, for example. According to REA data, the average cost of a unit in Penrith costs $540,000, with a rental yield of 4.3%.
Which state is best for investment property in Australia?
It’s hard to go past Queensland as one of Australia’s best states for investment properties. With four out of ten suburbs in Queensland appearing in Little Real Estate’s annual report—including Southport, Caloundra West, Coomera and Bulimba—Queensland and its surrounding suburbs, typically regional, are presenting as great investment opportunities.
“Whether you’re an investor, a family looking for a new home, or a professional seeking the ideal work-life balance, these suburbs are the ones to watch for growth and potential in the upcoming year,” says Kirkland.
What is the fastest growing suburb in Australia?
According to Smart Property Investment, the fastest growing suburb in Australia is Chelmer, Queensland – a south-western suburb in the city of Brisbane, with a quarterly price growth of 29.33 per ent. This is followed closely by Frenchs Forrest in NSW, and Greenmount in Queensland.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.

Parts for iPhones to cost more owing to surging demand from AI companies.
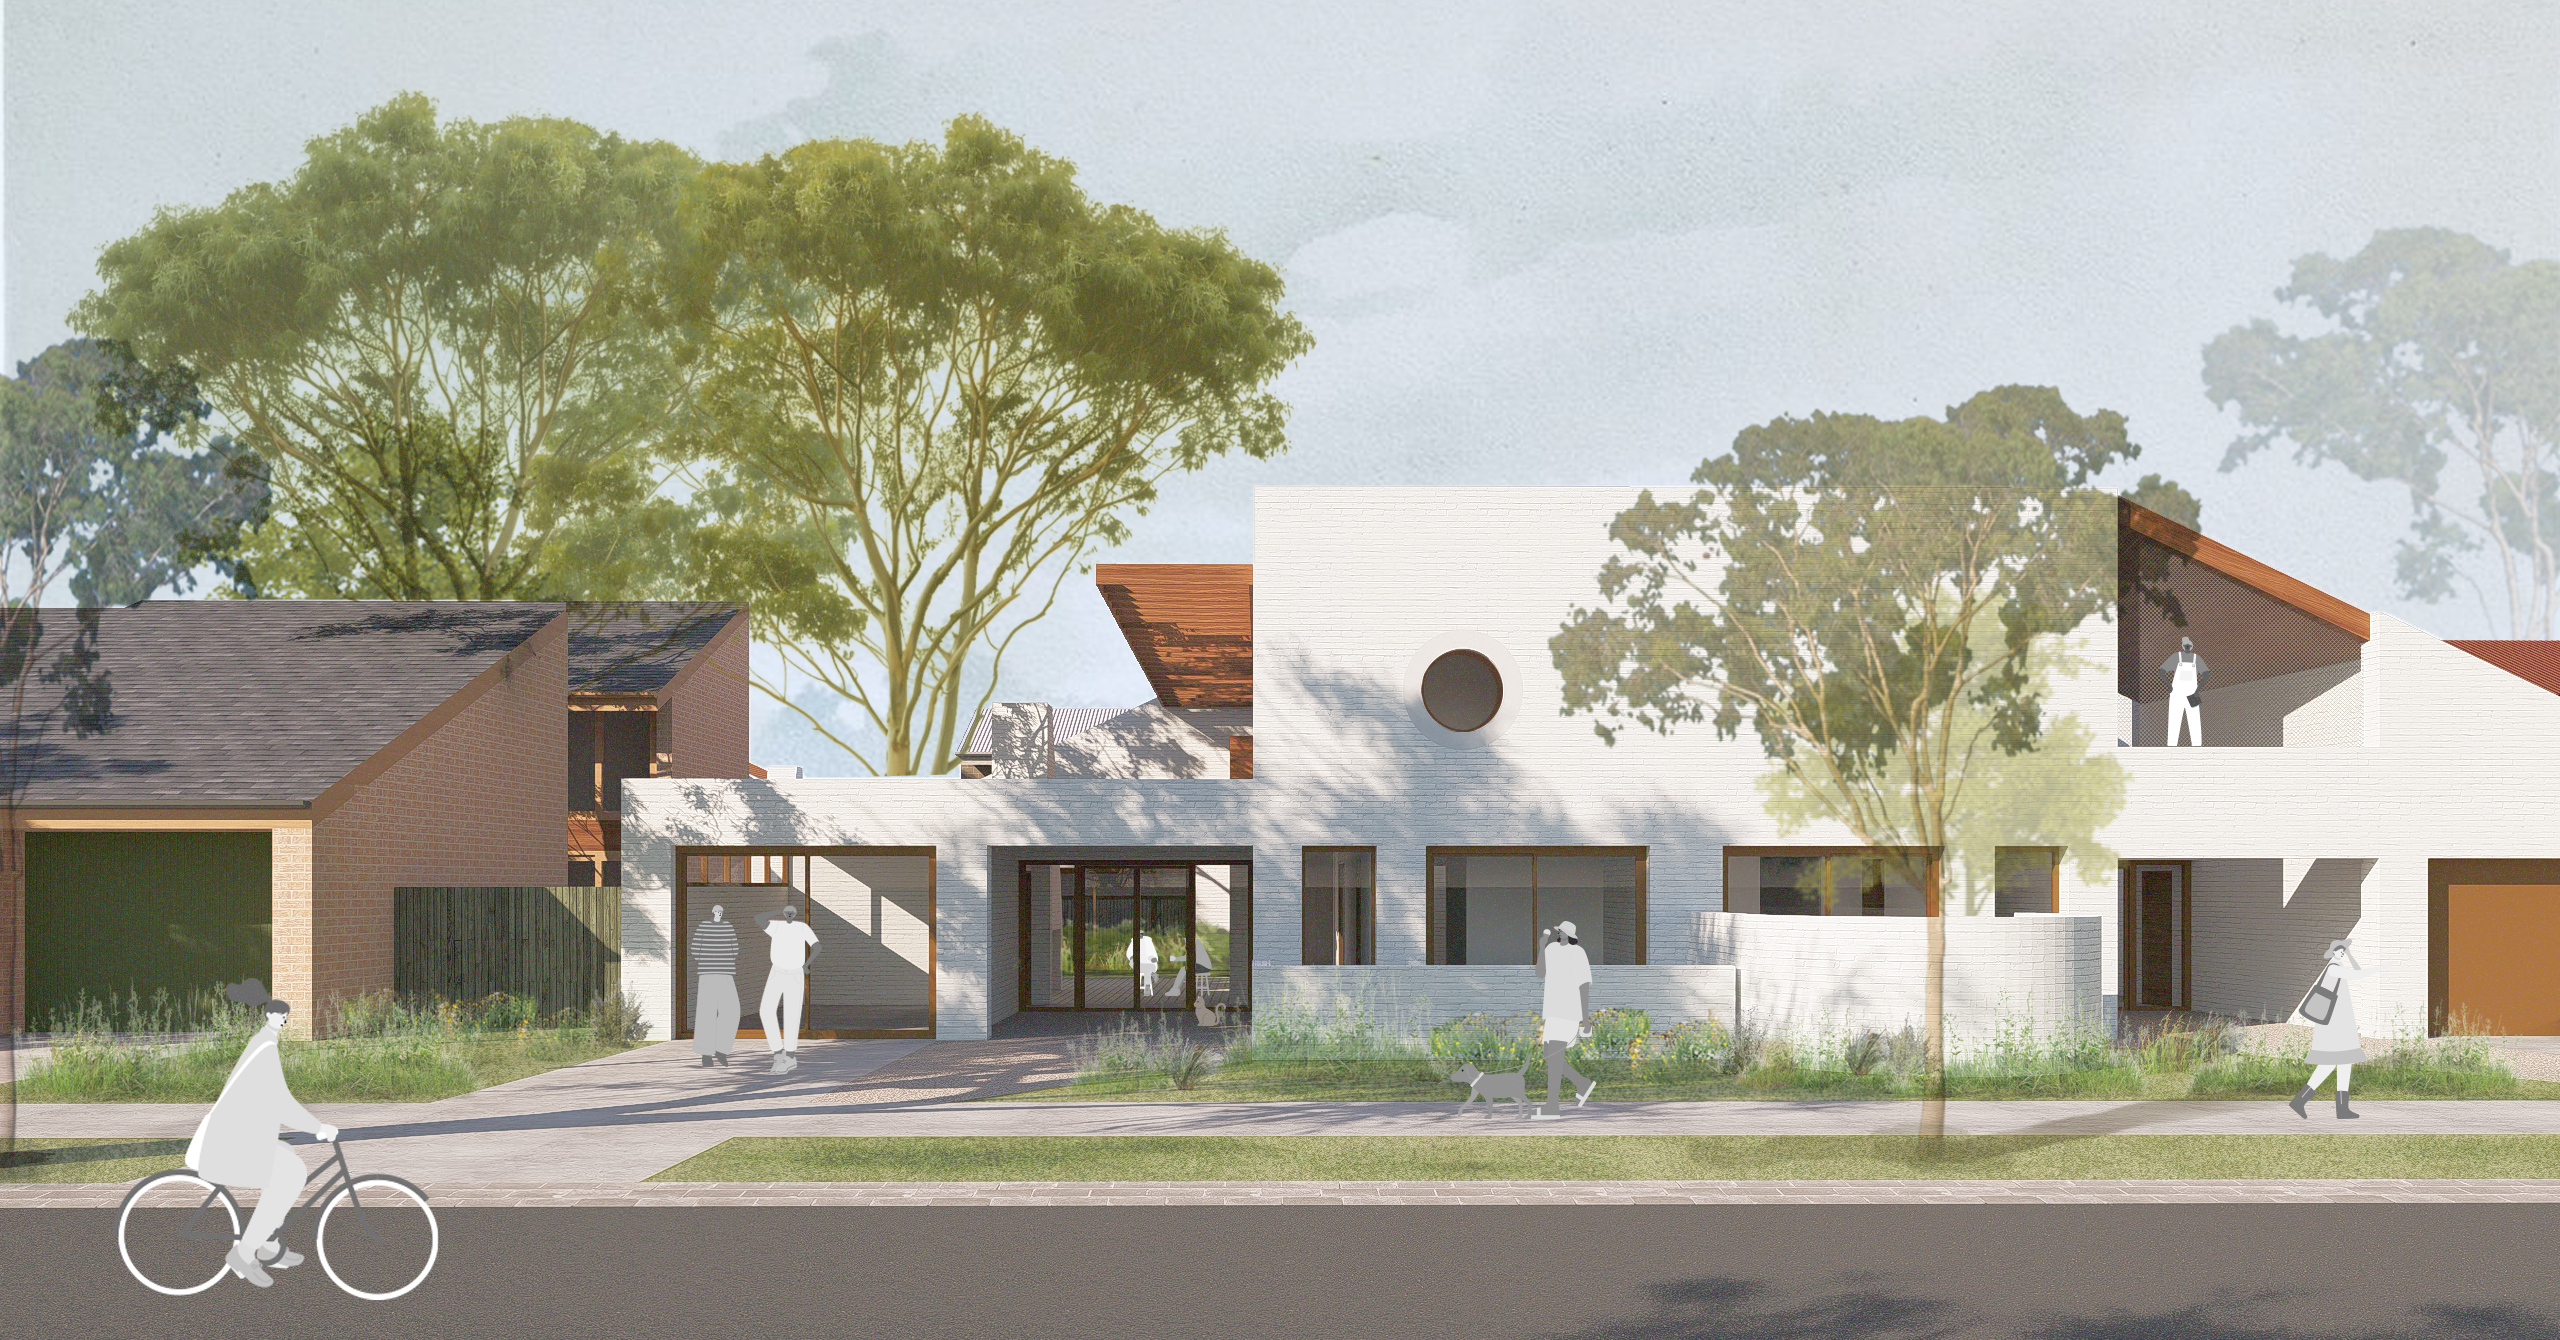
Brickworks has enlisted acclaimed architecture studio Kennedy Nolan to explore how homes could become more adaptable, energy-efficient and connected to community.