

The Spectacular Crash of a $30 Billion Property Empire

 8 min
René Benko was a high school dropout and convicted criminal. But by 2018, he was at the pinnacle of global real estate.
His company, Signa Holding, launched a glassy, J-shaped skyscraper on the banks of the River Elbe in Hamburg, Germany. The design of the 800-foot tower resembled a chart showing exponential growth. Hamburg’s mayor, the future German Chancellor Olaf Scholz , lauded Signa’s good reputation with banks when the city picked the developer to build the tower.
“Signa is financially strong,” he said. It wasn’t.
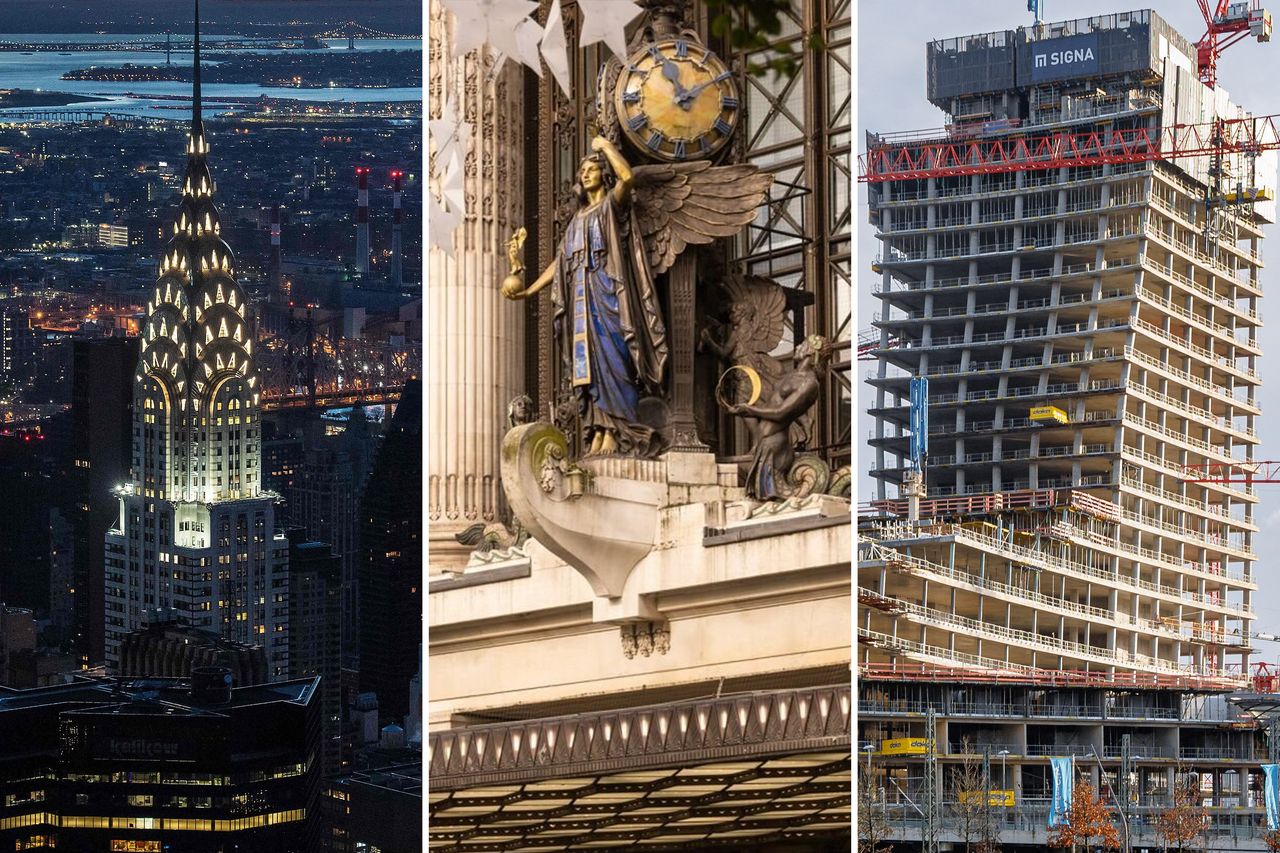
Benko’s sprawling, $30 billion empire of trophy real estate and department stores has imploded into the biggest property bankruptcy in Europe since the global financial crisis. The mess threatens to unleash significant losses on scores of lenders and investors and freeze half-built developments in numerous city centers. Stakes in Manhattan’s Chrysler building , upscale British retailer Selfridges and sporting- goods groups in the U.S. and Europe face the block. Auctioneers are selling off Signa’s bookshelves, doormats, 700-bottle wine collection and a diamond-shaped award for Europe’s 2021 real-estate brand of the year.
The Hamburg tower is halted—leaving a 330-foot tall concrete stump. The unravelling marks a dramatic reversal for the self-made entrepreneur, who once lavished backers with hops on his yacht, a top-of-the-line Bombardier Global Express jet and trips to Signa’s multiple Austrian hunting grounds, complete with a shooting guide on the company payroll.
Left tallying their losses are heirs to the Tetra-Pak and Peugeot family fortunes; billionaire Ron Burkle ; and marquee sovereign-wealth funds from Singapore, Saudi Arabia and the United Arab Emirates. Dozens of banks lent money, including Citigroup and Swiss bank Julius Baer, whose chief executive resigned on Feb. 1 after the bank wrote off $700 million on loans tied to Signa. Spokespeople for Citigroup, Julius Baer, Peugeot Invest , Singapore’s GIC, and the UAE’s Mubadala declined to comment. The others didn’t respond to requests for comment.
Insolvency administrators say they are still getting to the bottom of the group’s corporate structure. But public filings, investors and former employees paint a picture of an empire that combined persuasive salesmanship with extreme financial engineering—an unsteady foundation that crumbled when the low interest rate era ended. In fundraising presentations, Signa told investors it was offering conservative, low-debt investments in iconic properties to be held for generations. Investors said they have since learned through Signa’s legal filings the companies had far more debt than they knew.
Many were invested in discrete parts of the larger company, unaware of convoluted cross-investments and large amounts of borrowing across hundreds of vehicles. An attorney for Benko said a list of questions sent by The Wall Street Journal contained “credit-damaging” and inaccurate allegations, but declined to provide specifics.
Some of Benko’s associates disagree that Signa’s structure was at fault, but rather see the implosion as a result of herd behaviour by lenders. Former Austrian Chancellor Alfred Gusenbauer, who served on Signa company boards, told Austrian state radio in January that the group overextended in retail, draining cash, and that the European Central Bank told banks not to provide more financing. ECB supervisory board chairman Andrea Enria has called that suggestion bizarre, and said Signa wasn’t targeted, but rather part of a broader examination of banks’ commercial real-estate exposure.
Benko, 46, was raised with modest means in Innsbruck, the quaint Austrian city nestled in the Alps. He was a star junior indoor climber and, at 17, dropped out of high school and began converting attic lofts, he has said in Austrian media interviews. He said he raised money from an heir to a gas station fortune, and quickly built up his business, expanding throughout the 2000s. He ran into trouble in 2012, convicted of an elaborate scheme in which prosecutors said he commissioned a former Croatian prime minister to push Italian officials including Prime Minister Silvio Berlusconi to help contest a tax bill on Signa-owned Italian properties.
Though the tax bill wasn’t reduced and the court said money never changed hands, a judge called it a “model case of corruption,” Austrian media reported at the time. Benko was sentenced to the equivalent of probation. It could easily have been a fatal business blow. Such convictions are typically toxic in the eyes of the large lenders and major investors that fuel the market. Instead, Benko trained his salesman skills at wealthy European families who could be swayed by his personal pitch, former employees said. He met scions of one family fortune after another for dinners over glasses of Château Lynch-Bages, which sells for $200 a bottle, they said. He plopped down a specially made hard-bound book half the size of his desk. Paging through photos of property after property, he would tell stories behind the deals and rattle off detailed numbers from memory, staring into the eyes of his would-be investors for what some said were uncomfortably long periods.
Officially, Benko wasn’t in charge. Around the time of his conviction, he structured the companies so he was neither Signa’s chief executive nor on its executive board, instead serving as chairman of an advisory board. But inside Signa, Benko ran the show, making critical decisions and appeared indistinguishable from a normal CEO, former employees said. Funds eventually rolled in from Switzerland’s Falcon Bank and Ernst Tanner , the chairman of chocolate maker Lindt & Sprüngli and from local Austrian lenders. Signa snapped up buildings in Vienna’s historic “Golden Quarter” and department stores like Munich’s Oberpollinger. Benko boasted Signa was second only to the Catholic Church in owning Vienna property. One key to Signa’s growing empire was a financial maneuver in which Benko’s companies functioned as both landlord and tenant for department stores. This allowed Signa to reap outsize benefits by moving money from its department store business to its landlord business through hiked rents, former Signa employees involved said. That extra rental income was worth far more in the landlord arm through what a former employee called “multiple arbitrage.”
Long-term leases instantly increase the value of properties substantially—and investors tend to value income at landlords at more than 20 times the annual proceeds. At retailers, where business is seen as more fickle, investors value it at less than half that level. This allowed the real estate unit to borrow and raise investment based on the higher valuations. In 2012, Signa joined with mining magnate Beny Steinmetz to buy a portfolio of Karstadt department stores, a chain that dots Germany. The following year, Signa raised rents on a chunk of them and extended the leases to 30 years in return for upfront cash payments. Signa’s Karstadt unit reported the total amount it owed for leases jumped to €3.9 billion, up from €3.3 billion the prior year, according to corporate filings.
A person close to Steinmetz said the joint venture with Signa lasted only three years and that his team wasn’t involved in day-to-day management. He added the Steinmetz organization hasn’t had any contact with Benko or Signa since 2015. Benko and others at Signa justified the rent hikes by saying the department stores had been paying below-market rates, and that Signa would modernize and turn around the money-losing businesses so they could eventually afford the higher payments, former employees said. High-profile acquisitions like Karstadt and the growing roster of wealthy backers helped Benko attract high-profile allies. Former Morgan Stanley Chairman Walid Chammah advised him on fundraising; Gusenbauer, the former Austrian chancellor, and a deputy chancellor both joined his board, and the Peugeot family invested .
The value of properties reported by his two main real-estate companies rose to €3.6 billion in 2014, surpassed €10 billion in 2017 and more than €18 billion by 2020—extraordinary growth in a slow-moving sector. Luxuries piled up, including a ski chalet, fine art, two private jets and the Roma, a 203-foot yacht, which Benko parked in front of Europe’s annual real estate conference in Cannes, France, former employees said. Signa purchased a stake in two Austrian newspapers in 2018, and further expansions in retail gave it a giant department store empire across Austria, Germany, Italy and Switzerland.
Benko pushed into the U.S. in 2019 with a splashy purchase: Signa and a partner paid about $150 million for the Chrysler Building, giving each a 50% stake. Photos of the art deco skyscraper went up around Signa’s offices. As they grew, Signa’s real-estate companies boasted high profits—on paper, at least. Signa called itself “the best performing real-estate company in Europe” in a 2018 investor presentation Between 2017 and 2021, the main real-estate unit, Signa Prime, had a combined €3.4 billion in profits, it said in Austrian corporate filings.
But all of Signa’s profits over that period were from paper gains. Signa marked up the values of its own properties by €4 billion, meaning the company would have otherwise reported substantial losses. In the same period, Signa Prime spent more on interest payments and dividends—€1.9 billion—than the €1.6 billion it received in rental revenue, an unusual situation for a large property owner. Pushing up values was a key focus within the company, former executives said. Employees focused heavily on appraisals, giving rent projections and other evidence to outside appraisers in a bid to get high values, according to those employees. Many investors and lenders relied on the outside appraisals. Dividends were based largely on property values, so higher values boosted returns. Appraisers valued the company’s office properties at 41 times the income they produced in 2021, corporate filings show. Comparable publicly traded office companies’ property portfolios were valued around 20 to 25 times income, according to Green Street, a real-estate advisory firm.
Signa’s figure “doesn’t make sense for any portfolio,” said Peter Papadakos , head of European Research at Green Street. “That’s something I’ve never seen for listed office companies.” He said Signa’s numbers for its hotel and retail properties—valued at 30 times annual income in 2021—were similarly off the mark. Rising paper values allowed Benko to boast of low debt ratios, hovering around 50% of building values, he told investors, according to presentations. That left a healthy buffer in case the market turned.
Some properties, however, had a layer of debt on corporate shells that sat between the properties and the real-estate company, which itself had numerous layers of debt. Benko’s 50% calculation typically omitted billions of dollars in liabilities that increasingly weighed on its finances. Called Genussscheine, a hybrid between debt and equity, it promised investors a share of any profits in a year from Signa companies or individual projects. Even though under German accounting principles it isn’t technically categorised as debt, interest was steep—in the high single digits—on some of these notes and they had to be repaid or refinanced upon maturity. As Signa grew and Covid hit, rents proved unsustainable at the department stores. In 2020, Signa’s German department store unit filed for bankruptcy. To make sure the company would continue to pay the high rents that underpinned Signa’s property values, Signa gave the unit a 200-million-euro lifeline in the form of a loan that was later forgiven. Meanwhile, Signa needed money to fund dividends and an array of large developments started in city centers around Europe.
In December 2021, a unit of the Benko empire that sold bike and tennis gear went public by merging with a special-purpose acquisition company established by Ron Burkle’s Yucaipa. Citigroup gave loans and big U.S. mutual funds bought bonds. A Benko family trust owned nearly half of the stock, which was worth $3.2 billion at its peak. Signa joined with Central Group—run by Thailand’s Chirathivat family—to pay $5 billion for Selfridges, the tony British department store chain known for ostentatious displays on London’s Oxford Street. The Saudi Public Investment Fund helped fund the deal. The empire wobbled in late 2022, when a triple whammy hit. Prosecutors in Austria raided Signa Holding’s offices as part of a sprawling probe into alleged government corruption.
Galeria, Signa’s flagship German department store, filed for insolvency in October 2022, after limping for years. And the sports arm called on Benko for hundreds of millions of dollars in emergency money because of plunging sales. Benko started showing signs of stress. During the day, he would hype himself up by drinking over half a dozen espressos and chain smoke one Cuban cigar after another, filling his jet’s cabin with smoke, former employees said. He had a bad temper, the former employees said. In one meeting, he called his chief financial officer a “fette Sau,” or a “fat pig,” according to a person who was present. In spring 2023, Signa Development, one of Benko’s many arms, sold some buildings to raise cash. But the proceeds didn’t stay with the company, according to people familiar with the matter and statements from ratings agencies.
Instead of being reinvested into the company and ongoing developments as required under the terms of bonds it issued, the cash flowed to other Signa companies, the people said. Fitch Ratings called it a “breach of financial separation” that wasn’t supposed to happen. In August, Signa sold a resort overlooking Lake Garda to a Benko family trust. Signa wasn’t able to find a loan crucial to paying for the rest of the Hamburg skyscraper that was under construction and stopped paying its contractor. In October, Signa Holding backed out of paying Signa’s U.S. sports retailer another €150 million it had promised. The publicly traded retailer declared bankruptcy days later.
A €200 million bond went unpaid by Signa Prime the next month. The defaults sparked a cascade of insolvencies, first by Benko’s holding company, and then by Signa’s two main real-estate companies. Two days before the holding company filed for bankruptcy, it sold a ski chalet to an entity controlled by the “Laura Foundation,” a Benko family trust that shares the name of one of Benko’s daughters, according to corporate filings. More insolvencies within the Signa web are expected, and investors and lenders are bracing for the final bill. Bonds tied to Signa Development are trading at just 13 cents on the dollar, implying the debt investors think they may lose virtually everything. Numerous Signa development sites have stalled, leaving boarded-up sites in Munich, Berlin and Düsseldorf. The site of the 800-foot Hamburg tower sits idle, with Signa’s name on the fence covered with graffiti as politicians debate its future.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


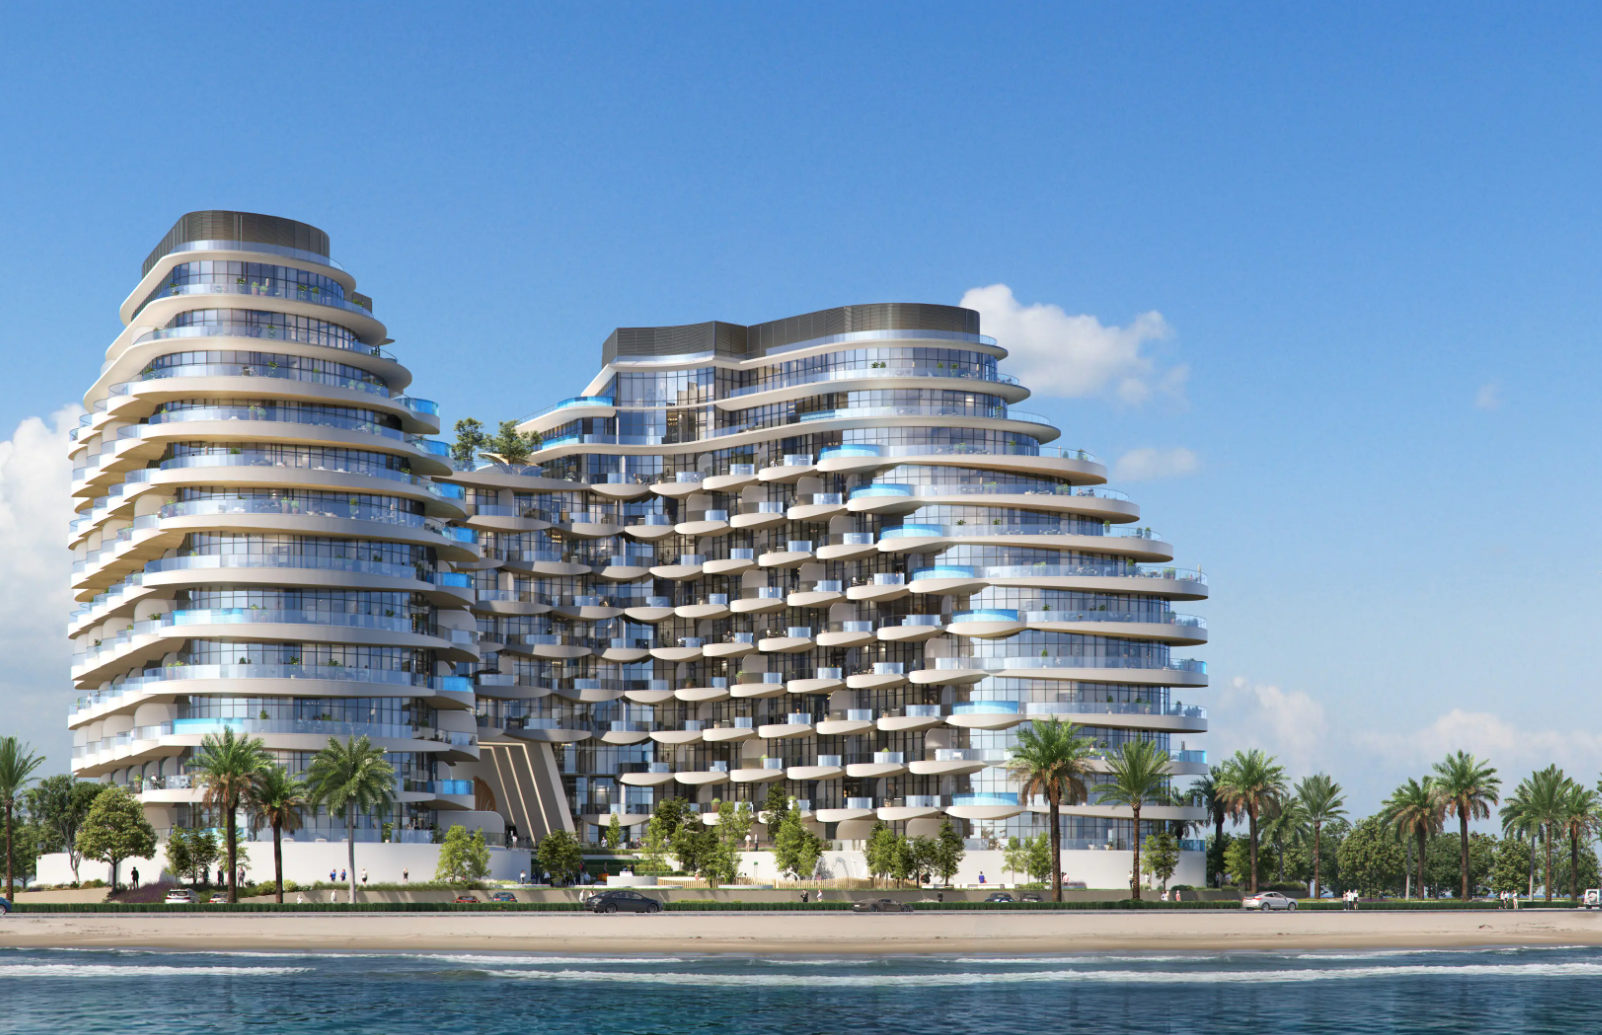
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”
A vibrant 1954 Palm Springs home featuring eight colorful murals by late artist Shawn Savage is on the market for $2.295 million. The 2,237-square-foot property features bold hot-pink doors, three bedrooms, a pool, mountain views and playful interiors blending modern glamour with classic Palm Springs style.
3 min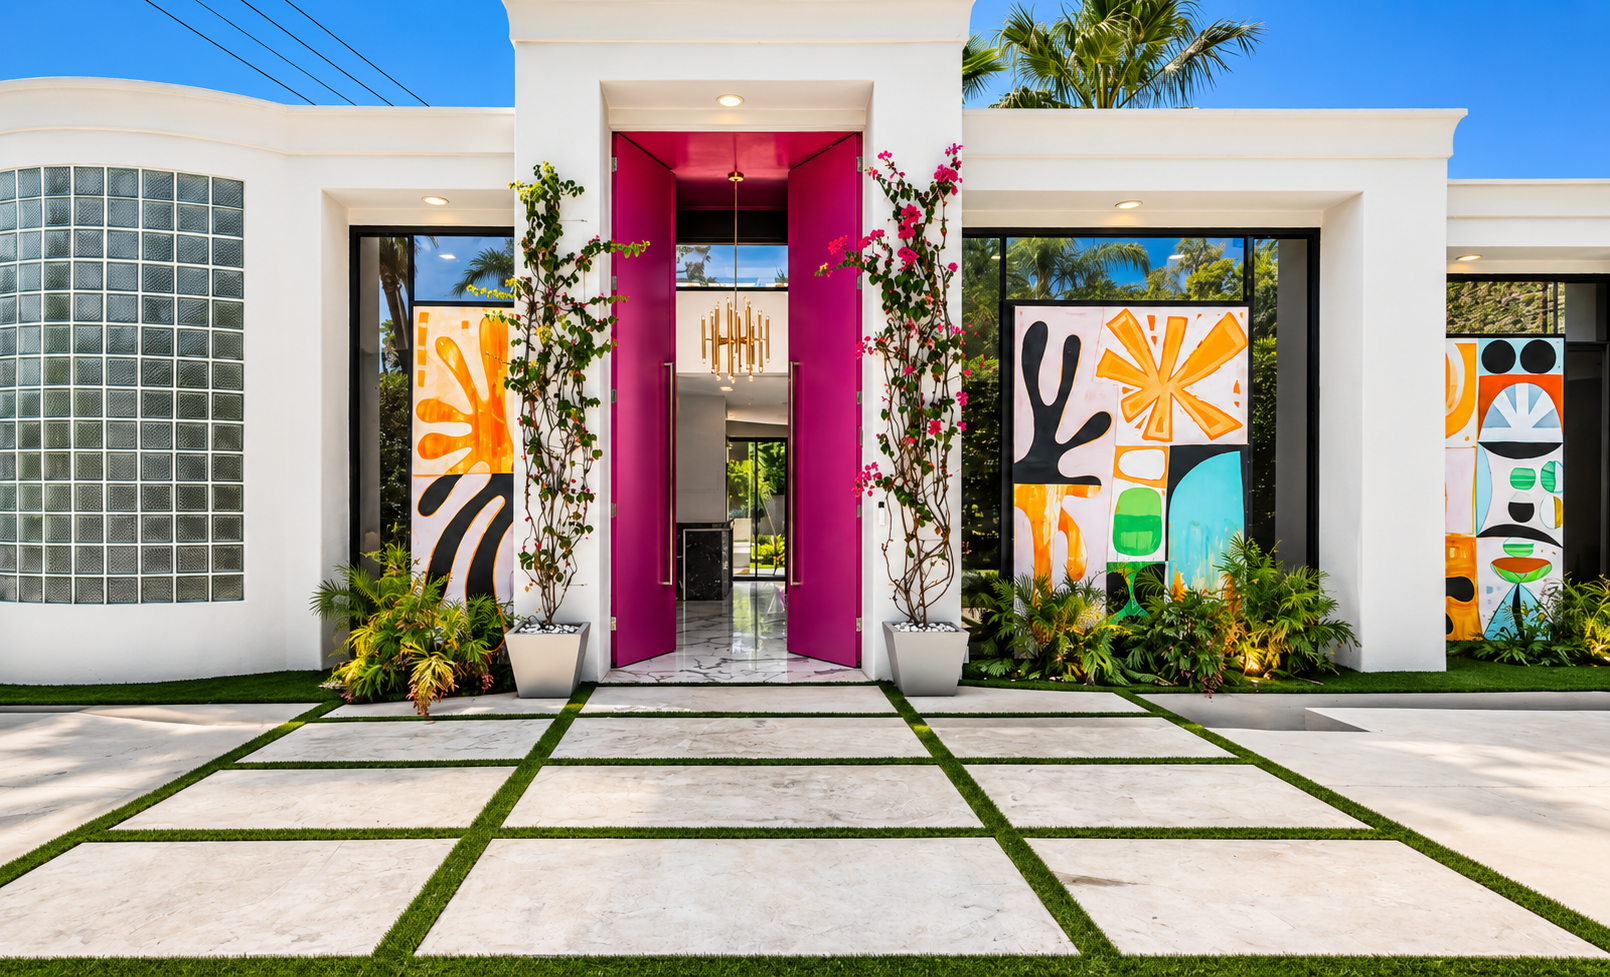
A bold 1950s home in Palm Springs, California, adorned with eight colorful murals by the late artist Shawn Savage, is coming to market ahead of the city’s annual Modernism Week.
The white stucco home on El Camino Way, built in 1954 and recently renovated, has an asking price of $2.295 million. Its staggered facade features three playfully abstract murals on either side of double-height hot pink doors.
MORE: Megamansion Outside Princeton, N.J., With a Pub and Two-Story Library Heads to Auction
The sellers are Los Angeles-based partners John Freeman and Mathieu Faure, who knew it was “the one” when they saw it after several months of searching in the winter of 2023. “It’s a happy house,” Freeman said. “We really liked the feel of the house: the uniqueness, the openness, the brightness—and the art.”
Located in the Mesa neighborhood of Palm Springs, which backs up to the San Jacinto Mountains, the 2,237-square-foot house features three bedrooms, an angled bonus room and a yard with a pool, desert mountain views and another colorful mural running alongside the pool.
“I never thought in my life I would have a house with pink doors,” said Faure, a producer at Apple TV who is originally from Paris. “It’s so colorful, it’s so different. And so Palm Springs.”
The layout of the home creates a smooth flow from the front doors through the open-plan common area—a foyer, bar, and living and dining room—into the kitchen around a fireplace wall and out to the yard. A corridor leads to a private bedroom wing, where the primary suite has floor-to-ceiling windows and the primary bath is only a tad smaller than the bedroom.
Faure has filled the home with Jonathan Adler furniture, rugs and accessories, riffing on the energetic California vibes of the house to create an aesthetic of “modern American glamour,” he said.
“It was enjoyable for me to play with different types of furniture and make this house ‘happy chic,’ as I describe it,” he said.
MORE: Beverly Hills Villa of Late Philanthropist Glorya Kaufman Sells for $19.25 Million
“He did a fantastic job,” said Freeman, who is an attorney and consultant. “It does kind of bring a smile to my face whenever I walk into the house.”
Since the furniture and decor were chosen for the particularities of the space, the couple is open to selling them with the home. Their West Hollywood house is already furnished; the collection doesn’t match the vibes of a Houston loft they bought near family; and Faure can’t imagine these pieces in New York—where he’s lived in the past—he said.
The duo bought the Palm Springs house for $1.925 million in 2024, according to property records, and will list the home Monday. They are represented by Stewart Smith, Patrick Jordan and Kevin Stanley of Bennion Deville Homes/Luxury Portfolio International.
The previous owners had purchased the home in 2021 for $975,000 and then spent more than two years and $700,000 on the renovation, according to Realtor.com. They commissioned Savage, a local Palm Springs artist and painter known for his joyful abstract work, to decorate the home.
MORE: Alpine Villa From Lady Gaga Movie ‘House of Gucci’ Lists for €2.9 Million
Savage, who died in 2024, lived in the Coachella Valley from 2003, and his work can be found in various local institutions and is on exhibit at the Illumine Gallery in Palm Springs. “Some artists pass through a place. Shawn Savage became a part of it,” the gallery’s description states.
Unsurprisingly, the murals invite lots of friendly conversations, as well as guided tours and interested lookers, but never to a degree that it disturbed the peacefulness of their home or the neighborhood, the sellers said. “It felt like living in an art gallery, and you have the exterior that you would share with the world,” Faure explained.
The neighborhood also played a role in their decision to buy, because of its access to the hiking trails of the San Jacinto Mountains, the lack of through-roads and the neighborly environment.
“It’s a very friendly place,” Faure said.
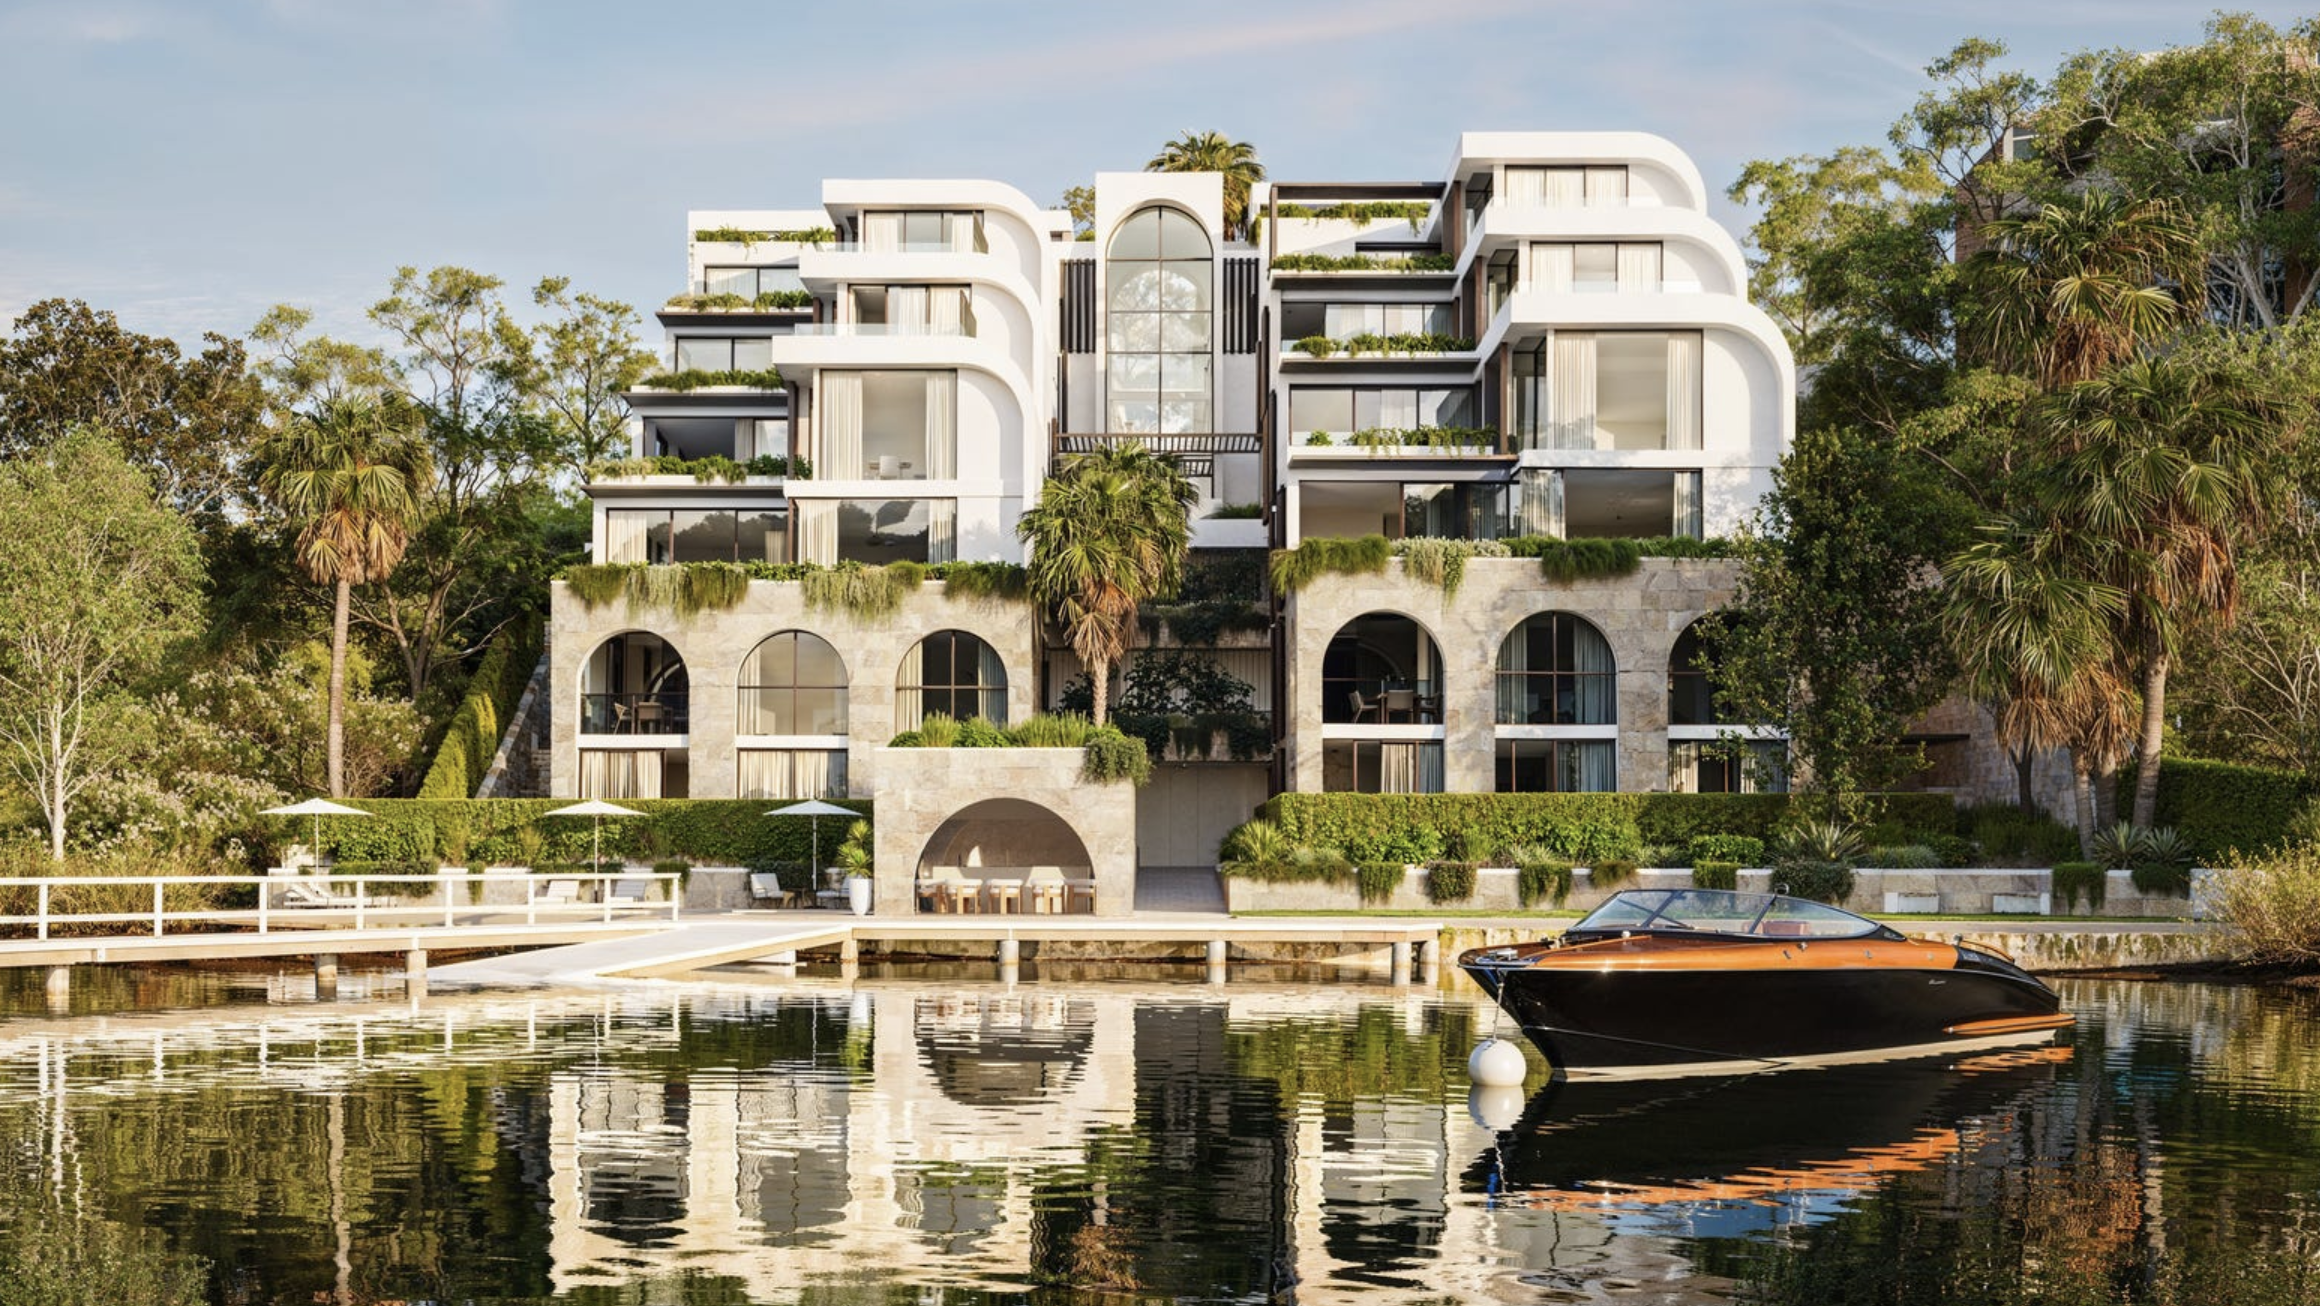
Advertising legend John Singleton unveils an exclusive 16-residence Caroline Bay development, marking his latest high-end property play on the Central Coast.
High-end homeowners are choosing to upgrade rather than relocate, investing in bespoke design, premium finishes and long-term lifestyle value.