The sustainability trend coming to an office near you
It lends a whole new meaning to the concept of hot desking
 3 min
Everyone is talking about environmental sustainability these days. From growing our own food to opting for less plastic packaging, there is an increasing desire to embrace practices that have as little impact on the environment as possible.
One of the last sectors to seriously consider the way their behaviours are contributing to waste is the office.
Prior to COVID, most offices were refurbished every five to seven years, in line with leasing arrangements. However, quality office furniture can come with warranties of 10 or more years. What to do with used – but still useful – furniture at the end of a lease has been a challenge.
The result is 35,000 tons of furniture from Australian offices ends up in landfill every year.
Designer furniture retailer Living Edge is calling on businesses to end the waste with a shift from one of purchase to leasing. This would result in the furniture supplier taking responsibility for the product over a lifetime.
Sustainability strategist at Living Edge, Guy Walsh, said while it has been a slow burn convincing businesses, interest has gained pace in a post-COVID, hybrid-working environment.
“We have been talking to the market about the life cycle model since 2016,” Mr Walsh said. “But in the last 12 months, we have seen an increase in interest, how it works and the sustainability benefits.”
He puts this down in part to the number of businesses committing to sustainability targets, sometimes without a plan for how to achieve them.
“The big organisations are all making their sustainability pledges and they are working out how to deliver them later,” he said. “You can’t just make claims anymore – you have to provide evidence. We can pull a report out and demonstrate the outcomes, which can be useful for external and internal communications.”
With many workers reluctant to return to the office full time, Mr Walsh said the need for a floor full of office furniture has also changed. A leasing model offers flexibility.
“One of the things COVID created was uncertainty, which requires more agility (from businesses),” he said. “We have promoted that concept around the life cycle model, which has a lot more agility than a traditional model.
“If the world changes, as it has in recent years, you need a strategy for what to do with those assets. One top of that, through a sustainability lens, change can often result in waste.”
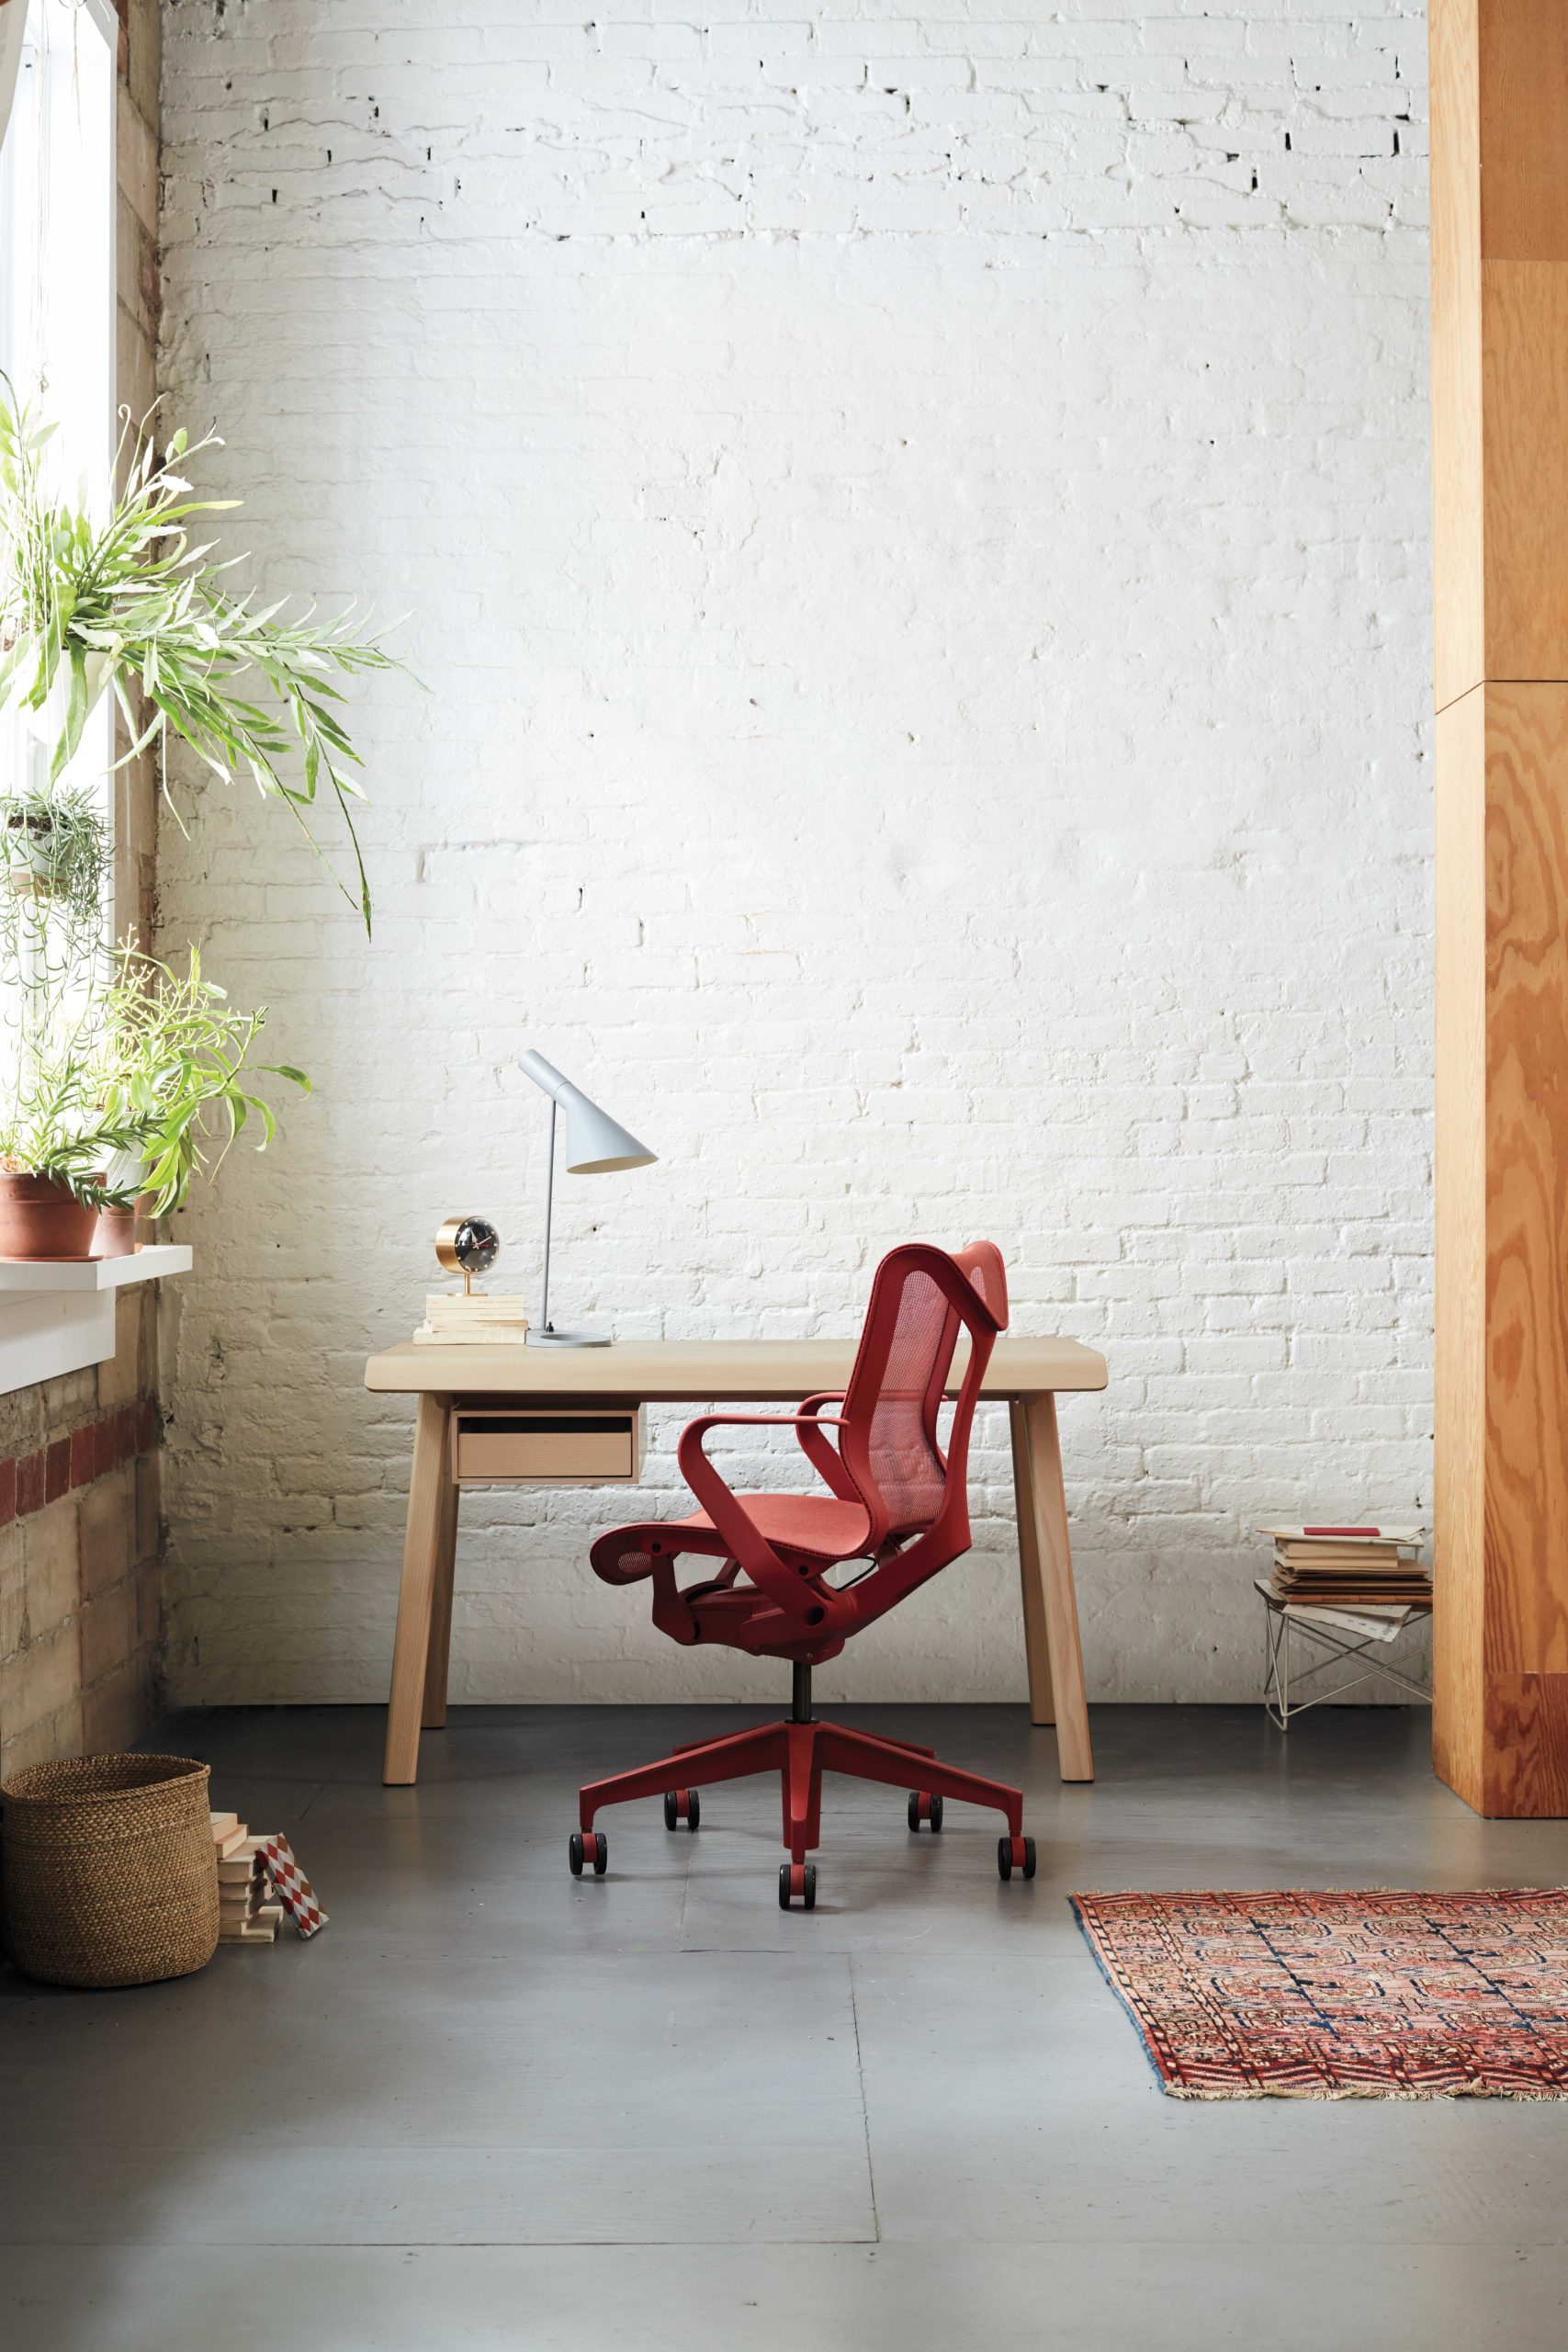
Living Edge is the main distributor for Herman Miller, which has built its reputation on the high quality, ergonomic task chairs favoured by big business.
Mr Walsh said the chairs, such as the Aeron, come with a 12-year warranty. Under a leasing arrangement, businesses could return their chairs to Living Edge where they will be triaged according to useability under their LivingOn scheme.
“The top outcome is it gets refurbished and reused by the original purchaser,” he said. “The next option is we refurbish it and we resell it as a ‘second life’ chair. The next option is to recycle the parts. The last, and least attractive option is that it goes to landfill.”
It’s good news for commercial landlords, as well as tenants but it does require a different approach from the standard office fit out. One concern is how to ensure furniture is identifiable by the supplier as theirs. The other is a structural change in how budgets are created and managed.
“One of the big barriers traditionally is that furniture falls under capital expenditure but a lease model would put it under operational expenditure,” he said. “You are moving the cost from a one-off figure to ongoing. It is purely the legacy of how furniture has been bought for office spaces.”
While the model is still in its infancy both here and in Europe, Mr Walsh said there are already signs that it is the way of the future.
“We have heard examples of it happening in Europe but to my knowledge, we haven’t seen that ‘lift off’ moment,” he said.

From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min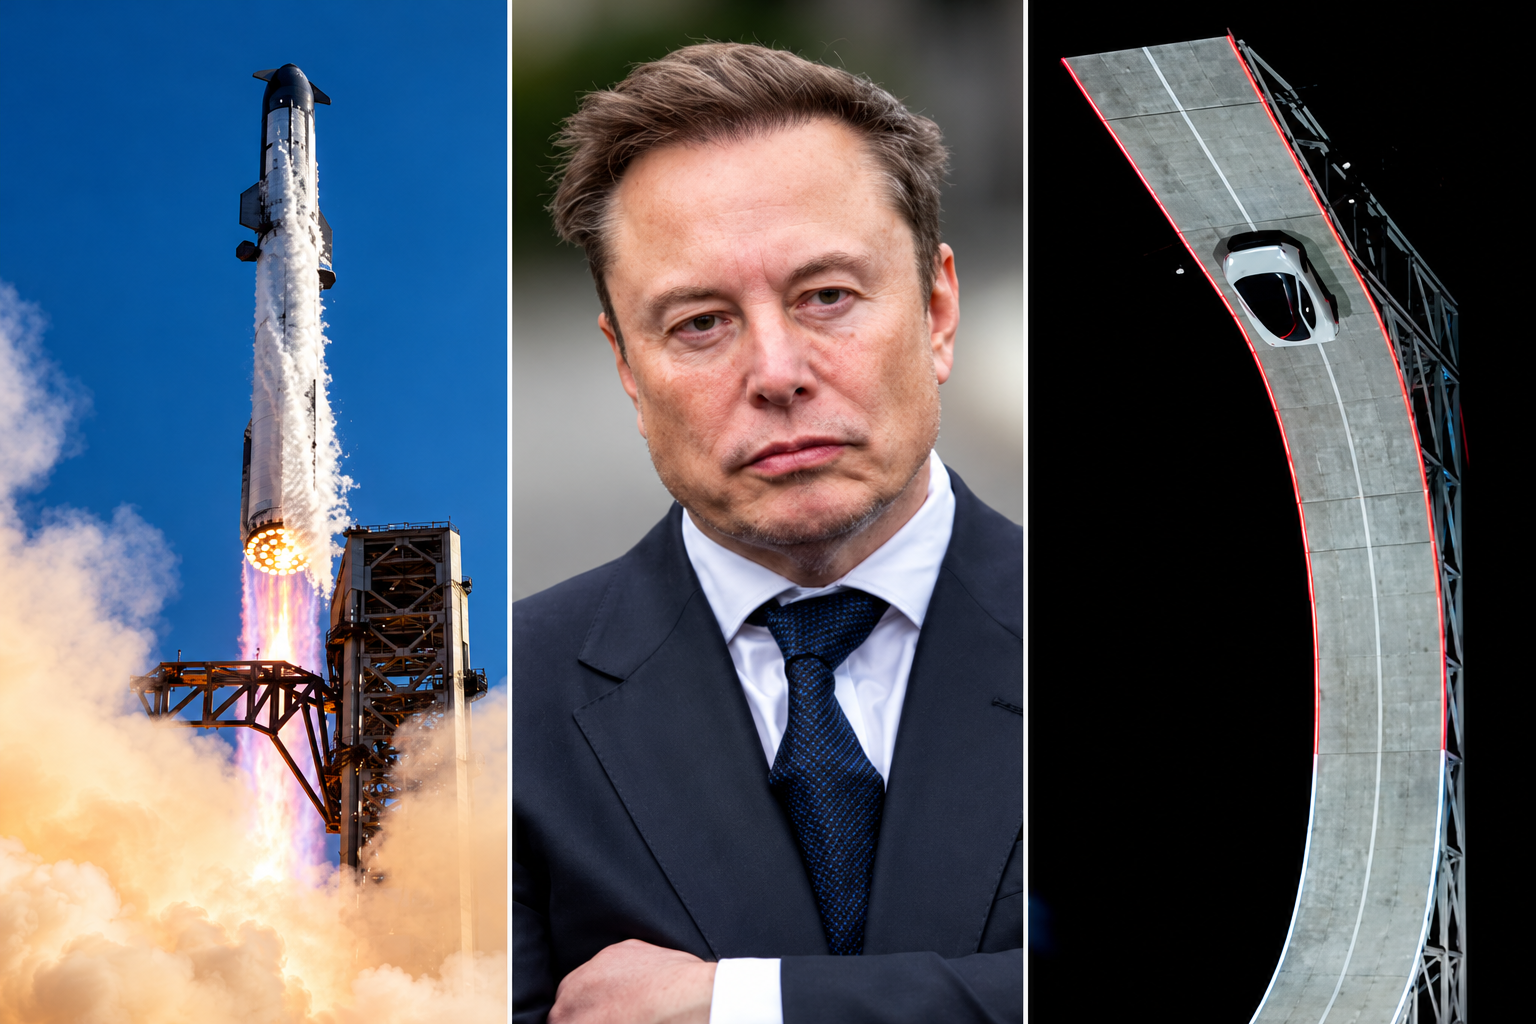
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.
Australia’s housing market defies forecasts as prices surge past pandemic-era benchmarks.