





In a Florida Town Ravaged by Storms, Homeowners All Want to Sell
Ballooning home insurance costs and the perennial threat of violent storms hit Tampa Bay housing market hard

 4 min
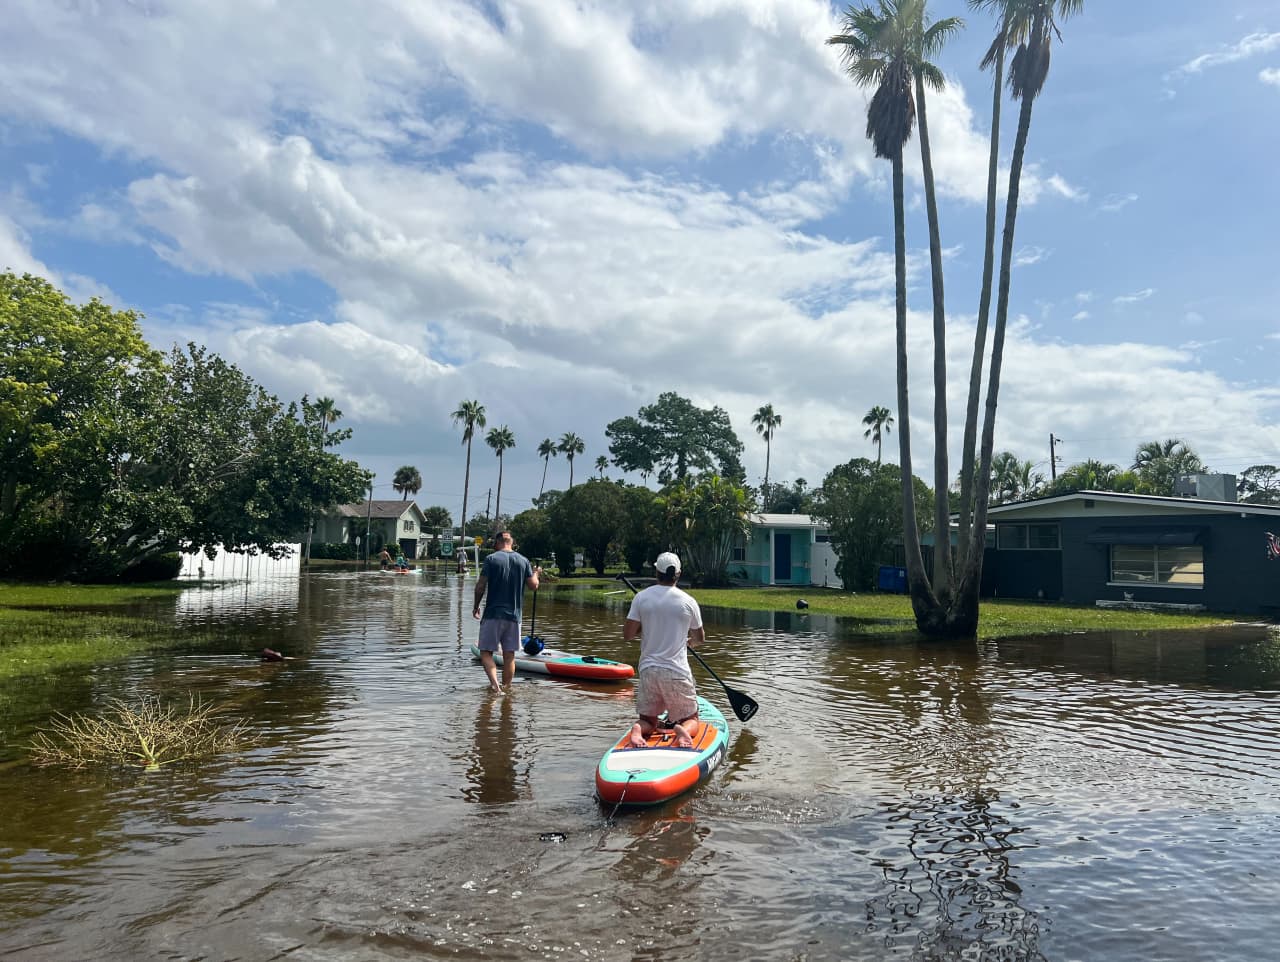
ST. PETERSBURG, Fla.—Kellen Driscoll bought his home here in 2019, settling in the coastal enclave of Shore Acres. It flooded for the first time four years ago after tropical storm Eta dumped more than 3 feet of water.
Hoping it was a fluke, Driscoll tore out the affected drywall and started fresh. After all, the four-bedroom home built in 1960 had no flood history.
But then it happened again, and again. Like many others in the community, he put his home up for sale in the spring of this year. After seeing little interest, he cut the asking price.
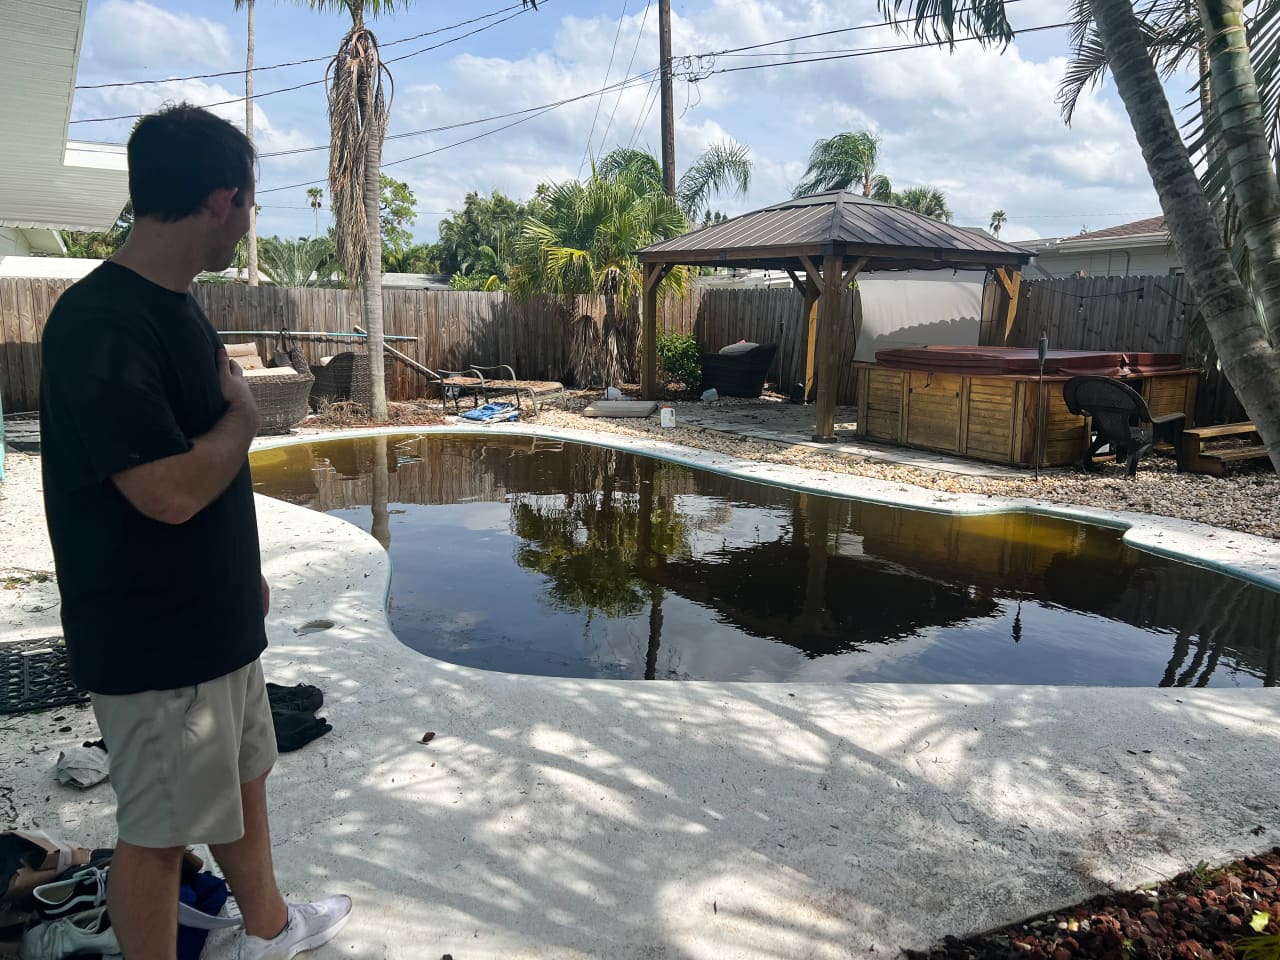
On Friday, Hurricane Helene deposited more than 6 feet of storm surge in the neighbourhood. The rushing waters ripped the “For Sale” sign off his front lawn, and etched a waterline that reached halfway up his front door, just underneath the doorbell. He reduced the asking price for a fifth time.
“We flooded here four times in the last four years,” said Driscoll, as he threw his television sets, furniture, appliances and other belongings to the curb. “I’m just hoping I can sell the house. It’s a good neighbourhood for sure, but dealing with the floods is horrible.”
In the Tampa Bay metropolitan area, which includes St. Petersburg, a real-estate boom nearly doubled median home values from 2018 to June of this year, according to Redfin data. Young people flocked to the region, looking for a coastal lifestyle at a relatively affordable price.
The Tampa Bay metro area was the fifth most popular relocation destination in the country, according to an analysis by Redfin last year. The population has soared to more than three million.
But as Shore Acres’s young residents sorted through the storm’s wreckage, only one thing was on their minds: selling.
Ballooning home insurance costs and the perennial threat of violent storms are starting to undermine housing markets throughout much of the state. But in few places has the turnaround been more dramatic than in low-lying communities up and down the coast of Florida that frequently flood.
The Tampa Bay housing market had been softening even before Helene struck. While prices have been flat, the area experienced a 58% increase in supply in August compared with a year ago, and a 10% decrease in demand, according to Parcl Labs, a real-estate data and analytics firm.
About half the homes listed for sale in Tampa experienced price reductions as of Sept. 9, the third highest share of all U.S. major metropolitan areas.
“Tampa was already heading in this direction before the hurricane hit,” said Jason Lewris, co-founder of Parcl Labs. “This hurricane may compound the market dynamics that have been occurring there over the last few months.”
While Tampa escaped a direct hit from the eye of the hurricane, it was the worst storm to hit the area in a century. The hurricane also plowed into landlocked towns well north, causing heavy damage in the Carolinas where people were just beginning to absorb the scope of ruin.
‘Let’s roll the dice’
Bradley Tennant’s home flooded last year. But to avoid all the competition, he was waiting a year to put it up for sale.
“We saw the glut of homes for sale in the spring and thought, ‘What are the chances it’ll hit again the next year?’” said Tennant, as he cleared out the soaked contents of his waterfront home. “We went 50 years without a storm that flooded the house. So we thought, let’s roll the dice.”
While he paid around $350,000 for the house about seven years ago, Tennant says he received offers as high as $800,000 during the height of the market—before last year’s storm hit. Now he’s hoping to sell as soon as he’s able to renovate.
The area’s affordability, once a large part of its appeal, is also waning as insurance premiums soar. Jacob McFadden was paying $880 a year to insure his home when he bought it in 2020. That amount has since almost quadrupled, to $3,300.
Premiums will likely increase again now. Property damage from last week’s Category 4 storm could be as high as $26 billion, according to estimates from Moody’s Analytics.
“I don’t know how much longer I’m going to do this waterfront living,” McFadden said, standing in front of his home with a wheelbarrow and his home’s contents scattered around the front yard. “This may be the end.”
Dustin Pentz bought his home 10 years ago, and was one of the lucky few to avoid flooding. That is until Hurricane Helene. When police blocked his car from entering the neighbourhood, he paddleboarded his way home to assess the damage.
His fridge was knocked over, and the water reached up as high as his mattress. Unfortunately, his flood insurance doesn’t cover the contents of his home. A tree in his backyard fell over and hit the corner of his roof, but he was unsure that the damage would hit his $8,500 wind deductible.
“This neighbourhood’s amazing, great schools. But no one wants to deal with this all the time,” said Pentz. “It sucks because no one wants to live here anymore. There are so many houses for sale and no one’s buying.”
Working class squeezed
Down the street, Domonique Tomlinson and her husband, Leon Tomlinson, filed a claim for items they lost in last year’s flood. They didn’t want to go through the headache of filing another claim for the contents of their home this year, with a separate $5,000 deductible.
Two days before Hurricane Helene hit, they rented a moving van to haul many of their belongings to a storage unit. She bought her home four years ago for around $199,000. Because property values have increased so much in her area, she hopes to break even. But now she says she’s not so sure.
Tomlinson, who is a teacher, and her husband, who works as a manager at a grocery store, worry that people like them will be priced out of the area because they can’t afford the preventive measures and insurance.
“Basically the only people that are going to be able to live back here are rich people who can build up,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.

With two waterfronts, bushland surrounds and a $35 million price tag, this Belongil Beach retreat could become Byron’s most expensive home ever.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.


