Why autumn property listings are on the rise
Vendors are no longer waiting for spring to list their property, but there’s still an art to get the timing right
 5 min

Industries like luxury fashion and elite sport are dictated by the seasons, so why not the residential real estate market? Selling homes is considered a science by some in the business who suggest that when you list can have a direct effect on the final price.
Analysis by property portal realestate.com.au’s data group PropTrack reveals there is generally a more profitable time of year to list a home for sale, but ultimately results can vary by region.
The 2021 research isolated the impact of the sale month from other features impacting price and discovered properties which sold in November received the highest average prices. Across Australia, sales in November were almost 6 percent higher than those in January, traditionally the sleepiest month on the real estate calendar. These results also ranked October and December as additionally profitable months.
Spring saturation
The reasoning behind strong spring selling statistics comes down to a mix of human behaviour and mother nature.
Tim Lawless, head of research at property data specialist CoreLogic, says while there is logic to the popularity of spring among sellers it could also just be an established pattern of behaviour Australians have found hard to kick.
“It definitely comes back to sentiment as well as the ability to present a property well. Spring is a time when the weather warms up, people become more active, the grass is greener and flowers start to bloom. So from a property presenting perspective, it’s a logical time to prepare your property for inspections so people can see it in its best possible light,” he says.
For more stories like this, order the latest issue of Kanebridge Quarterly magazine here.
It’s a great theory for houses with gardens, but he admits there is no real reason why apartment listings also ramp up in spring.
“I think it’s probably so deeply ingrained culturally that people don’t necessarily think about some of the logical aspects, because selling a unit wouldn’t be much different from season to season,” he says.
While this boom in the property calendar is often referred to as “spring selling season” Lawless says it could probably be more accurately be described as the “spring listing season”.
“We actually see the number of sales is equally as strong around March as it is in November, which are sort of both seasonal peaks in sales activity” he says. “But for listings, it’s really clear that after winter there’s normally a solid ramp up in the number of newly-listed properties coming onto the market.”
Understanding the real estate calendar
While spring is an active time of year in property, the rest of the calendar is marked by milestones which can make or break the success of a sale. School breaks, long weekends and even major sporting events should be taken into account when a home’s marketing campaign is being created.
“School holidays are relevant, but probably what’s more important would be long weekends, like Easter, or grand final weekends. The most obvious one is the Christmas period when pretty much everything shuts down,” Lawless says. “If you think about the property process, a lot of people need to be around to make a transaction happen.
“You need buyers and sellers obviously, but also you need the agent, the conveyancer, building inspectors and those individuals or professions may not be operating due to holidays.”
The real estate calendar had its first real shake up in a generation during the pandemic as potential buyers couldn’t leave on holiday or even view interstate homes.
Auctions moved online, property professionals worked from home and an unprecedented number of buyers bought site unseen.
As a result, some of those old seasonal selling tropes went out the window.
Bucking the seasonal trend for buyers
Bianca Denham, head of performance at the Ray White Group said bucking the seasonal listing trends could be a valuable move for sellers.
“Even pre pandemic we would train our agents not to fall into the trap of focussing on spring time,” Denham says.
“Because if sellers have been institutionalised — for lack of a better word — that spring is the best time to sell, then what it creates is actually more competition among listings.”
While there are more properties for sale, that doesn’t necessarily translate into more buyers, she says.
“Buyers don’t become buyers just because the daffodils are in bloom, they become buyers because something has happened in their life; they’ve got that promotion, finally saved the deposit, or they have a baby on the way,” she says. “Buyers become buyers for reasons that have absolutely nothing to do with the time of year.”
Alternatively, some agents are testing the water by working against old school traditions.
“We’re seeing more agents embracing the downtime of summer as an opportunity to sell,” Denham says. “If you look back to a pre pandemic so-called ‘normal’ market then you would have seen it go to sleep over Christmas and January.
“We’ve found that any agent who makes the concerted effort to list over Christmas is rewarded because there are inspections and they do get offers.”
She added that vendors who tap into holiday periods could be rewarded with more buyer eyeballs on their listing.
“When people step out of their everyday and go on a break, that’s when they can start dreaming because they’ve got time on their hands. It’s one of our nation’s most-loved pastimes — browsing on real estate portals. We love it even if we’re not actively buying.
“Not everyone goes away, and some people come from the country to the city, or vice versa, and they start looking at local real estate wherever they go.”
Lawless agrees that savvy sellers should consider just how saturated the market can get at certain periods.
“It’s definitely a factor in decision making. It’s good to know how much competition there’s going to be, or lack thereof,” he says. “So maybe going counter cyclical is a good idea by listing in winter when there’s not as many listings to come up against.”
In the end, do what works for you, he says.
“Your best option is to buy or sell when the timing is right for you rather than trying to time it with the seasons or trying to buy property at the bottom and sell at the top.”

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
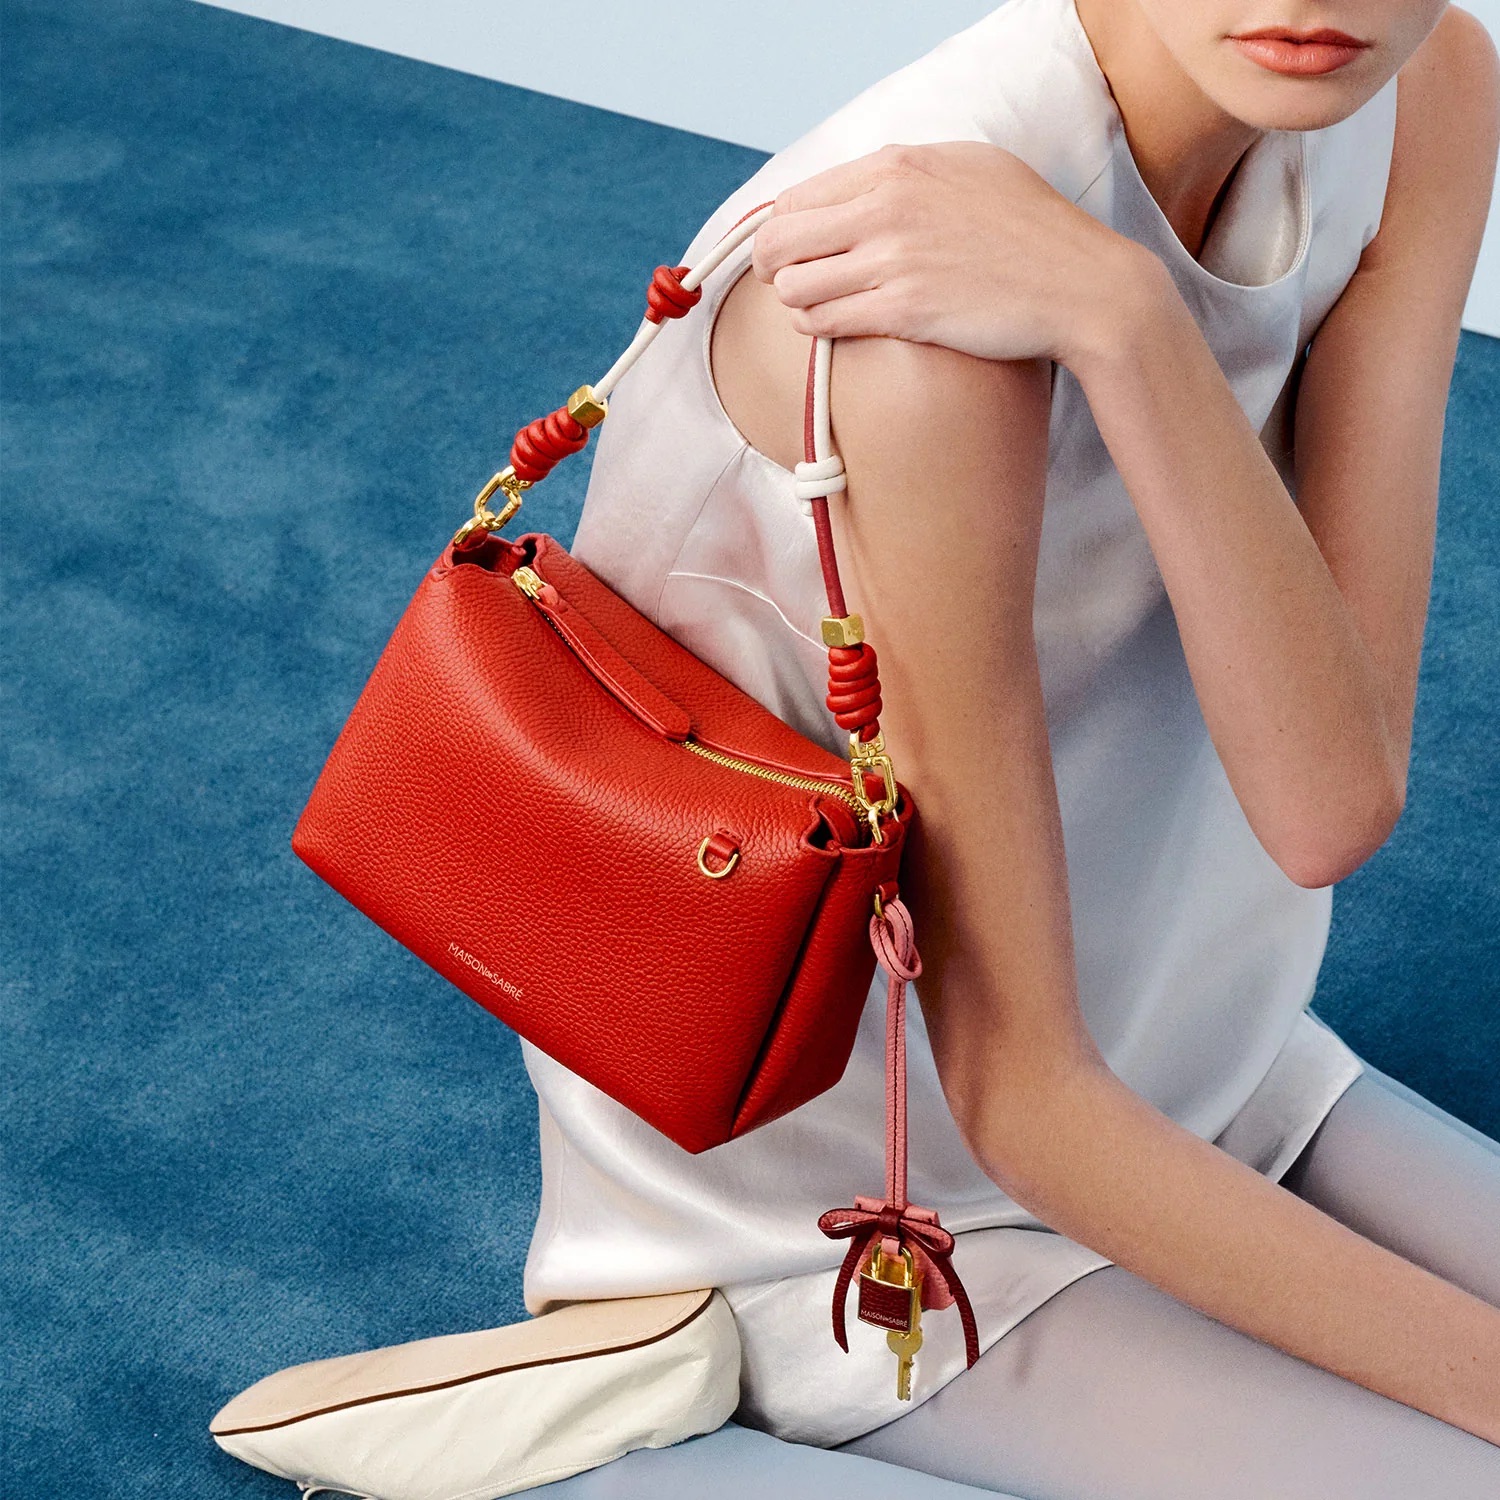
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
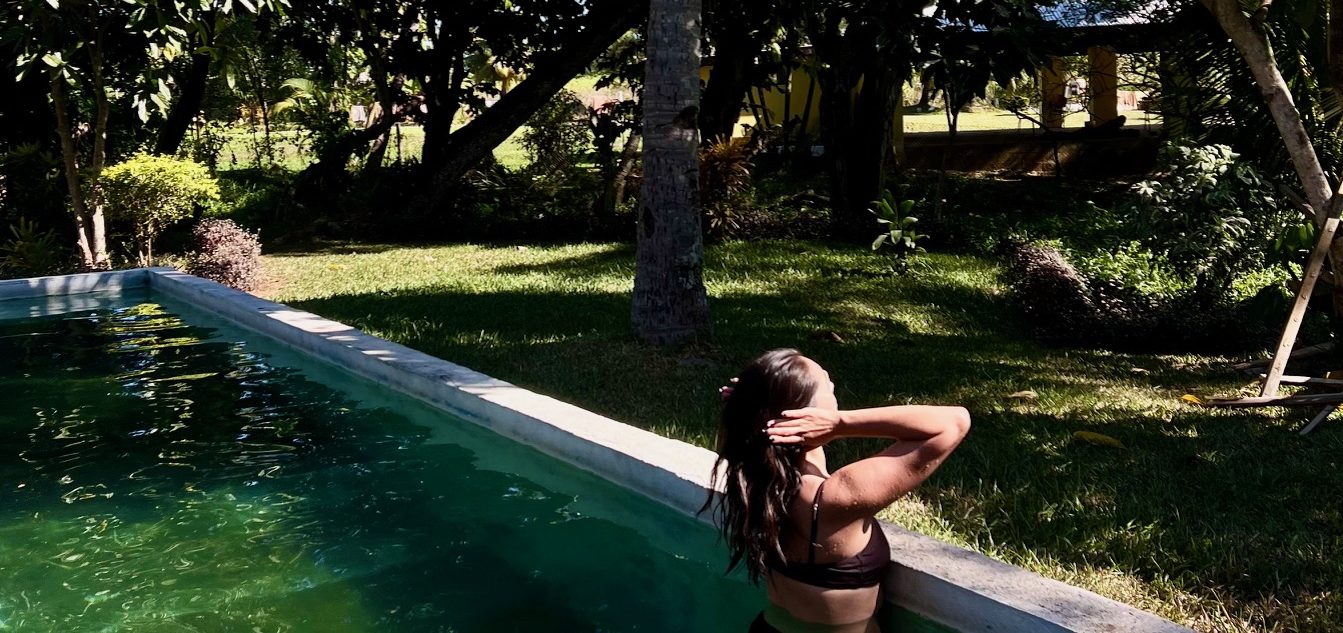
From mud baths to herbal massages, Fiji’s heat rituals turned one winter escape into a soul-deep reset.