How Property Styling Can Elevate Your Sale Price
In today’s luxury market, selling a home isn’t just about bricks and mortar—it’s about selling a lifestyle.
 2 min

In today’s high-end property market, buyers aren’t just purchasing a home; they’re investing in a lifestyle.
First impressions are everything, especially in the luxury space, where details matter and emotion drives decision-making.
This is why property styling and staging have become essential tools for anyone looking to maximise the value and impact of their home during the selling process.
As an interior designer who works with high-end homes, I’ve seen time and again how professionally styled properties don’t just sell faster, they sell for more. Here’s why.
Buyers don’t buy empty spaces, they buy possibility
When buyers walk into a beautifully staged home, they can instantly imagine themselves living there.
Styling helps people connect emotionally to the space, picturing entertaining in the dining room, relaxing in the master suite or hosting friends in the alfresco area.
Without furniture, scale is hard to read, flow is harder to feel and the property can feel cold or overwhelming.
In contrast, a styled home feels warm, inviting and aspirational, like a private escape rather than just a transaction.
Staging highlights the home’s best features
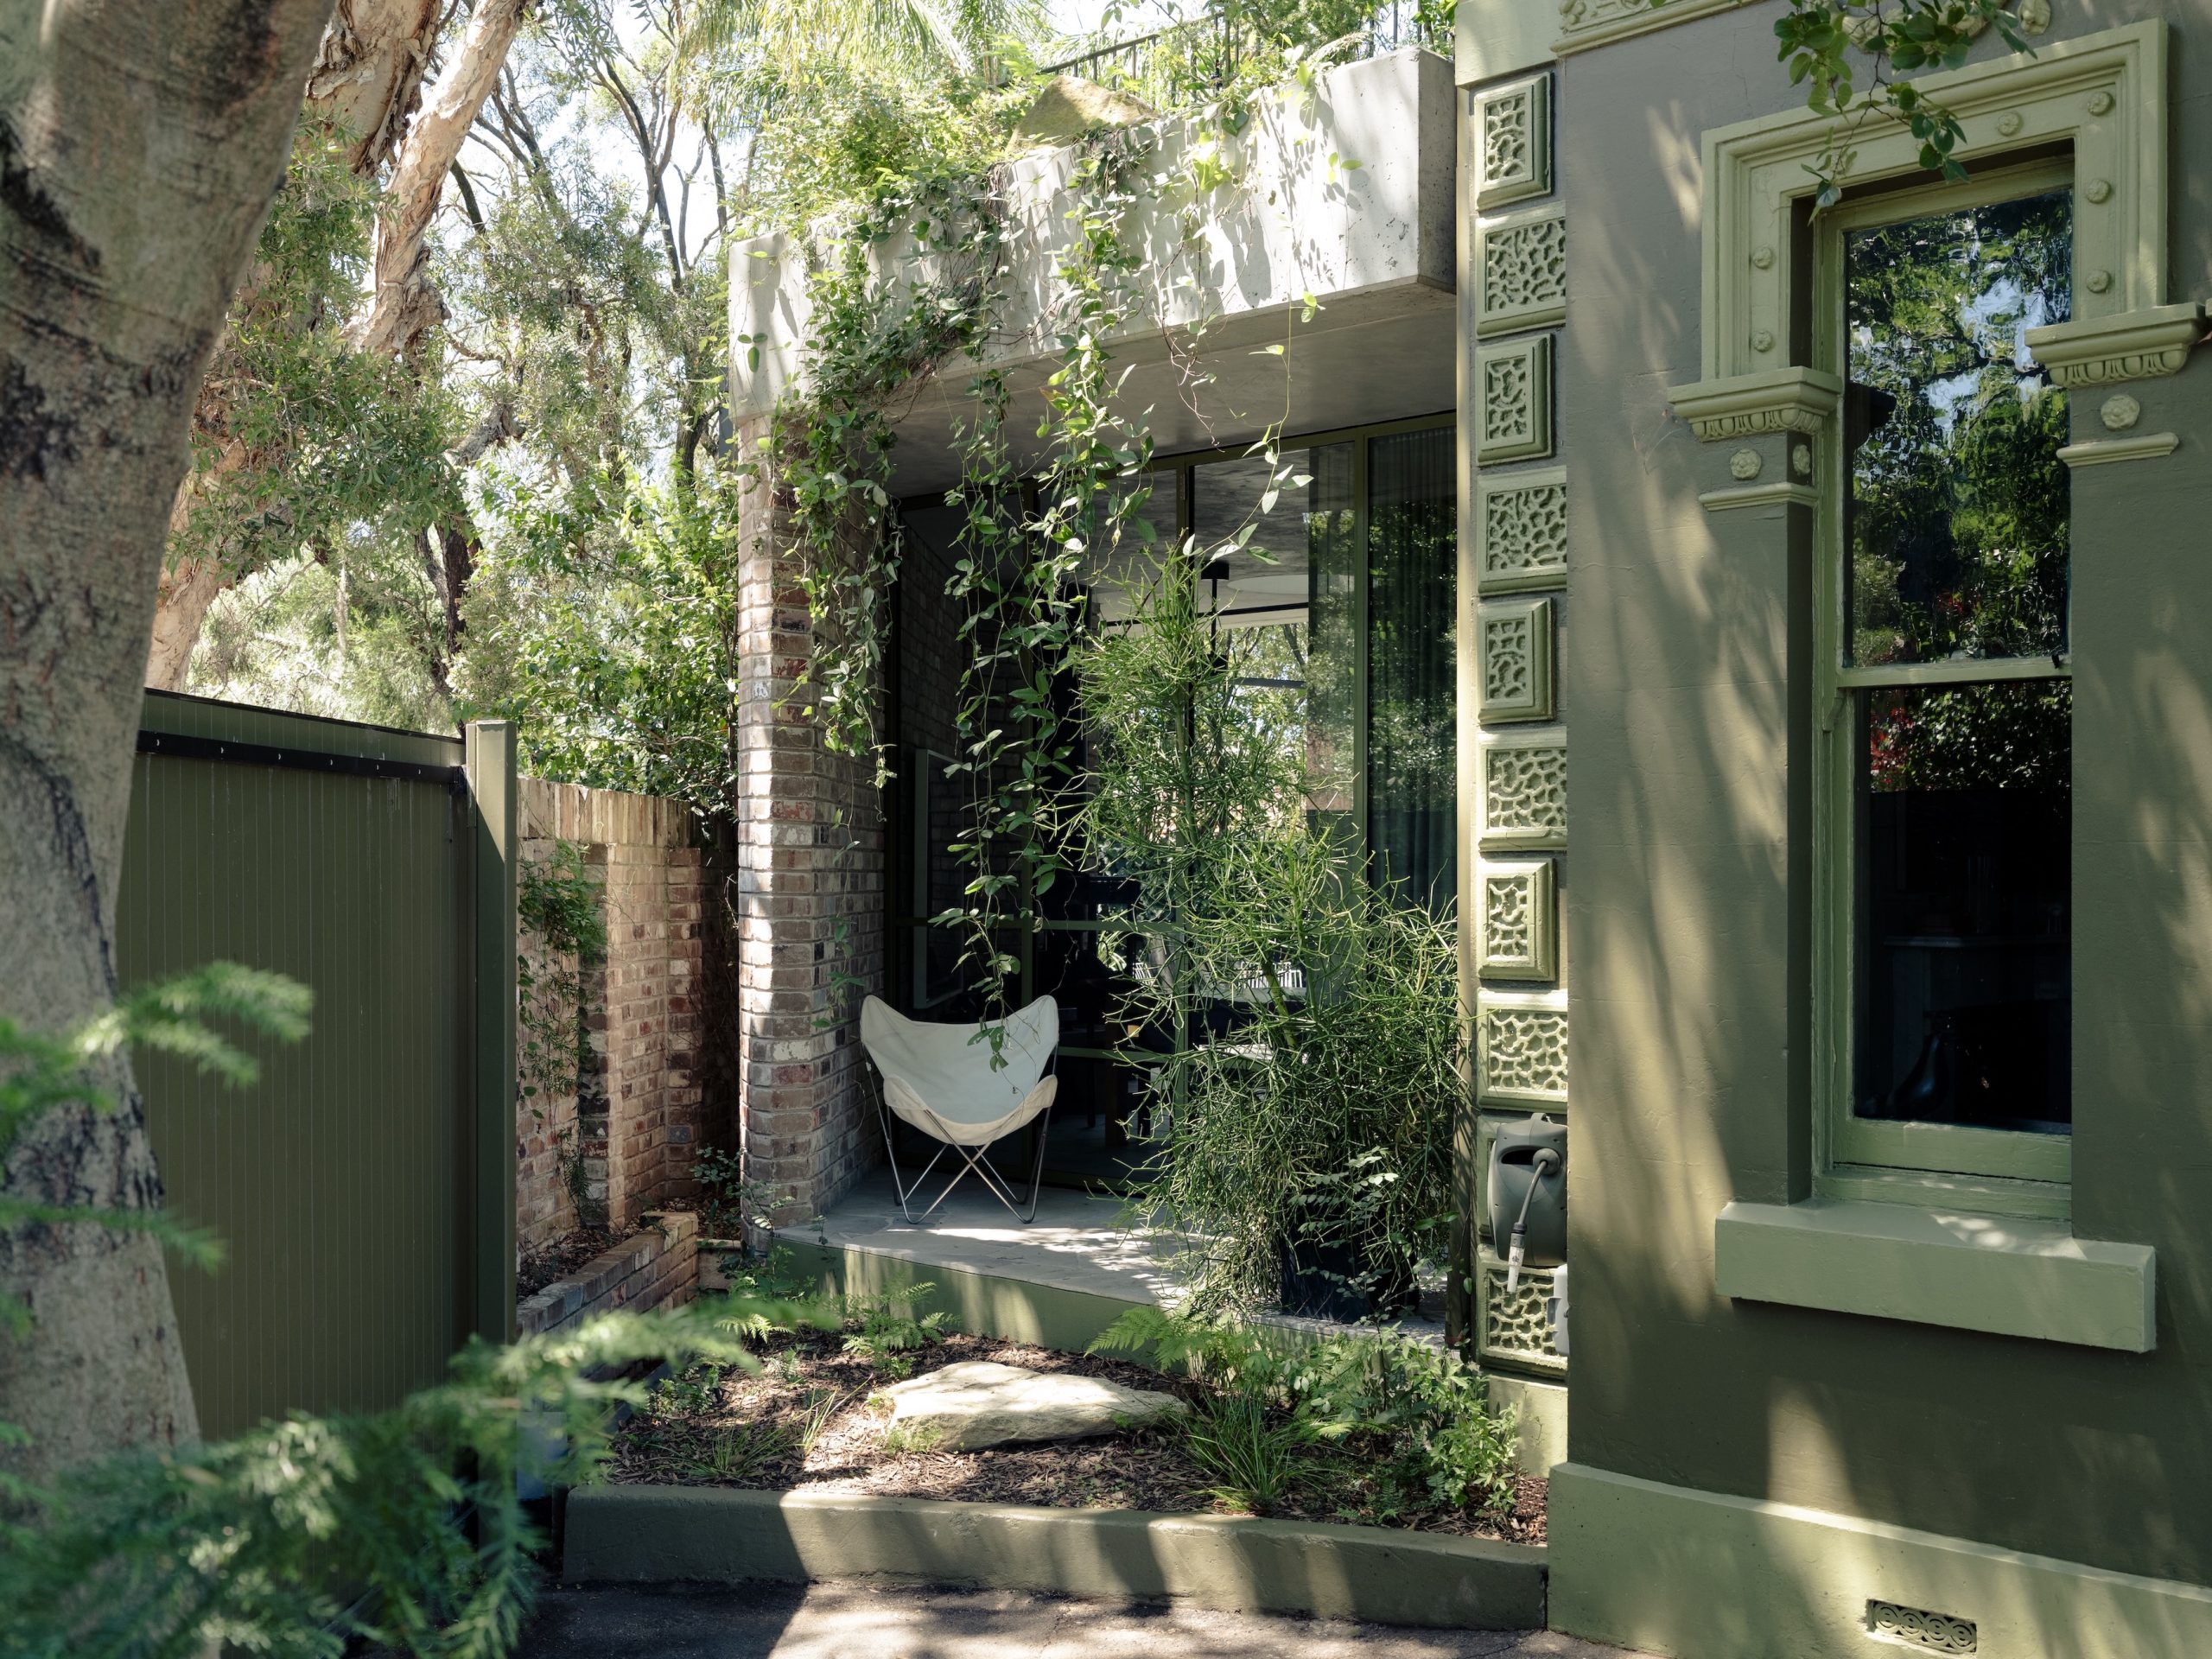
Luxury homes often come with grand proportions, soaring ceilings, unique architectural elements or standout features like wine cellars, fireplaces or butler’s pantries. Styling draws attention to these assets and helps them shine.
By placing furniture, lighting and art in the right proportions and positions, you create a sense of scale and spatial clarity.
A well styled room frames views, improves traffic flow and gives each space purpose, all of which increases buyer confidence and perceived value.
It helps set your home apart from the competition
In a crowded market, luxury homes need to stand out, and the right styling is a powerful point of difference. Professional staging creates a unique visual identity for your home that sets it apart from other listings, both in online campaigns and during inspections.
Buyers are making decisions before they even step foot through the front door. If your home is styled to photograph beautifully, it will capture more attention, more clicks and ultimately, more interest.
Luxury buyers expect a polished presentation
Discerning buyers notice the little things. They expect quality, attention to detail, and a home that feels move-in ready.
Styling adds that layer of polish that elevates the entire experience. From hand-selected furniture to curated accessories and textures, staging creates the kind of sophisticated, turnkey environment that speaks directly to a luxury buyer’s expectations.
Even if the buyer plans to renovate later, the emotional pull of a beautifully styled home still influences their sense of value, and often, what they’re willing to pay.
It can drive up the final sale price.
A styled home can lead to faster sales and stronger offers. Why? Because it removes objections.
Buyers walk through and feel like everything just works. There’s no guesswork, no wondering if a room is too small or where the furniture would go. The home feels complete, and that completeness creates confidence, urgency and often, competition.
When a property is styled to its full potential, it’s not unusual for it to attract multiple offers or exceed price expectations.
Final word
Styling is not about decorating; it’s about positioning your property to achieve its highest value. For luxury homes, where buyers are emotional, discerning and looking for something special, professional styling transforms your space from a house into a home, and from a listing into a dream.
Kellie Richardson is an Interior Designer and Founder of Kurved by Design
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.

In the lead-up to the country’s biggest dog show, a third-generation handler prepares a gaggle of premier canines vying for the top prize.
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”