





Family’s dream home could rewrite Brisbane records
Built as a forever home, Corazón combines wellness, luxury and architectural flair in one of New Farm’s most ambitious residential projects.
 4 min
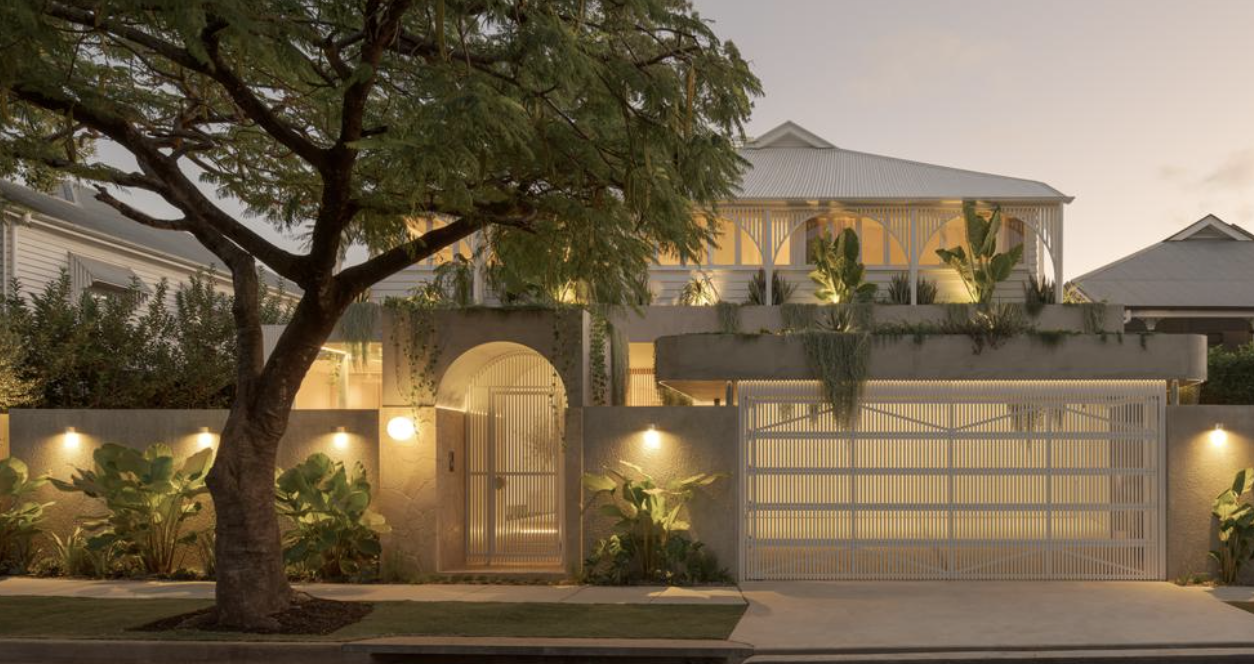
Although Corazón was meticulously built to be the Smout family’s dream home, the glamorous Brisbane residence is now seeking its next custodian.
The luxury New Farm property named Corazón, the Spanish word for heart, was always meant to be the Smouts’ forever home.
Becky, a teacher-turned-design specialist, and her property developer husband Francisco bought a pre-war timber home on the 810sq m site back in 2022 for $2.625 million. They then painstakingly transformed it into a luxury 21st-century residence.
The laborious process included a full year of negotiations with Brisbane City Council to secure approval for the now six-bedroom, nine-bathroom architectural landmark at 563 Lower Bowen Tce.
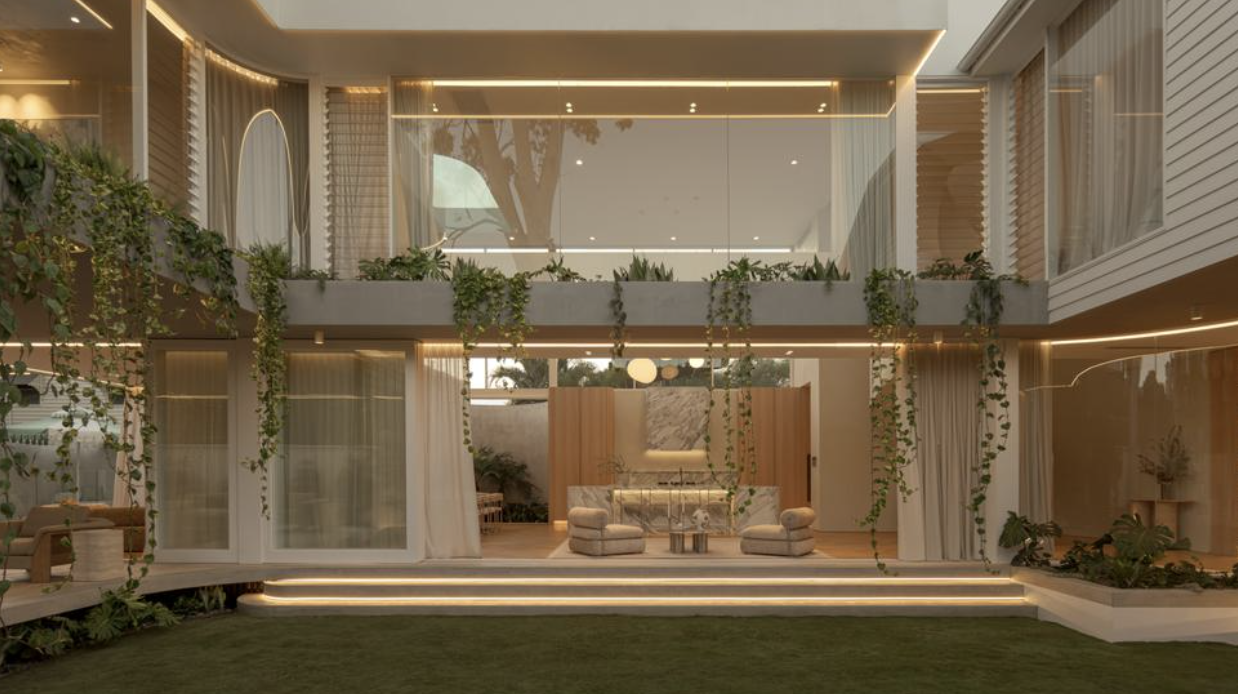
Plans for the family of five are taking another direction, and on June 13, Corazón will go under the hammer, marketed by Matt Lancashire and his team from Ray White Collective Luxury.
“This is the most incredible house I have ever seen. The quality of the build, the finish, this family poured their heart into this home for three years, and it shows in every single detail. There is nothing else like it in Brisbane,” he said.
Since the house is headed to auction, Queensland regulations prevent agents from publicly advertising price guides.
However, according to Cotality records, the current price record for New Farm is $25 million, set by a renovated home at 17 Julius St that sold for $25 million in 2025.
The top figure paid on Lower Bowen Tce was set in 2023, when a contemporary 503 sq m property at number 603 sold for $6.2 million.
Lancashire added that demand for luxury Brisbane property had never been stronger, as more cashed-up buyers seek designer homes close to the CBD.
Just this month, Lancashire and his colleague Josh Brown set a new suburb price record when Governess, an 1860s-era home in Paddington reimagined by local builder-developer Graya, sold for an undisclosed sum reported to be “more than” $12 million.
Corazón is an example of how the Australian prestige market is currently reflecting the high-end tastes of high-net-worth buyers.
Vanessa Rader, Ray White head of research, said the nation’s wellness economy – now valued at $141 billion and representing 7.8 per cent of GDP – was actually reshaping buyer expectations.
“The most significant transformation in luxury real estate is happening behind the walls,” Rader explained.
“Intelligent wellness design is no longer coming; it has already arrived in Australia’s premium property market, redefining luxury for a generation that values optimisation.”
Today, the spacious three-storey New Farm home has 963sq m of internal and external living space, crafted for Queensland’s long summers and laidback lifestyle.
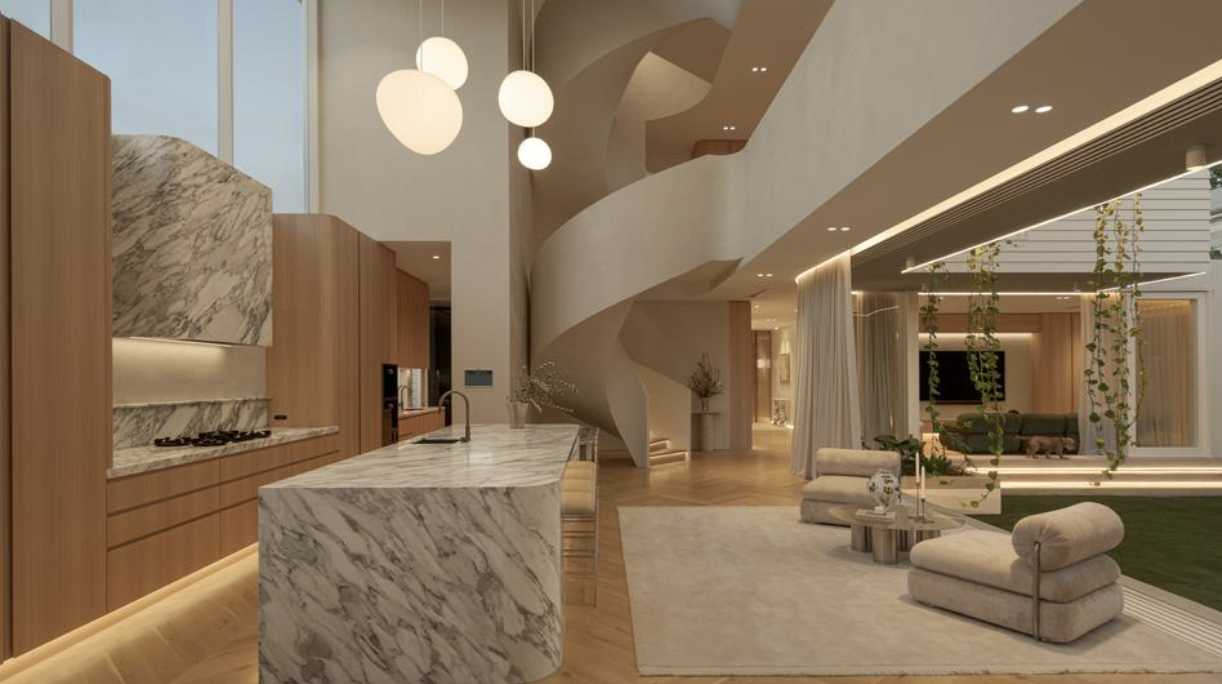
Standout design features include a dramatic double-helix spiral staircase, 3m ceilings, curved glass and steel, off-form concrete surfaces, Venetian plaster walls, and a show-stopping solid marble travertine bathtub carved from a single block of stone.
The ground floor is an entertainer’s playground with a vast open-plan living and dining zone anchored by a sleek kitchen complete with a long eat-at island bench, a hidden buyer’s pantry, plus Miele, Gaggenau and Pitt appliances.
Floor-to-ceiling glass walls peel back to reveal a paved terrace featuring a full outdoor kitchen and an integrated Beefeater barbecue.
A heated magnesium-filled pool sits next to a grassed courtyard and fire pit, with an added wellness retreat space housing a sauna, an ice bath, and a bathroom.
The entry level also houses a separate media room, a wine bar, a guest bedroom with an ensuite, a mudroom-style laundry and a home office with built-in desks.
A private lift serves all floors, including the accommodation level, which has five ensuite bedrooms, as well as a first-floor retreat and study area. In the primary suite, there is a huge dressing room, strategically placed skylights and a lavish bathroom with a double shower.
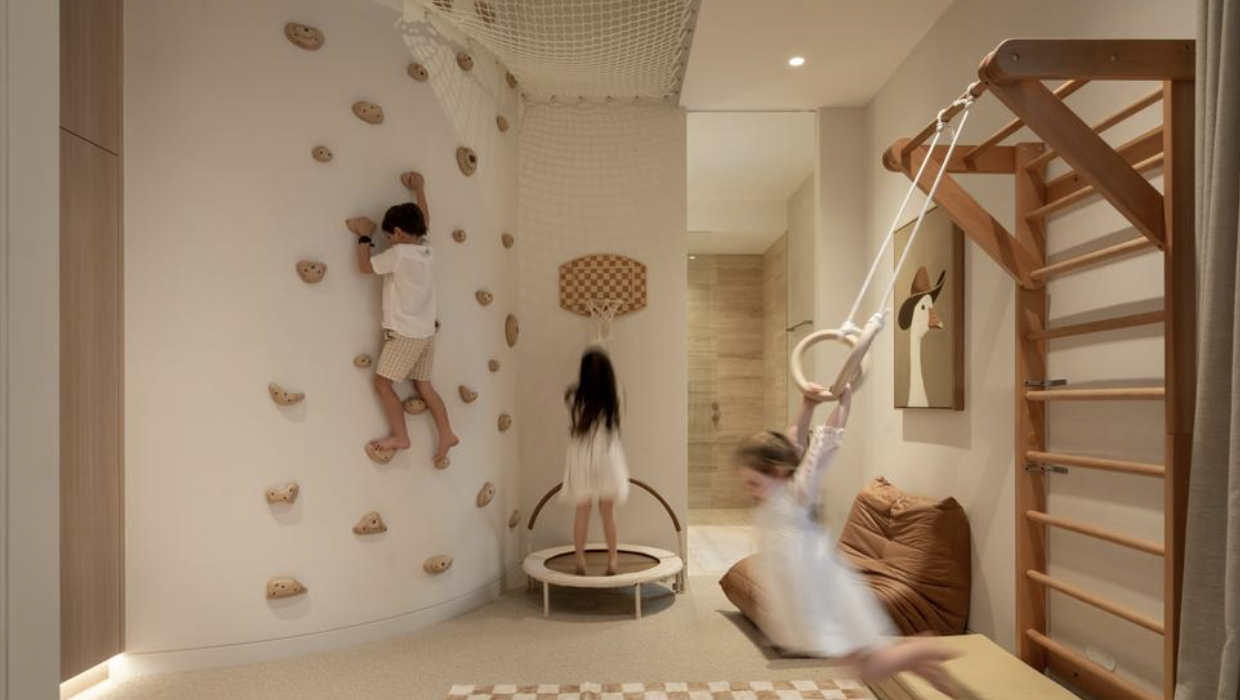
As an added bonus for the kids, one bedroom has its own rock-climbing wall and suspended net cubby.
One more level up, and the rooftop lounge with a kitchenette has sweeping city skyline views and a grand terrace.
Security features at the home include facial-recognition entry, perimeter cameras, and a comprehensive internal and external alarm system. There is also a Crestron smart home system with Dali lighting control for more than 400 fittings.
Corazón has a three-car garage with a gym and parking for up to three more cars behind the security gates. The Lower Bowen Tce home is approximately 200m from New Farm Park, 400m from Merthyr village and 2 km from the Brisbane CBD.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.

In the lead-up to the country’s biggest dog show, a third-generation handler prepares a gaggle of premier canines vying for the top prize.
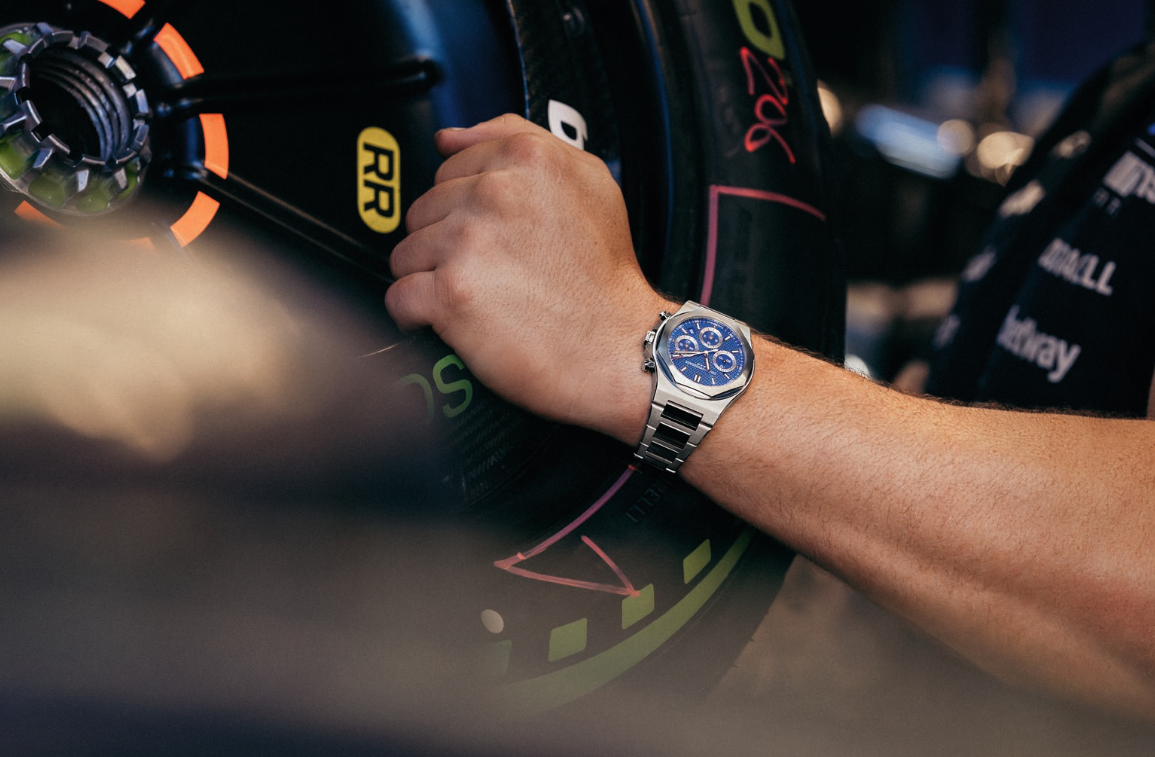
The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.


