





Australian Homeowners Stay Put: New Report Highlights Suburbs With the Longest Tenure
Here are the suburbs we love not to leave – Australia’s most tightly-held areas
 4 min
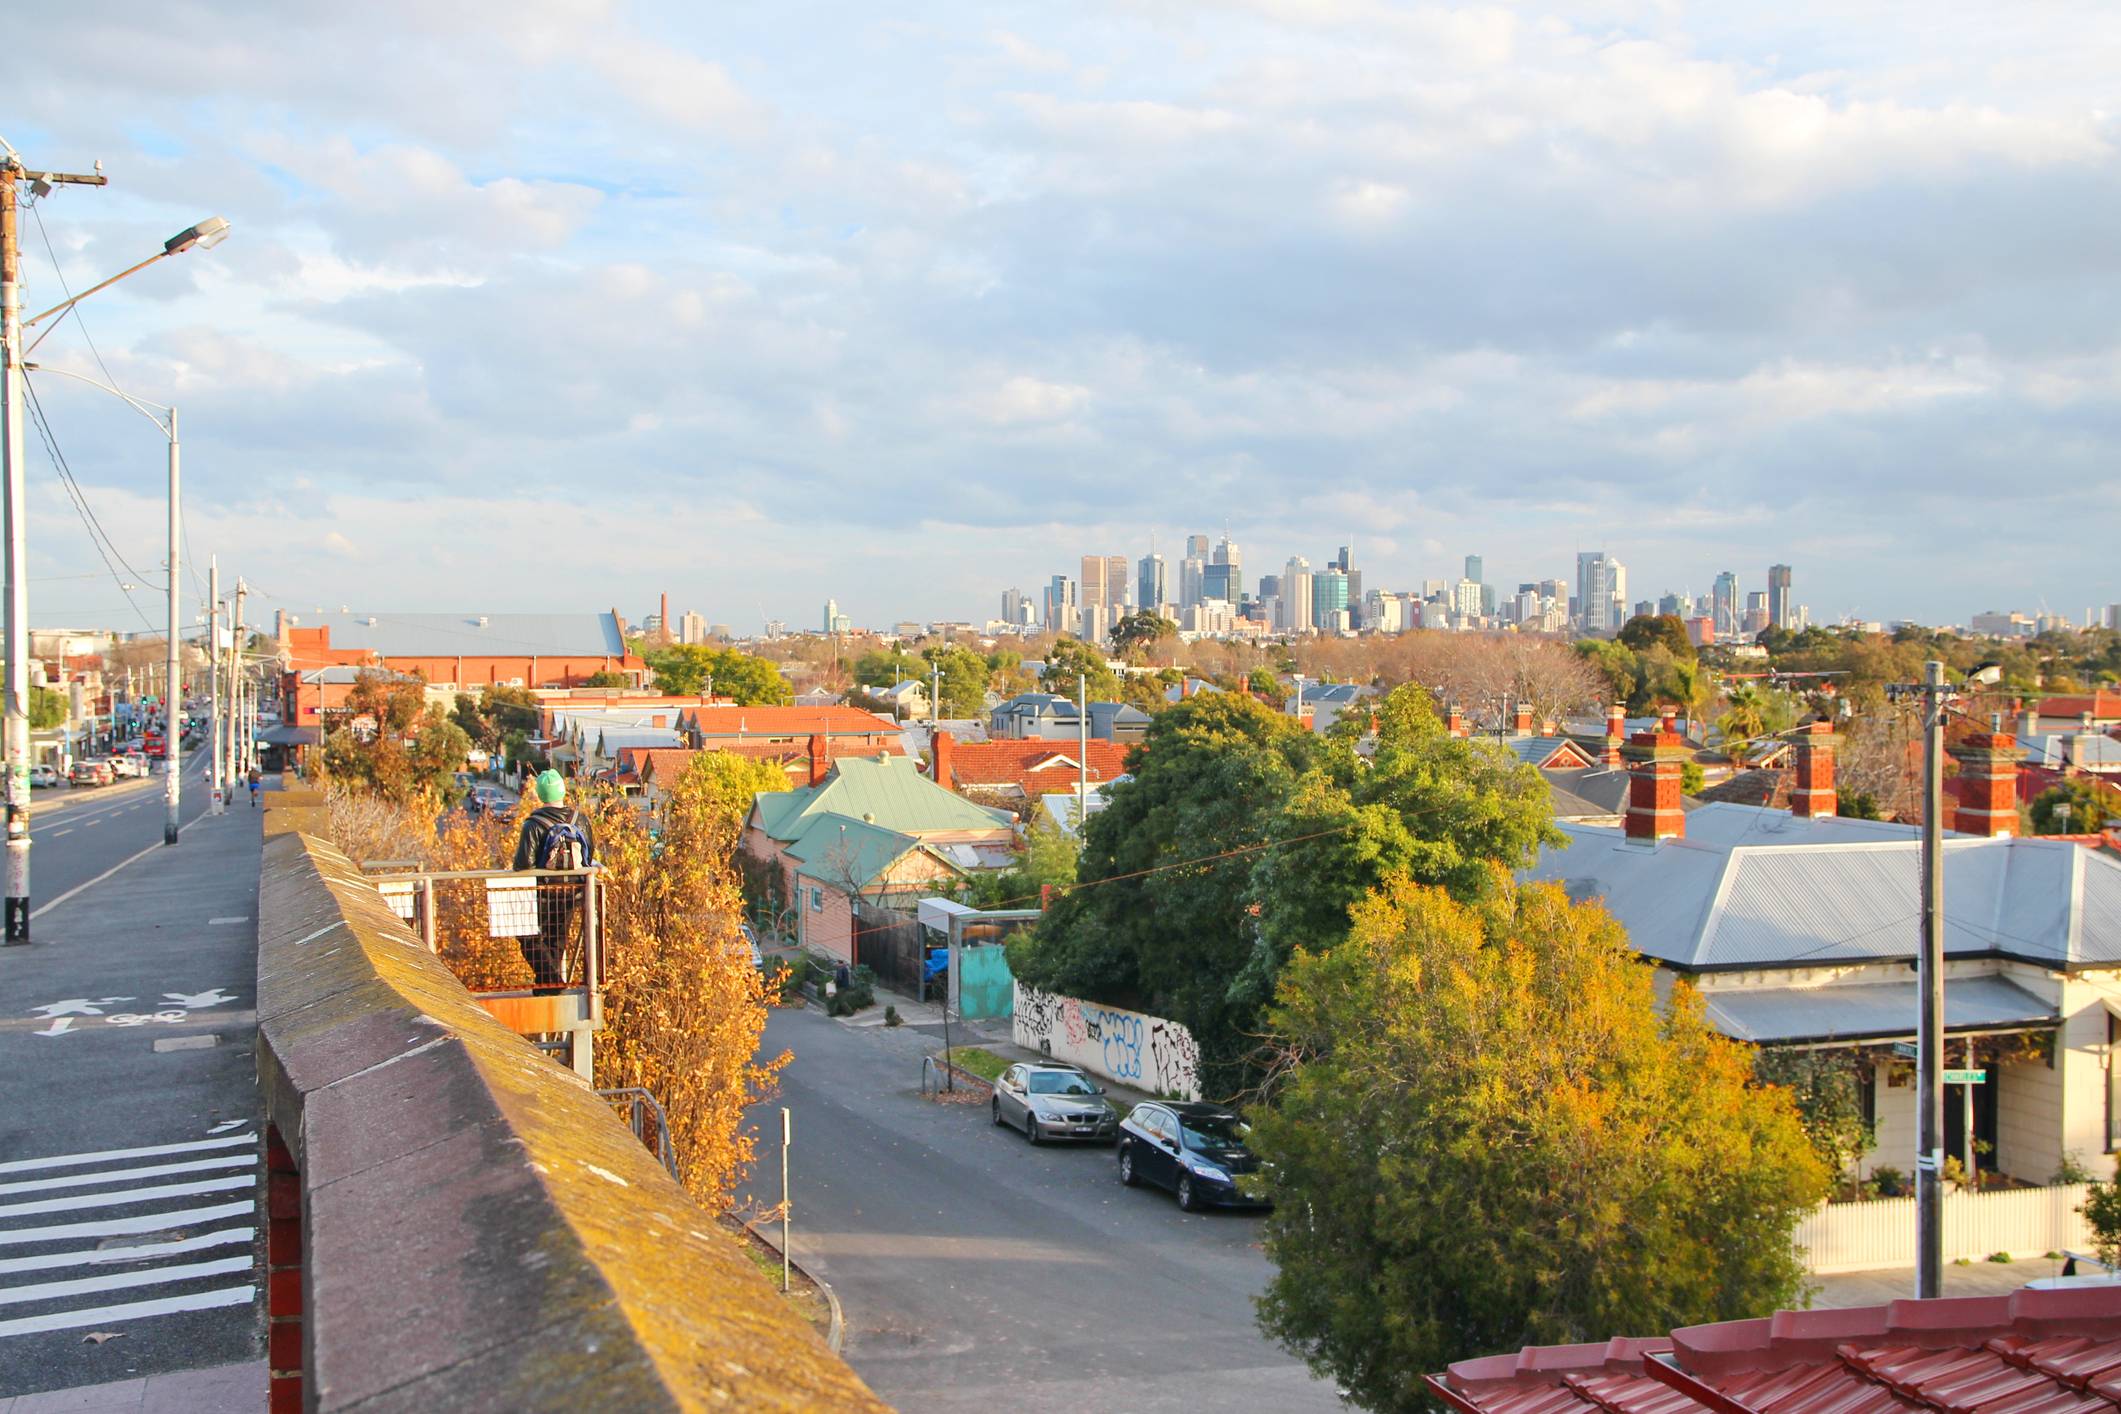
Australians are holding onto their homes for longer, as a new report reveals some of the suburbs that are the most tightly held in the country. The newly released Domain Tenure Report reveals house owners are staying put for an average of nine years, up from seven years in 2013. Apartment owners are holding their homes for an average of eight years, up from six years in 2013.
There are many reasons why tenure periods are lengthening in Australia. Across the capital cities, the most consistent tenure increases have been in Sydney and Perth houses and Sydney and Melbourne units. Housing affordability challenges are likely a factor in more home owners staying put in Sydney and Melbourne. Whereas in Perth, a long period of weak market conditions may have discouraged people from changing homes until they can sell for more than they bought. It’s cheaper to buy a house today in Perth than in any other capital city bar Darwin, so the increasing period of tenure may also reflect buyers’ ability to secure a ‘forever home’ on the first purchase.
The report notes that transactional costs associated with moving, such as stamp duty, can distort housing decisions and be a disincentive to move. “The financial burden of stamp duty can be linked to people’s willingness to change homes to suit their current needs,” according to the report.
A long average tenure period can also reflect a suburb’s high desirability or aspirational nature, perhaps due to its strong community, the style of housing, or a prized school catchment zone. Domain chief of research and economics, Dr Nicola Powell says: “There are certain areas that people tend to stay at for much longer and that’s because they are committed to the community. So, what you can find is that those tightly held areas are very hard to gain access to.” Dr Powell commented that in certain areas “people almost stalk for houses to come up since it means you’ll gain access into that suburb”.
A long average tenure can also indicate a lack of variation in local housing stock. Growing families may opt to renovate and/or extend their existing homes to suit their changing needs, thereby staying put longer. Would-be downsizers may also stay in larger homes for longer periods because there is a lack of smaller homes available in the area.
The areas with the longest average tenure periods across Australia’s capital cities are profiled below.
The suburbs we love not to leave
Strathfield-Burwood-Ashfield area, NSW (average tenure 13 years – houses)
Within the Strathfield-Burwood-Ashfield area is the suburb of Strathfield, which is known for its grand modernised Federation homes on generous blocks in wide, leafy streets. The suburb has a large number of schools including Strathfield Girls High School, Trinity Grammar, Santa Sabina College and St Patrick’s College. The area attracts older families with teenage children who want to buy forever homes in their preferred school catchments. The median price for a four bedroom house in Strathfield is $3.01 million, down 6.3% in 2023.
Whitehorse-East, VIC (average tenure 13 years – houses)
Balwyn North is the most populous suburb within the Whitehorse-East area. Located about 10km east of Melbourne CBD, it is one of the city’s most affluent suburbs. It is known for its wide, leafy streets, large parcels of land and post-war homes that have been modernised or knocked down and rebuilt over the years. Balwyn North offers close proximity to some of Victoria’s best private schools. The median price for a four bedroom house in Balwyn North is $2.345 million, up 2% in 2023.
Centenary, QLD (average tenure 14 years – houses)
Within the Centenary area of Toowoomba is the suburb of Centenary Heights, about 4km from the CBD. The suburbs attracts younger families on a budget looking for homes they can renovate or extend over time. It’s a great alternative to the pricier neighbouring area of Middle Ridge, with the median price for a four bedroom house in Centenary Heights being $615,000, up 13.5% in 2023.
Port Adelaide (average tenure 11 years – units)
The suburb of Port Adelaide has a strong maritime history and is home to the Techport naval construction base. It was developed in the 1800s and showcases some of the best preserved colonial buildings in South Australia. A sizeable part of the town centre is heritage-listed. Much residential development over the past decade has provided more apartments and townhouses, thereby attracting younger buyers who are also drawn to the thriving social and sporting scene. The median apartment price in Port Adelaide is $533,500, up 23% in 2023.
Joondalup, WA (average tenure 11 years – houses)
The suburb of Joondalup is about 26km north of Perth CBD. It is the primary urban centre of the outer northern suburbs and has its own train station, many parks and a coastal zone featuring Burns Beach in the north and Beaumaris Beach in the south. Joondalup began its journey to becoming Perth’s ‘city of the north’ in the 1980s, when many houses and businesses were established in the area. The median price for a four bedroom house in Joondalup is $633,000, up 2.9% in 2023.
North Canberra, ACT (average tenure 12 years – houses)
Within the North Canberra area is the suburb of O’Connor, which borders bushland on the edge of the CBD. O’Connor is a uniquely quiet residential area with a much-loved local village, yet is only 3km from the city centre. O’Connor is gentrifying as families seize the opportunity to buy quarter-acre blocks with 1950s homes that they can replace with architecturally designed dream homes in tranquil bush surrounds. The median price for a four bedroom house in O’Connor is $1.588 million, down 27.8% in 2023.
Litchfield, NT (average tenure 13 years – houses)
The Litchfield municipality is on the eastern and southeastern outskirts of the Darwin-Palmerston urban area. Within Litchfield is the suburb of Humpty Doo, a popular tourist spot on the way between Darwin and Kakadu National Park. The town has a thriving agricultural industry and the warm climate enables top-quality mangoes to be grown and picked earlier than Queensland fruit. The median price for a three bedroom house in Humpty Doo is $650,000, up 11.5% in 2023.
Hobart Inner (average tenure 8 years – houses)
Within the Hobart Inner area is Sandy Bay, an affluent residential suburb known for its natural beauty, with many homes enjoying spectacular panoramic water views. It is just 1km from Hobart CBD and offers a mix of historical homes and contemporary residences. It is home to many prestigious schools and has a vibrant restaurant and café scene. The median price for a four bedroom house in Sandy Bay is $1.51 million, down 9.9% in 2023.

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
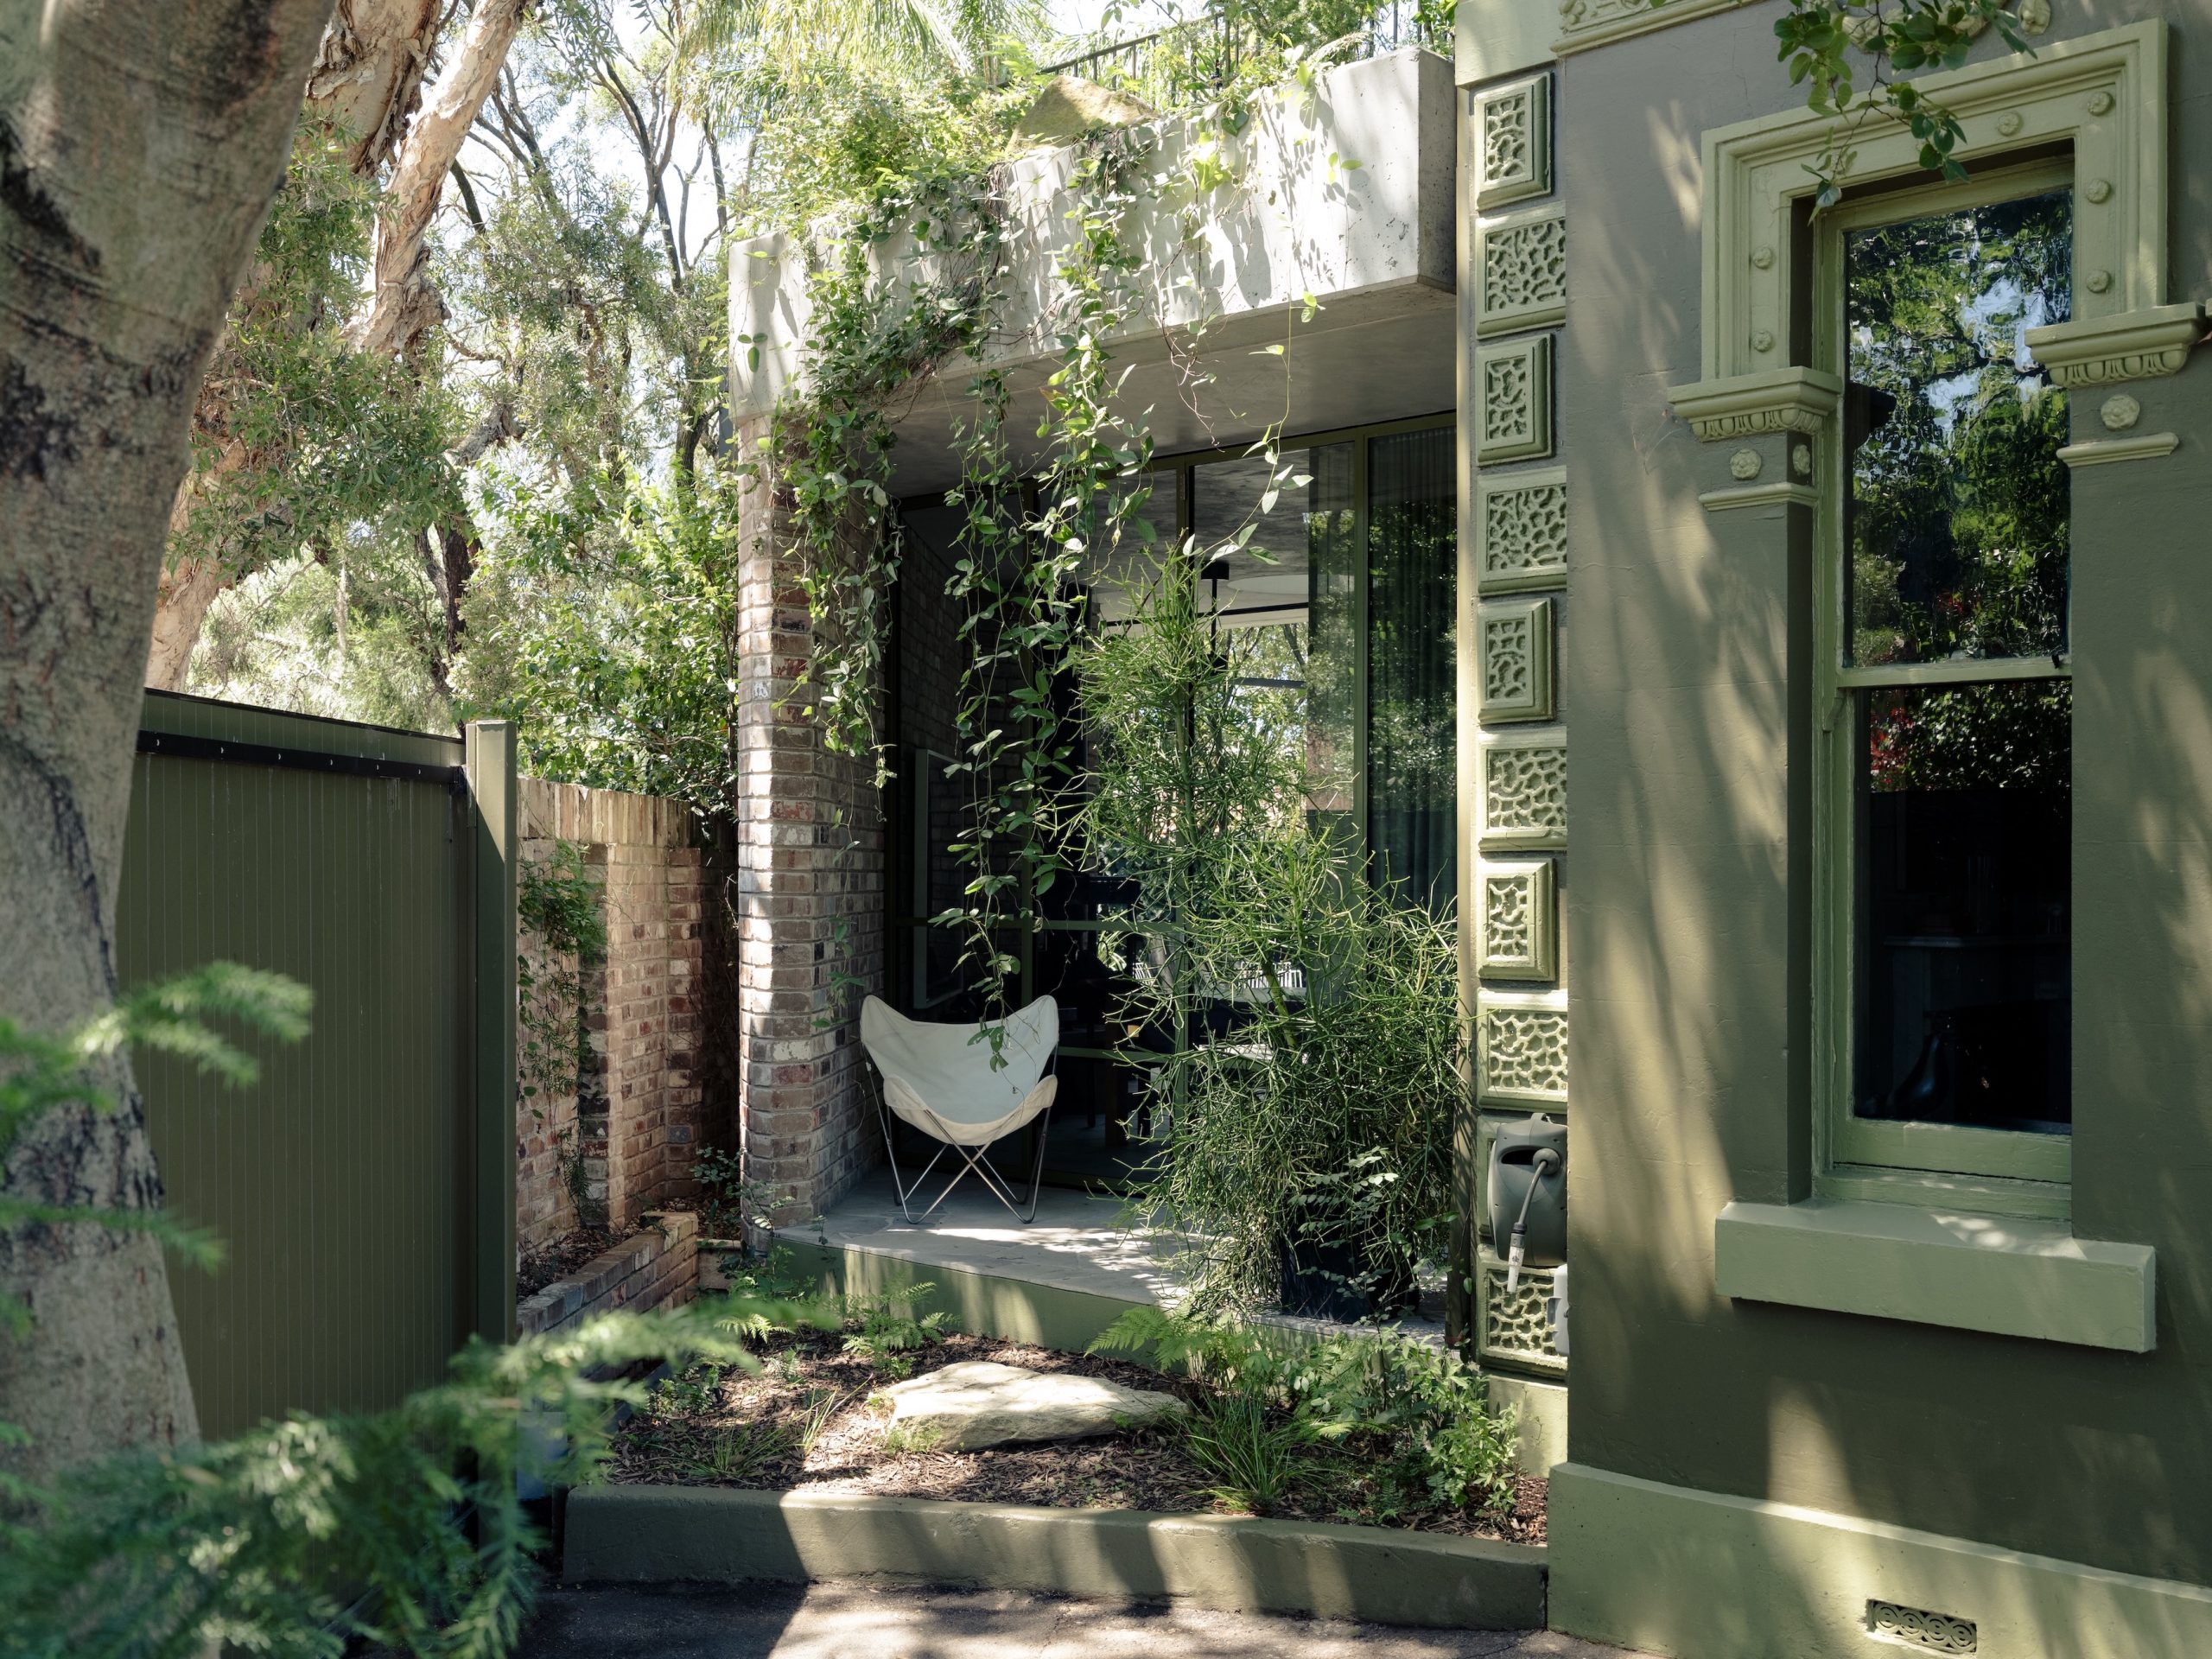
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.
When the Writers Festival was called off and the skies refused to clear, one weekend away turned into a rare lesson in slowing down, ice baths included.


