Build-to-rent apartments and rooftop gardens: how the City of Sydney is facing the future
The proposed changes are designed to address housing affordability in Sydney and increase the vibrancy of the city
 2 min
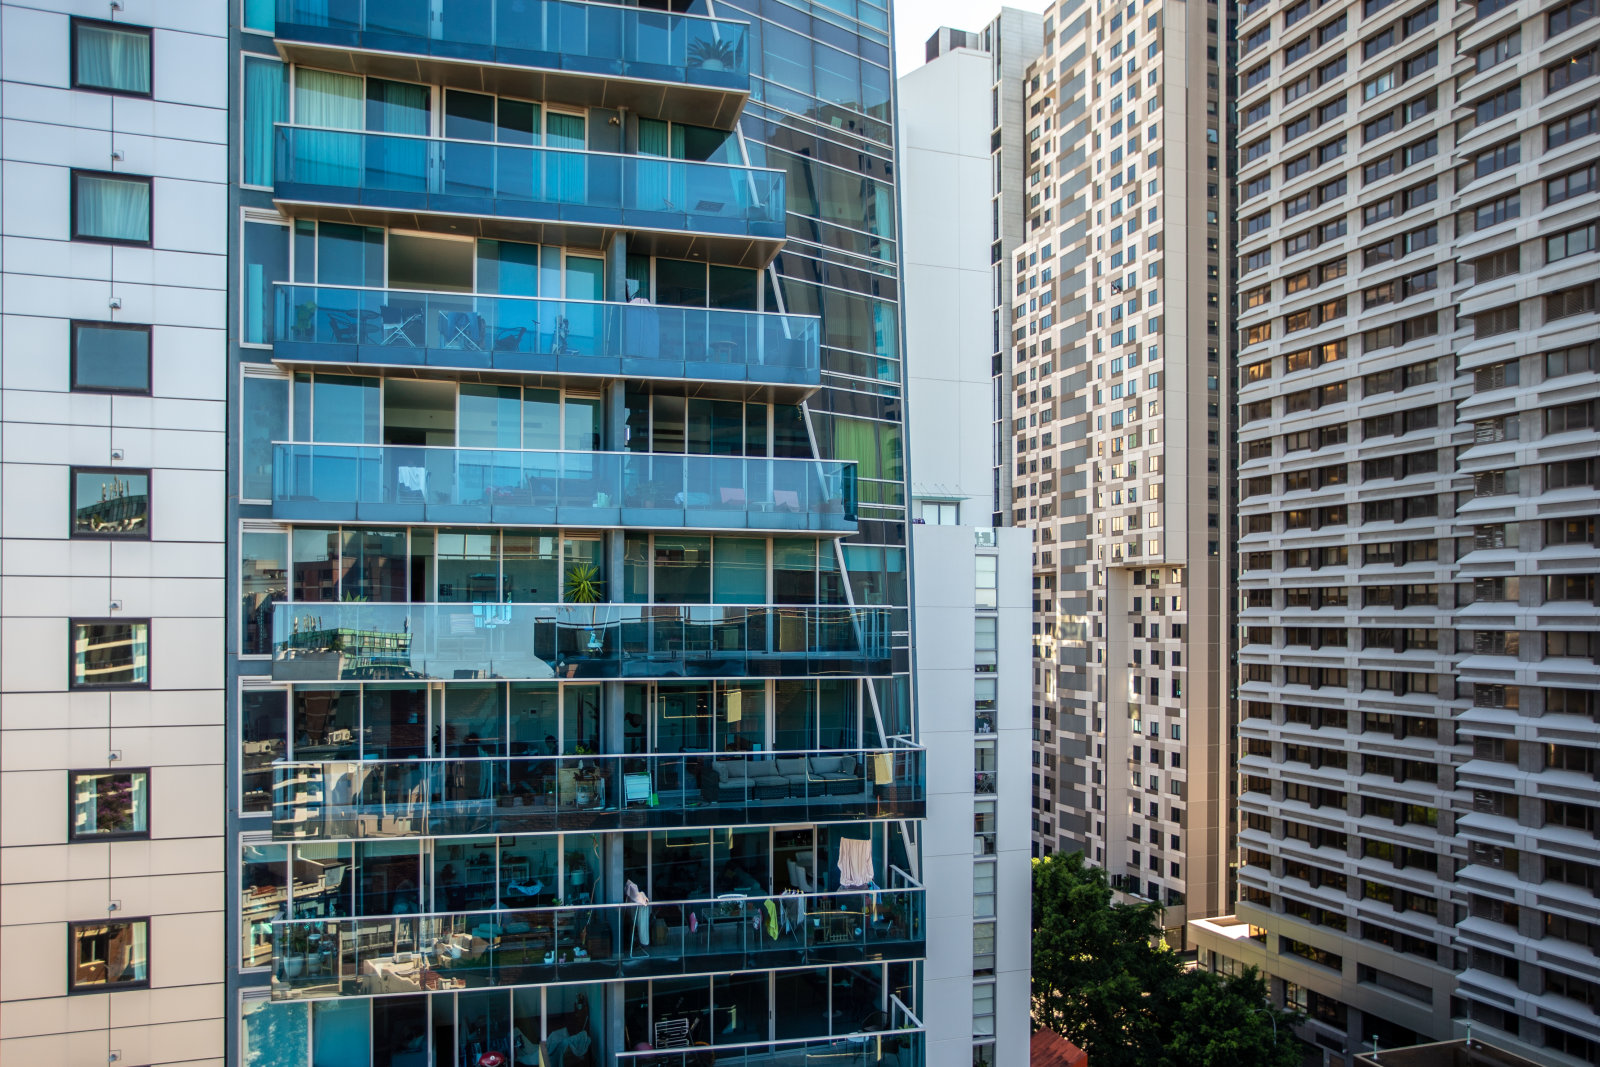
Developers could be given between 20 percent and 75 percent more floor space under plans by City of Sydney Council to encourage build-to-rent residences.
The allowance will be available to applications made within the five-year time frame from when changes to planning and development rules are approved.
City of Sydney has announced its endorsement of changes to the rules to make building family friendly and build-to-rent apartments easier. Lord mayor of Sydney Clover Moore said the proposed changes to the planning controls balanced the need for more housing with sustainability concerns and the desire to maintain the character of the city.
“Exciting changes include new incentives for build-to-rent housing in the CBD, embedded Net Zero building controls, the promotion of increased tree canopy and green roofs and a streamlined processes for design excellence and major development applications,” she said.
“We are also supporting housing diversity and addressing the loss of smaller and more affordable dwellings as a result of redevelopment.”
The concept of ‘built to rent’ properties has gained traction in recent months as a way of addressing the housing affordability crisis in major centres. The concept is one where developers and their financiers build multi-residential dwellings but, rather than selling them, retain ownership of all properties and rent them out.
Built-to-rent properties are more commonly seen in Europe and the UK, where they have been used to supply housing to those struggling with housing affordability.
Ms Moore said moving to this model would ensure higher occupational rates in inner city residences.
“That is great for inner-city vibrancy and avoids situations where international investors leave newly built flats empty for capital gain,” she said.
The Federal Government announced incentives to encourage built-to-rent development in its budget earlier this year.
The proposed changes would also encourage developers to install green roofs through height incentives, as well as allowing developers 20 percent more floor space for co-living accommodation for students and low income workers.
“We know that students are one of the groups that have been hit hardest by the rental crisis in Sydney, with lack of appropriate accommodation and affordability both major issues,” Ms Moore said.
“By offering these additional floor space incentives we hope landowners and developers will create more co-living accommodation in areas like Haymarket, which has proved popular with students in Sydney.”
Draft changes will be presented to the NSW Department of Planning and Environment.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.

A 30-metre masterpiece unveiled in Monaco brings Lamborghini’s supercar drama to the high seas, powered by 7,600 horsepower and unmistakable Italian design.
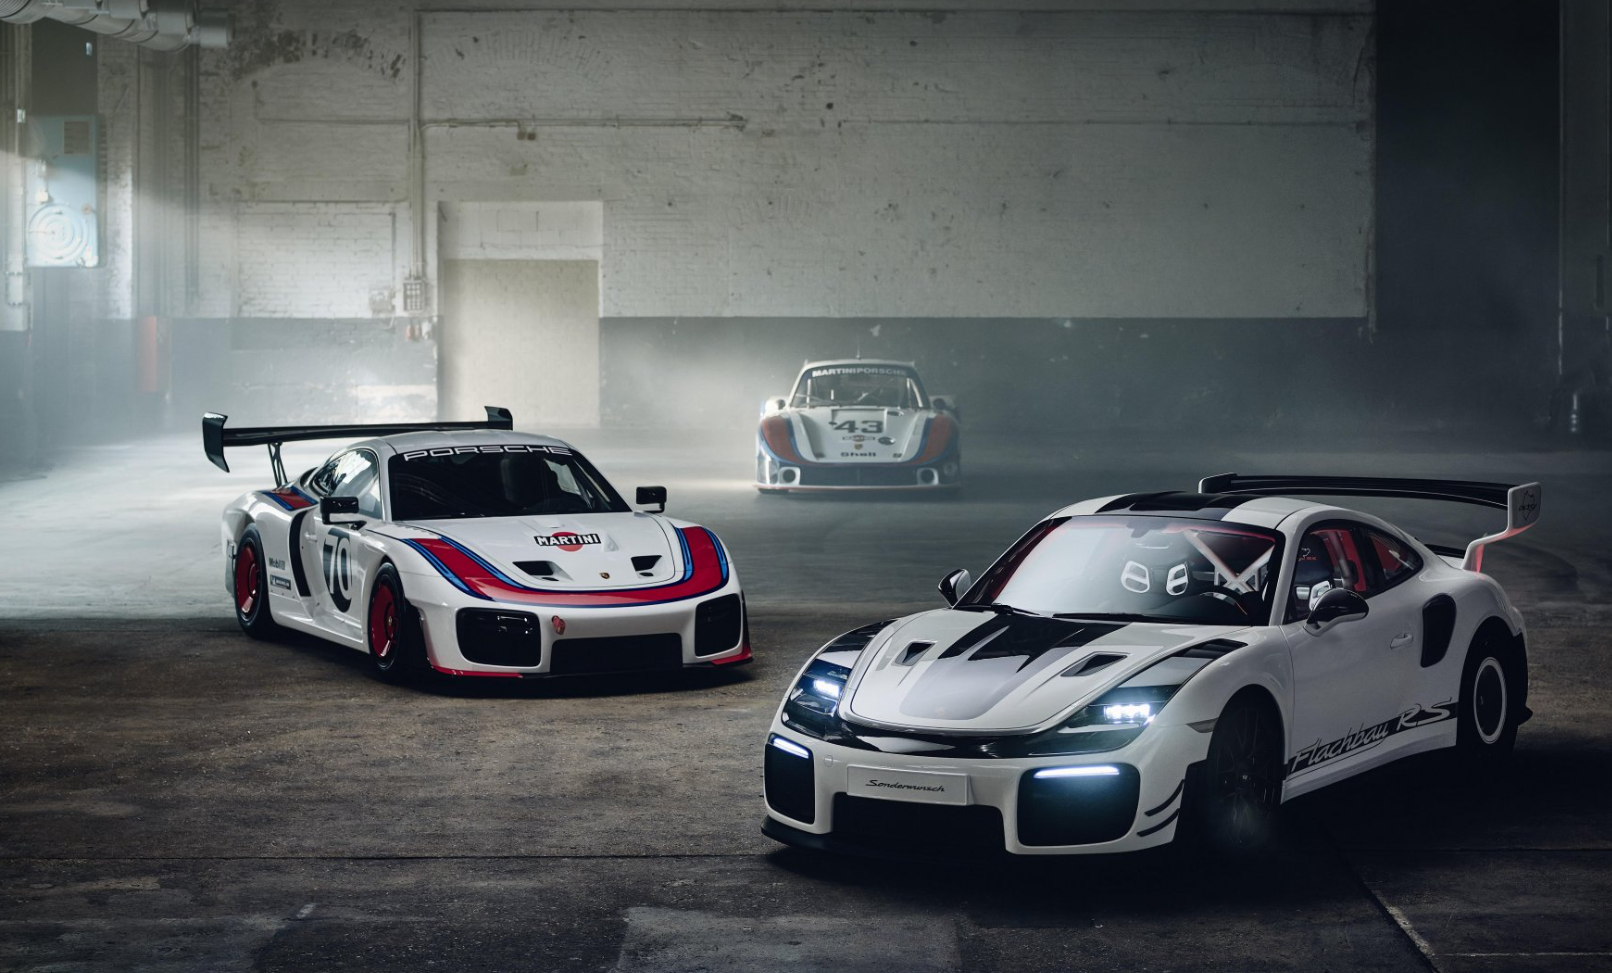
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”