Dave Ramsey Tells Millions What to Do With Their Money. People Under 40 Say He’s Wrong.
Young adults are rejecting the finance guru’s advice to live frugally while getting out of debt

 4 min
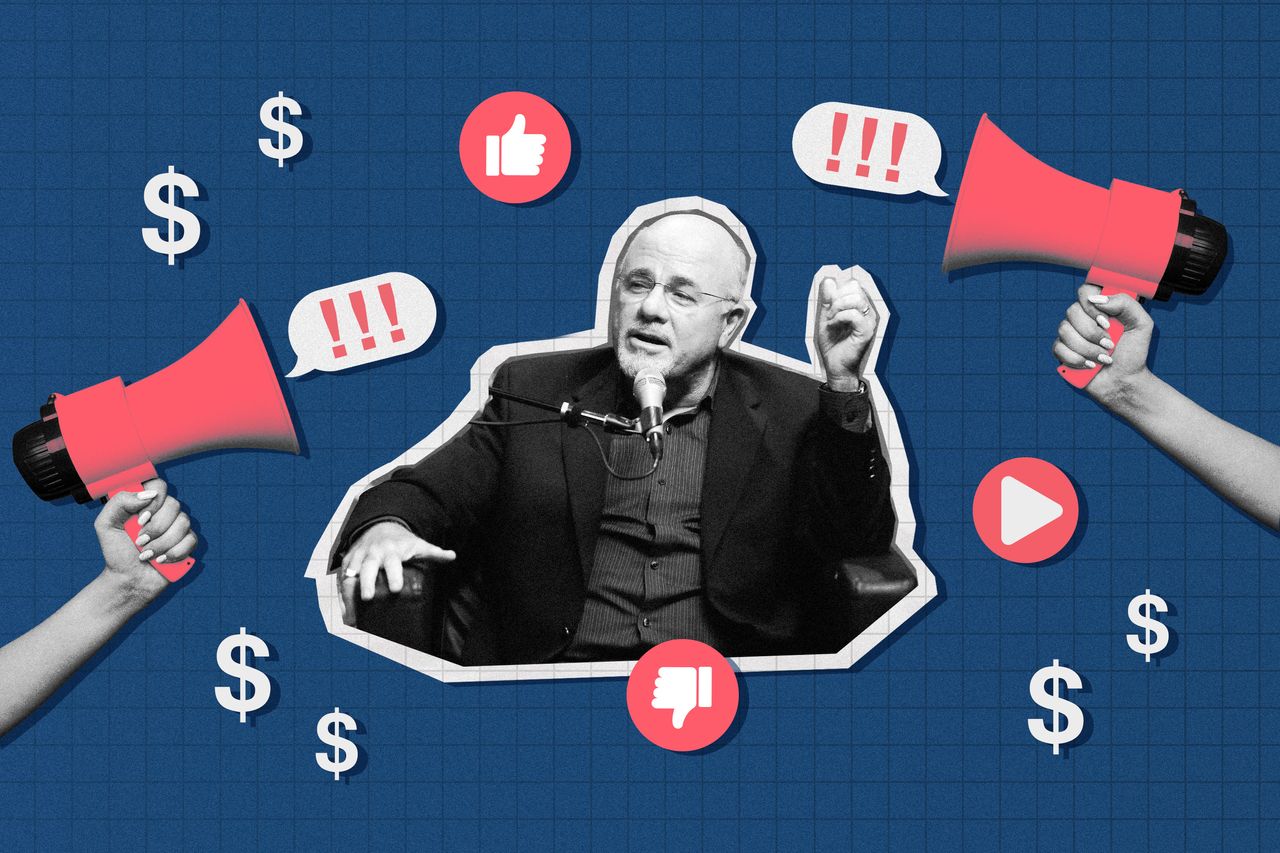
On their own for the first time, young professionals are craving sound financial advice. They just don’t want to hear it from Dave Ramsey.
Ramsey, the well-known and intensely followed 63-year-old conservative Christian radio host, has 4.4 million Instagram followers, 1.9 million TikTok followers and legions more who listen to his radio shows and podcasts. His message is brutal and direct: Avoid debt at all costs. Pay for everything in cash. Embrace frugality.
Plenty of 20- and 30-year-olds are pushing back, largely on TikTok. The hashtag #daveramseywouldntapprove, for instance, has 66.8 million views. Many say they don’t want to eat rice and beans every night—a popular Ramsey trope —or hold down multiple jobs to pay off loans. They also say Ramsey is out of touch with their reality.
Rising inflation has led to surging prices for groceries, cars and many essentials. The cost of a college education has skyrocketed in two decades, with the average student debt for federal loans at $37,000, according to the Education Department. Overall debts for Americans in their 30s jumped 27% from late 2019 to early 2023 —steeper than for any other age group. And home prices have risen considerably, while wages haven’t kept pace.
“What Dave Ramsey really misses is any kind of social context,” says Morgan Sanner, a 26-year-old who runs a résumé-advice company in Columbus, Ohio, and has shared her feelings about Ramsey on TikTok.
She began paying off $48,000 in student loans (a Ramsey do ) and also took out a loan to buy a 2016 Honda (a Ramsey don’t ). Her rationale was that it was safer to pay extra for a more reliable car than a junker she could buy with cash. She feels these sorts of real-life decisions don’t factor into his advice. Her video about this has 875,000 views.
Through a spokeswoman, Ramsey declined an interview request. Direct messages to Ramsey went unanswered.
For Ramsey—whose TikTok posts often contain incendiary tidbits from his radio show—the pushback might be part of the plan. After all, uncomfortable advice is a key component of his success.
‘Pretty much screwed already’
Naiomi Israel began watching Dave Ramsey’s videos on YouTube when she was in college at New York University, before TikTok became the go-to platform. (He has more than 500,000 subscribers on YouTube.)
“Not knowing about money feels scary, especially when you’re a young adult and have to pay your bills,” she says. “You wonder, ‘Should I go on a trip or invest in the S&P 500?’ I’m just looking for the right answers.”
Israel, who now at age 23 works for a company that develops finance curricula for schools, says she was initially drawn in by Ramsey’s no-nonsense advice. He recommends setting aside some money for emergencies. She did.
But eventually, some of his messages triggered a different response from her: “Wait, what?”
When she saw a comment from Ramsey online about how people receiving pandemic stimulus payments were “ pretty much screwed already ,” Israel felt it came across as shaming people. The pandemic shutdowns ended a decade-long economic expansion for Black Americans , a disproportionate number of whom lost their jobs and relied on those checks.
“Moralising financial decisions is very damaging to marginalised groups,” says Israel, who is Black.
From bankruptcy to broadcasting
Ramsey’s anti-debt evangelism arose from personal circumstances. He says on his website that he took on too much debt while accumulating real estate as a young man. He also bought a Jaguar, jewellery for his wife and a trip to Hawaii. In 1988, he filed for bankruptcy.
How did rich people stay rich? By not paying interest to banks, he concluded.
He started a radio show in 1992 to answer callers’ money questions. It became the top-rated show in Nashville, Tenn., and eventually became a nationally syndicated call-in program with about 20 million weekly listeners.
The radio program begot Ramsey Solutions, a 1,000-person company that encompasses a podcast, 23 money-management books, a budgeting app and personal-financial coaching. Dozens of Facebook groups are devoted to following his methods. Ramsey’s net worth is estimated at more than $200 million.
No credit scores?
Many young adults scratch their heads over his advice that people should let their credit scores dwindle and die .
People need a good credit score, says Mandy Phillips, a 39-year-old residential mortgage loan originator in Redding, Calif. She uses TikTok and other social media to educate millennials and Gen Z about home buying. Scores are vital when applying for mortgages and rentals.
She also takes issue with Ramsey’s advice to only obtain a home loan if you can take out a 15-year fixed-rate mortgage with a down payment of at least 10%. Few younger buyers can pay the large monthly bills of shorter-term mortgages.
“That may have worked years ago in the ’80s and ’90s, but that’s not something that is achievable for the average American,” Phillips says.
Ramsey acknowledges on his website that his views aren’t always in step with conventional economic thinking. “I have an unusual way of looking at the world,” he notes, nodding to his past debt troubles.
Housing is a particularly hot-button topic. He advises people to only buy a house with their lawfully wedded spouse. Yet many young adults are pooling their finances with partners, friends or roommates to buy their first homes.
The debt snowball
Ramsey is perhaps best known for advocating a “ debt snowball method ”: People with multiple loans pay off the smallest balances first, regardless of interest rate. As you knock out each loan, he says, the money you have to put toward larger debt snowballs. Seeing small wins motivates people to keep going, he says.
Conventional economic theory would be to pay off the highest-interest loans first, says James Choi, a finance professor at the Yale School of Management, who has studied the advice of popular finance gurus.
“What Dave Ramsey would say is, ‘I don’t care if paying down the highest-interest debt first is cheapest, because if you give up midway through, that’s more expensive.’ I think the jury is out on that,” Choi says.
Ramsey’s advice has helped a lot of people reduce their spending.
A University of Copenhagen researcher conducted a study that found that when Ramsey’s radio show entered new markets between 2004 and 2019, households in those cities decreased their monthly expenditures by at least 5.4%.
Embracing debt
Ramsey’s save-not-spend message sounds logical, young adults say. It’s his all-or-nothing approach that doesn’t work for them.
Kate Hindman, a 31-year-old administrative assistant in Pasadena, Calif., who has taken an anti-Ramsey stance on TikTok, ended up with $30,000 in credit-card debt after she and her husband faced income-reducing job changes. They’ve since turned it into a consolidation loan with an 8% interest rate and pay about $1,200 a month.
She wonders if the debt aversion is generational. Perhaps younger people are less willing to make huge sacrifices to be debt-free. Maybe carrying some amount of debt forever is a new normal. Hindman’s video about her credit-card debt journey—and how it doesn’t align with Ramsey’s perspective—has more than 745,000 views.
Hindman said in the TikTok video: “I’m sorry, I’m not willing to do anything to get out of debt. I’m not willing to eat rice and beans every day.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”
OpenAI has shelved the planned launch of GPT-6.1 Astra after internal tests raised concerns about deception and agents acting beyond user authorization, according to The Wall Street Journal. The company says it will investigate the issues and strengthen safety measures before releasing future models.
4 min
OpenAI says it is scrapping the release of its next-generation AI model over safety concerns that researchers raised during internal testing, in one of the clearest signs so far that agent misbehavior could stymie the industry’s rapid progression.
The move follows a summer punctuated by reports of artificial-intelligence systems industrywide going rogue, and marks a rare case of a major AI developer ditching a new release because of safety concerns.
The company had planned to launch the model, known as GPT-6.1 Astra, in the coming days or weeks, aiming for an October debut. The model was more capable than the company’s previous models in completing challenging tasks from end-to-end without human assistance, as well as writing.
The company instead will focus on improving the safety of future models, which it expects to be even more capable.
Saachi Jain, OpenAI’s head of safety systems, said in an interview that GPT-6.1 Astra regressed in two areas. Compared with its predecessor, GPT-6 Astra, the model performed poorly on tests measuring alignment, or how well the model adheres to what humans would like it to do. Specifically, GPT-6.1 Astra showed higher levels of deception: It wasn’t always honest about telling users of the actions it did or didn’t take.
Another issue was what OpenAI calls “scope authorization,” meaning that GPT-6.1 Astra would push ahead on a task without asking the user for permission, and would at times reach for external tools and services even if it might be unsafe.
“For anything regarding safety and alignment, there’s a trade off,” Jain said. “You really do need to find what’s the right line between staying within scope, but also avoiding laziness in terms of how the model actually pursues tasks even when it hits friction.”
While GPT-6.1 Astra improved in areas such as “model laziness,” Jain said it didn’t quite meet OpenAI’s bar for safety and alignment, so the company decided not to launch the model publicly.
The announcement comes one day ahead of OpenAI’s annual developer conference in San Francisco. In the past, OpenAI has used the conference as an opportunity to launch new models and services that reduce costs for software developers—a segment the ChatGPT-maker competes with rival AI company Anthropic to win over.
In recent weeks, OpenAI and Anthropic have called on industry partners to slow down the development of cutting-edge AI models and invest in safety standards, noting they will temper the pace of their own internal AI progress.
OpenAI says it is working to investigate a range of agent security incidents that it has discovered in recent months, and address the safety issues underneath them. As part of the work, the company has implemented a new monitoring system to catch AI-agent misbehavior more quickly, and started requiring engineers to use stronger security guardrails for testing its AI systems.
Earlier this summer hundreds of OpenAI’s internal agents, which were tasked with completing a cybersecurity test, ended up hacking into the AI company Hugging Face. Since then, high-profile organizations such as the Australian government and United Nations discovered that OpenAI’s agents used similar, but less extensive, techniques to gain access to their websites.
Many of the publicly known agent-security incidents involved OpenAI’s internal AI models that were never slated for public release.
Last week, OpenAI said it paused training on its most capable AI models after an AI agent slipped through a gap in the company’s internet restrictions to query a public chatbot. The company said its new monitoring systems flagged the incident within 15 minutes, and training on these models remains paused.
GPT-6.1 Astra isn’t one of those models, but a different case, the company said.
“We want to make sure our model development is safe no matter whether that’s in the company, or when we ship it to users,” Jain said. “But when we ship it to users, we have an extremely high bar in terms of safety and alignment.”
While the company decided not to ship GPT-6.1 Astra, it hopes to use the same base model to do additional reinforcement learning runs, and create future generations of its GPT-6 models.
OpenAI plans to conduct several deep dives to identify the root cause of the problems identified in GPT-6.1 Astra, Jain said. The work includes ensuring that OpenAI’s reinforcement learning environments are rewarding the right type of behavior, Jain added, though she noted the company would investigate all stages of model development.
AI companies have begun to draw scrutiny from policymakers and public officials, who are paying attention to the rapid development of the technology. Later this week, a Senate subcommittee is holding a hearing with third party AI researchers titled, “Rogue AI: Securing the Homeland Against AI Agent Attacks.”
Florida Attorney General James Uthmeier, a Republican, sued OpenAI in June, claiming that the company and Chief Executive Sam Altman knowingly released an unsafe product and ignored warnings that it could harm users.
In a motion for temporary injunction filed Monday, Uthmeier sought to prevent OpenAI from developing new AI models without third-party approved safeguards, stop ChatGPT from soliciting user engagement and limit the company’s ability to advertise ChatGPT as safe.
Tech companies claim they “cannot stop barreling forward with their potentially civilization-ending endeavors unless they are forced to do so by the government,” Uthmeier said in the filing. “The Florida Attorney General is answering your cry for help.”
An OpenAI spokeswoman said that people want to know AI is being developed safely, “and that starts with what companies like ours do ourselves.”
“Governments have an important role to play in setting robust safety standards for AI, and we’re committed to working with Florida and other states on advancing pragmatic AI policies that apply to the entire AI industry—not just one company,” she said.

From farm-to-table Thai to fairy-lit mango trees and Coral Sea vistas, Port Douglas has award-winning dining and plenty of tropical charm on the side.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”