‘Go Woke, Go Broke’ Review: The Worst Investments
Charles Gasparino of Fox Business excoriates the progressive pieties that dominate the modern boardroom.

 4 min
Charles Gasparino is a gladiatorial journalist. When he steps into the arena to fight a money-man or enterprise that he believes is anticapitalist or crooked, he can be brutal. Making an enemy of him is not for the faint-hearted: Watch him trade insults with his critics on social media. He was once a Wall Street reporter for this newspaper, where editors and colleagues remember him for his no-holds-barred style. Which is precisely how we’d describe the approach in “Go Woke, Go Broke,” Mr. Gasparino’s blistering account of “how corporate America became something close to a foot soldier in the progressive movement.” Now a senior correspondent at the Fox Business Network, Mr. Gasparino is also a columnist at the New York Post, whose irreverent, indignant (and often irresistible) tabloid style is very much in evidence here. (Fox, the Post and the Journal share common ownership.)
“Go Woke, Go Broke” is a takedown of “corporate wokeness,” which Mr. Gasparino describes as the “noxious ideology of progressive politics in the boardroom”—an ideology, he says, that “needs to die a thousand deaths.” The book can be seen as a demotic complement to “Woke, Inc.” (2021), by the brainy (and sometimes tiresome) former Republican presidential contender Vivek Ramaswamy. Mr. Gasparino’s is the better book for its plainspokenness: Many more Middle Americans—whose jobs have been outsourced or have been imperiled by the high-minded dictates of “diversity”—will grasp its message. These are the people who, Mr. Gasparino argues, have been shafted by the Wall Street “fat cats” who’ve grown “much fatter” by their “feeding at the ESG trough.”
ESG stands for “environmental, social, and governance”—metrics intended to direct or funnel investment in an ostensibly socially responsible direction. Mr. Gasparino is a populist-capitalist, and ESG is his bête noire, along with “diversity, equity, and inclusion” (DEI). These “leftist shibboleths” have, the author says, “warped” American business practices for nearly two decades and grew in intensity under the second Obama administration.
Mr. Gasparino traces the roots of ESG to the 1980s and ’90s, when business leaders began embracing so-called corporate social responsibility (or CSR, in its now archaic abbreviation). CSR, in time, evolved into bien-pensant notions of stakeholder capitalism, championed by the likes of Klaus Schwab, the founder of the World Economic Forum in Davos, Switzerland. Davos Man, writes Mr. Gasparino, “represents the ultimate marriage of the progressive globalist corporate citizen with the globalist progressive regulatory bureaucrat.”
All this performatively moral investing is a revolt against Milton Friedman, the economist who in 1970 stated that “the social responsibility of business is to increase its profits.” Friedman, writes Mr. Gasparino, would have hated ESG and DEI, “among the most heinously anti-American management philosophies ever developed.” (Readers of Mr. Gasparino’s robust book will realize pretty quickly that nuance is for wimps.)
Basing his book largely on a host of interviews with “company insiders,” Mr. Gasparino gives us entertaining (and informative) accounts of corporate blunders in the name of wokeness. He reminds us of the time AB InBev—the holding company for Anheuser-Busch and its beer, Budweiser—thought it would be a great idea to use a “transwoman influencer” named Dylan Mulvaney to market its top-selling Bud Light. Middle America revolted and stopped buying the beer, heretofore branded as a manly beverage. Mr. Gasparino also recounts how the discount retailer Target was punished by consumers for promoting “tuck-friendly bathing suits for men transitioning to women” alongside rainbow-colored onesies for toddlers. And Disney, recalls the author, erred politically and financially when its chief executive, Bob Chapek, embarked on a bruising battle with Florida’s Gov. Ron DeSantis and challenged the validity of a state law barring public schools from teaching sexual education to children before the fourth grade. In each case, the company’s stock price tanked and sales plummeted.
It enrages Mr. Gasparino that America’s corporate management luxuriates “in progressive causes as a side hustle.” But in some cases, he tells us, these causes are the main course. Among the villains trying to ram ESG down our throats are Larry Fink, the CEO of BlackRock; Jamie Dimon, the CEO of JPMorgan Chase; David Solomon, the CEO of Goldman Sachs; and the “ESG-obsessed” Gary Gensler, President Biden’s chairman of the Securities and Exchange Commission, whom Mr. Gasparino describes as “a male version” of Sen. Elizabeth Warren, “among the most woke, annoying, and . . . dangerous bureaucrats in government.” Add to the list Adena Friedman, the CEO of Nasdaq, which demands that companies seeking to list on its exchange disclose board-level diversity statistics and, if the need arises, explain why they don’t have a diversity of directors. Such demands aren’t, of course, slapped on Chinese companies, which are, Mr. Gasparino points out, curiously exempt from all the wokest rules. When was the last time a Chinese company was asked why it didn’t have a Uyghur on its board, or an LGBTQ+ person?
Attacking Larry Fink as “Mr. ESG,” says Mr. Gasparino, has become “a rallying cry on the populist right,” whose backlash against corporate wokeness has been so fierce that even BlackRock has started to dismount from its moral high horse. Consumers’ Research, a conservative advocacy group pushing back against ESG, derides the abbreviation as “elitists, socialists, and grifters,” as well as “erasing savings and growth”—pungent and effective put-downs. More and more investors are aware that ESG-specific funds are expensive and rarely beat the market. In fact, writes Mr. Gasparino, “they’re some of the worst investments,” even as they make it harder to tackle inflation by forcing curbs on fossil fuels. But Middle America appears to have woken up to the perils of ESG and is giving voice to its displeasure. “It’s now their Arab Spring,” says Mr. Gasparino. This may be hyperbolic overreach, even for the crusading Mr. Gasparino, but he’s confident that America’s version of a grassroots people’s revolt will end better than the one in the Middle East. Let’s pray he’s right.
Mr. Varadarajan, a Journal contributor, is a fellow at the American Enterprise Institute and at Columbia University’s Center on Capitalism and Society.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min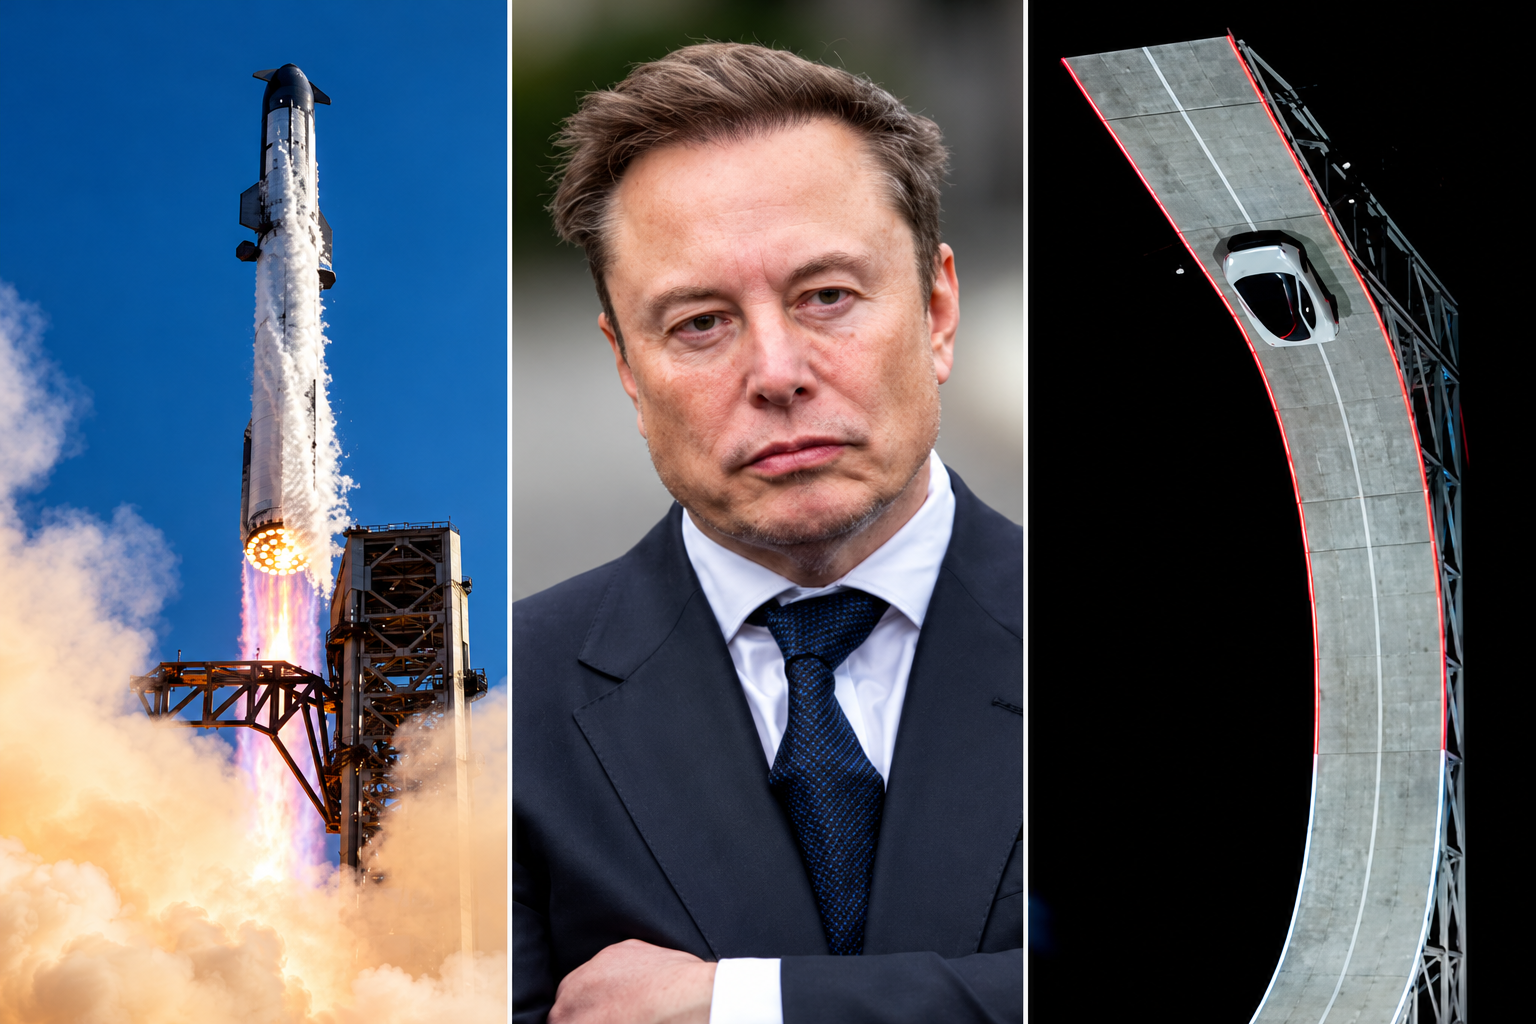
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.

A long-standing cultural cruise and a new expedition-style offering will soon operate side by side in French Polynesia.