Elon Musk Tries to Direct AI—Again
His latest startup follows a decade of being outmanoeuvred in his quest to steer the development of artificial intelligence

 6 min
For at least a decade, Elon Musk has tried to steer the development of artificial intelligence—only to be outmanoeuvred by rivals and former allies.
He has now stepped up his efforts after the success of OpenAI, an organisation he co-founded but then left after a power struggle. Mr. Musk has warned for years that poorly built artificial intelligence could have catastrophic effects on humanity. Since OpenAI’s ChatGPT became a viral sensation last November, Mr. Musk has denounced it as politically correct and warned it could lead AI to become too powerful for humans to control.
He has called his new effort TruthGPT, and billed it as a truth-seeking artificial intelligence model that will one day comprehend the universe. On March 9, he incorporated a company called X.AI in Nevada, laying the formal groundwork.
So far, he has struggled to define a precise vision for his startup and is still in the process of assembling a team, said people familiar with the matter. Musk’s representatives have said X.AI intends to raise cash at some point from investors, the people said.
Mr. Musk didn’t respond to requests for comment.
Two weeks after incorporating X.AI, Mr. Musk signed an open letter calling for a six-month pause on the development of AI models stronger than the latest one released by OpenAI, called GPT-4. The letter was organised by the Future of Life Institute, which says its goal is to steer transformative technology away from extreme, large-scale risks. Its biggest funder is Mr. Musk.
Steven Weber, a professor at the University of California, Berkeley who met Mr. Musk several years ago at a gathering of A.I. academics in Northern California, sees a consistent thread through what appear to be opposing impulses.
“He holds both of these beliefs at once: that human beings can’t be relied on to really control technology, and technology is going to advance and it needs to advance subject to his vision, more than anybody else,” Mr. Weber said.
“AI stresses me out,” Mr. Musk said at the end of a March presentation given to Tesla Inc. investors. “It’s quite dangerous technology. I fear I may have done some things to accelerate it.”
For X.AI, he hired Igor Babuschkin, a senior scientist at DeepMind, an AI lab under Alphabet Inc.’s Google, to lead the effort, people familiar with the matter said. Mr. Musk also purchased powerful computer chips similar to ones used in the technology behind ChatGPT, one of the people said.
He is still trying to attract top talent from leading labs and universities, people familiar with the matter said. Some AI researchers said they have been turned off by Mr. Musk’s struggles to turn Twitter around since acquiring the social-media company in October, as well as his public attacks on OpenAI.
Mr. Musk’s faltering attempts to steer AI’s development date back more than a decade. He has previously said he made an early investment in DeepMind, founded in 2010, to monitor its AI research rather than make money.
In late 2013, he launched a last-minute bid to purchase DeepMind, the leading AI lab at the time, but lost out to Google, according to people familiar with the talks. Mr. Musk wanted to steer the lab’s research and told associates that Google’s then-Chief Executive Larry Page couldn’t be trusted to oversee the creation of advanced AI, according to people familiar with his thinking.
DeepMind has become a central element of Google’s efforts to infuse advanced AI into its search powerhouse, and recently merged with another AI unit called Brain to form Google DeepMind. In a recent interview with Tucker Carlson on Fox News, Mr. Musk said he and Mr. Page used to be close friends who spent nights discussing AI safety at Mr. Page’s home in Palo Alto, Calif.
Mr. Page wanted to create a “digital god” as soon as possible, Mr. Musk said, and in their conversations called Mr. Musk a “speciesist” for saying it was important that the technology protected humanity.
Mr. Page and representatives at Google didn’t respond to requests for comment.
Mr. Musk’s interest in buying DeepMind was informal and didn’t reach the DeepMind board, according to the people familiar with the talks. It hasn’t previously been reported.
Mr. Musk co-founded OpenAI two years later with Sam Altman, the current chief executive, and several others. The organisation was founded as a nonprofit and intended to serve as a counterweight to Google, with the goal of developing AI in a safer, more transparent way than large tech companies could.
Mr. Musk served as the financial linchpin for the project and promised to make sure that OpenAI fully received the $1 billion in funding promised by early backers, people involved with the effort said. He recruited employees and met regularly with company leaders to set the vision, they said.
Mr. Musk set an aggressive research timeline for OpenAI, warning that the company’s credibility would be compromised if it didn’t achieve a major breakthrough soon after its launch, according to former employees familiar with the remarks. He often conducted polls among employees to see when they thought so-called artificial general intelligence—in which machines are able to match or surpass the intelligence of humans—could be achieved, former employees said.
In September 2017, Mr. Musk told his brother, Kimball Musk, and a longtime financial backer that he saw OpenAI and Neuralink, a startup he founded to link humans with computers through brain implants, as worthy of more of his time, according to recently released court documents related to a lawsuit against Tesla over Mr. Musk’s compensation.
“OpenAI and Neuralink are both critical to a good future for humanity. My instincts tell me that I should be devoting a much higher percentage of time to them,” Mr. Musk texted them, according to the documents. OpenAI and Neuralink at one point shared an office in San Francisco.
Mr. Musk grew frustrated with what he saw as OpenAI’s slow progress and pushed for more control of the company, The Wall Street Journal previously reported. At the time, OpenAI didn’t have a chief executive or a formal management structure.
Mr. Musk clashed with Mr. Altman, who wanted to create a for-profit arm that would allow OpenAI to raise cash from investors, people familiar with the matter said.
Mr. Musk subsequently left. Mr. Altman, who has said he considers Mr. Musk a mentor, became CEO in 2019, created a for-profit entity and raised $1 billion from Microsoft Corp.
Mr. Musk tweeted in March that he had donated around $100 million to OpenAI, though people familiar with the figure said he contributed less than $50 million.
Mr. Musk focused his AI efforts at Tesla, where he made progress in using the technology to enhance its driver-assistance systems. He said the EV maker would start introducing a fleet of robotaxis by 2020, and showcased a humanoid robot he said would feature safeguards to prevent wrongdoing by the machine.
Regulators are scrutinising Tesla’s driver-assistance software for safety problems. The company has yet to roll out robotaxis, which rely on the kind of driverless technology that Google sister company Waymo and General Motors Co.’s Cruise LCC have begun to deploy.
Mr. Musk grew more publicly critical of OpenAI after the company released ChatGPT last fall, accusing the company of being a “maximum-profit company” controlled by Microsoft. “Not what I intended at all,” he tweeted.
In a March 28 interview with the Journal, Mr. Altman said OpenAI took its safety obligations seriously.
“We spent more than six months after we finished GPT-4 to safety test, to align it, to really probe its capabilities, at a time when I believe some of the [Future of Life Institute] letter signatories were even, you know, pushing us to release it faster,” Mr. Altman said. He declined to specify which signatories he meant but said seeing those names prompted “some eye rolls.”
In early 2023, Mr. Musk texted Mr. Altman that he was starting a rival AI effort, according to people familiar with the exchange. Mr. Altman wished him well but said he didn’t understand how a new lab would allay Mr. Musk’s concerns about AI development, they said.
One OpenAI board member, Shivon Zilis, stepped down in part due to a conflict of interest with Mr. Musk’s new AI efforts, said people familiar with the matter. Ms. Zilis is also an executive at Mr. Musk’s Neuralink and had twins with Mr. Musk in 2021. Ms. Zilis didn’t respond to a request for comment.
After ChatGPT’s release, Mr. Musk said on Twitter that he cut off OpenAI from access to a pipeline of Twitter data, which OpenAI could potentially use for training the AI models powering ChatGPT. “I just learned that OpenAI had access to Twitter database for training,” Mr. Musk tweeted in early December. “I put that on pause for now.” People familiar with OpenAI say the company didn’t use this Twitter data to train its models.
A few days later, Mr. Musk visited OpenAI’s San Francisco headquarters at Mr. Altman’s invitation and the two had what turned into a lengthy discussion about the Twitter decision, among other topics, according to current and former OpenAI employees.
At one point, an OpenAI researcher showed Mr. Musk how Twitter could potentially use ChatGPT. Mr. Musk brought one of his toddlers and a nanny, some of the people said, and he and the nanny took turns bouncing the child on their laps when the child grew fussy.
He struck a benign tone with employees, who found him wandering around the kitchen and hallways with his security detail, the employees said.
In one conversation, Mr. Musk entertained the idea that the universe was a computer simulation, they said. Soon after, he left the building.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
From early financial mistakes to hard-earned habits, five high-performing leaders share how they spend, invest and think about wealth.
9 min
Five minutes doesn’t sound like much. But it’s enough time to tell whether someone really understands money or just talks about it. Because once the gloss is stripped away, what’s left is instinct. The early mistakes. The bad calls. The quiet pivots that no one brags about but shape everything that follows. Making money is one thing. Living with it, and not mishandling it, is another. Here, five executives talk about what they got wrong, what they’ve learned, and how they now actually spend, invest and think about wealth.
Andrew Raso: Founder, Online Marketing Gurus
Self-made millionaire Andrew Raso grew up in an ethnic household with a father in construction. Investing was not a priority, he recalls.
The co-founder and CEO of Online Marketing Gurus, a digital marketing platform that generated more than $30 million in revenue in the 204/25 financial year, admits he’s had to learn about handling money as his wealth has grown.
“If I had my time again, I would change my spending habits and would probably be a lot more wealthy as a result,” the Sydneysider tells Kanebridge Quarterly.
Raso, in his mid-30s, says that his biggest lessons have come from his losses.
Buying the wrong property and copping the losses upon sale. Feeling FOMO when buying crypto and making a purchase that lost money.
“I’ve learned a lot from the errors that I’ve made,” he says.
Raso admits that he gets more of a thrill out of working than watching money hit his bank account.
“I’ve had the cars, I’ve had the property, I’ve had the watches. Once you’ve had them, they’re not that exciting, but the process of earning money is pretty cool.”
What he won’t forget is being $45 million in property debt a few years ago.
“I’d never want to be in that position again,” he says.
“My investing strategy is a lot safer these days. I’m very cautious. I’d prefer to invest in things that don’t take as long to be realised so my family can be financially secure.
“Once you have a house paid off and a few investments, it then becomes about enjoying your money, rather than hoarding it. Giving back gives me a much bigger kick than spending these days.”
Daniel Wessels: CEO, Jacaranda Finance
Fintech founder Daniel Wessels knows only too well that money remains a taboo topic in Australia with many people.
He points to consumer surveys that reveal people are more likely to talk about their sex life with friends than their finances.
It’s a major concern for the man who founded Jacaranda Finance in 2013, which has helped countless people lift their credit scores and get their finances back on track.
“If people aren’t learning money habits at school and they aren’t discussing it with their friends, learning new strategies and better habits is difficult,” says Wessels, who is based in Brisbane.
He wants to see more people take the time to proactively understand where and why they are spending money.
“Everyone needs to have a financial strategy and a plan to measure if it’s working,” he says.
The father of two young children admits his week can be pretty fast-paced. Pomodoro clocks, sleep optimisation techniques and saying ‘no’ keep him on task during the week.
“I used to think I was fairly decent at managing time, but the whole game changed when we had kids,” he says.
“Now, I’ve got to get out of the house at a certain time and leave the office at a certain time for daycare pickup. I’ve got to be really specific about my tasks to maximise my week.”
Before he had a family, he loved heading out to one of the trendy new restaurants popping up in Brisbane.
But that happens less these days. He’s saving to build his forever home but admits that price rises have resulted in rising costs.
“It’s such a big project with so many variables that change quickly,” he says.
These days, Wessels likes to optimise his professional and personal life. “With only a finite amount of money, time and energy, you’ve got to be really good at deciding what you want to be good at,” he says.
He calls this ruthless prioritisation. He has a very specific focus on activities that prioritise health and wealth, adding experiences into the mix more recently. This has meant the addition of micro-holidays to his annual calendar.
Wessels works with a couple of financial advisers. That said, he also does his own due diligence before agreeing to investments.
“One likes private equity investments that pay cash every month and another prefers to focus on the NASDAQ Stock Exchange for buying shares because he’s bullish about that.” he says. “They’re each experts and really good at what they do.”
Jim Penman: CEO, Jim’s Group
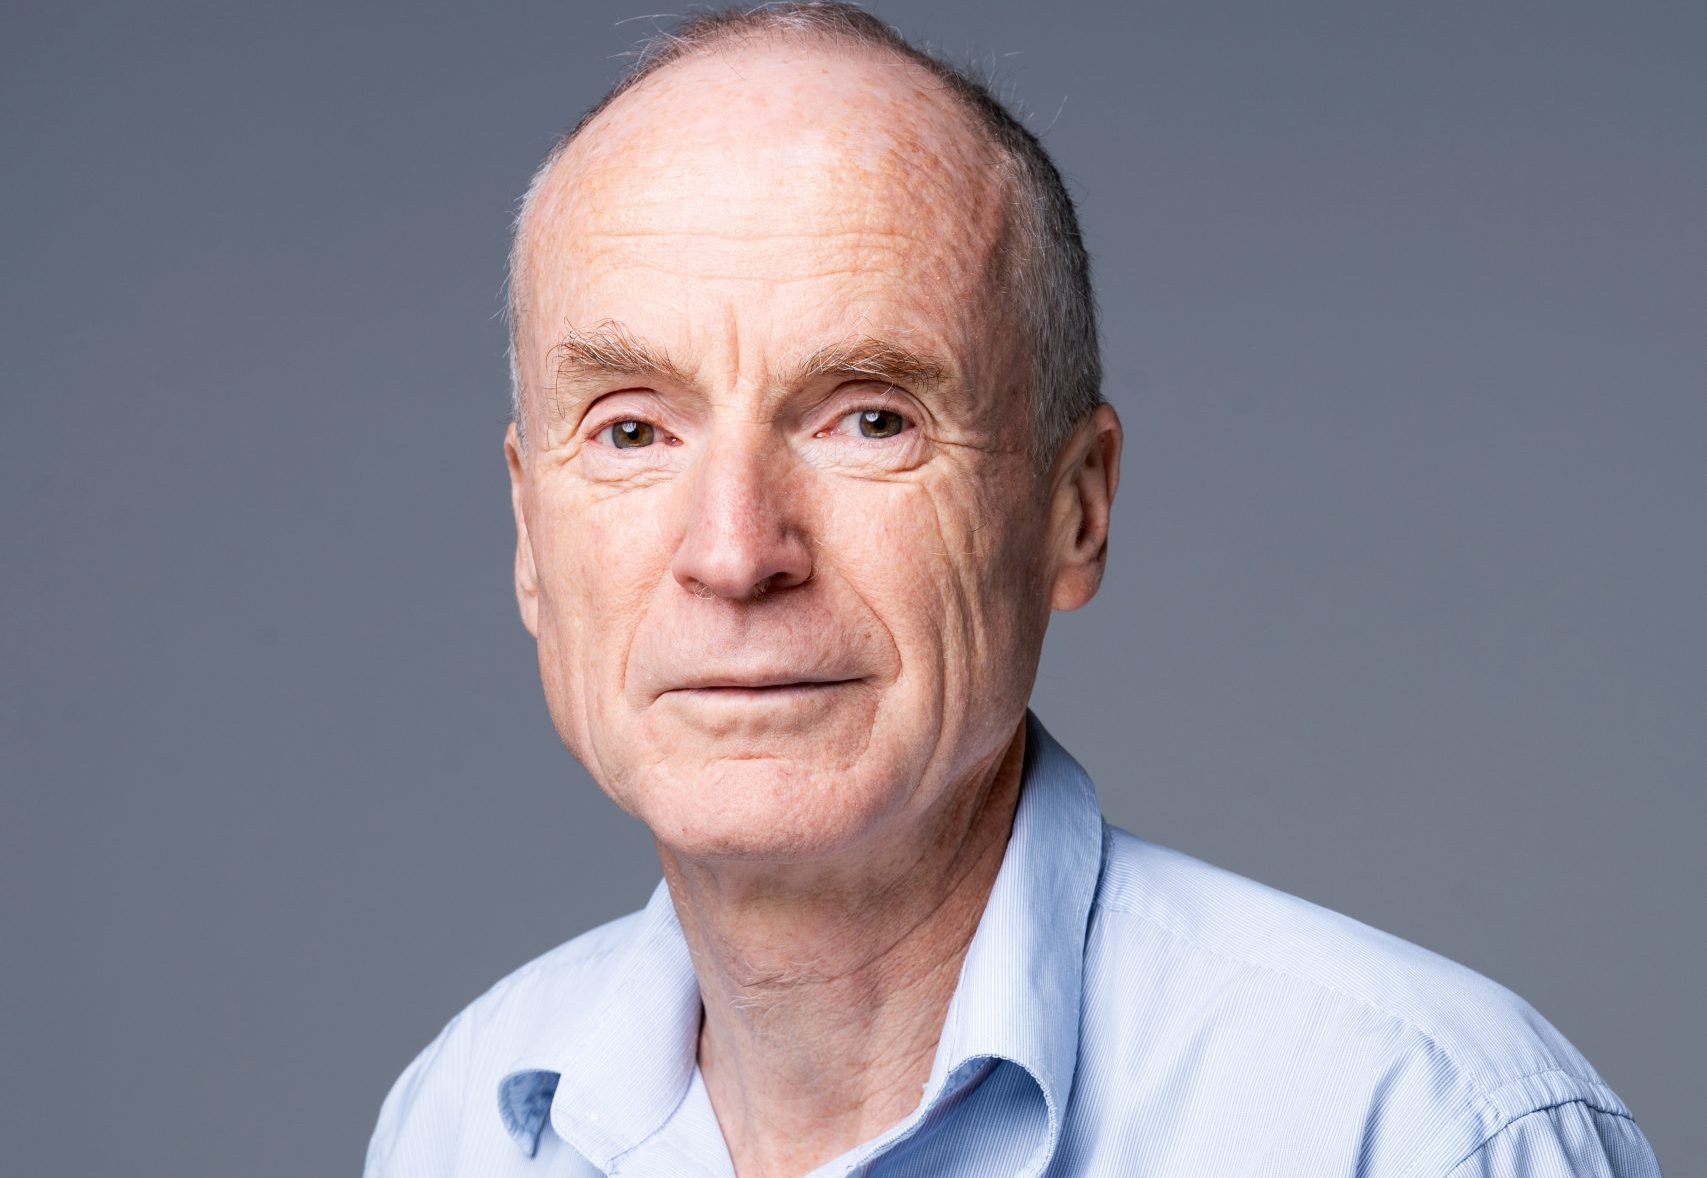
He may have invested a lifetime building a franchise juggernaut that is reportedly a $1 billion a year empire, but Jim Penman insists he’s a frugal guy who prefers to spend time planting a tree in his garden than contemplating his wealth.
What started out as Jim’s Mowing back in 1989 became Jim’s Group. Today, there are 5,700 franchisees across Australia and New Zealand in the business that has become ubiquitous for being the local handyman company that households could rely on.
He may have built a successful business empire, but the Melburnian insists he’s stingy when it comes to money.
“I wear my clothes even today until they wear out. I’ve always had a very lean and mean attitude. I live a simple life. My personal needs are very modest and my finances are simple,” he says. Jim reveals he’s usually in his garden these days and rarely eats out or takes holidays.
He is also running for state politics in the November Victorian election.
“I’m not particularly money focused. I could tweak the franchise contract to put more fees in and double my profitability, but that’s not my goal or my aim. To be honest, I often make decisions that go against my financial self-interest,” he says.
Jim purchased his first brand new car three years ago, opting for an electric Volvo.
“Being rich is not my aim and it never has been. People think I’m a lot richer than I am. They think I’m a billionaire, which is kind of ridiculous,” he says.
In fact, he insists he carries debt, which is common for anyone in business. “If I wanted, I could pay it off in 18 months.”
While his competitors were spending on fancy office space, Penman was running his franchise from his basement, keeping business costs low. “When I started out, I didn’t have any concept of how big this business could be. But there has never been a plan to grow franchisee numbers.
“Our attrition rate is far more important, and how to reduce complaint rates and drive more enquiries through new software.”
He believes people these days worry too much about impressing others, which leads to spending on superficial things.
“I would rather than offer people advice on how to be happy, rather than how to become rich. It’s important to have a good income so you can support yourself. But life is more about purpose.”
Jim doesn’t bother with stocks or bonds. He only invests in his own business. “My rate of return on my business is substantial. I could buy back a regional franchise when they come on the market and get a 20-25 per cent annual rate of return, plus capital gains. There’s nothing like that available in the investment space.”
Nicola Beswick: Founder, White Rabbit Advisory
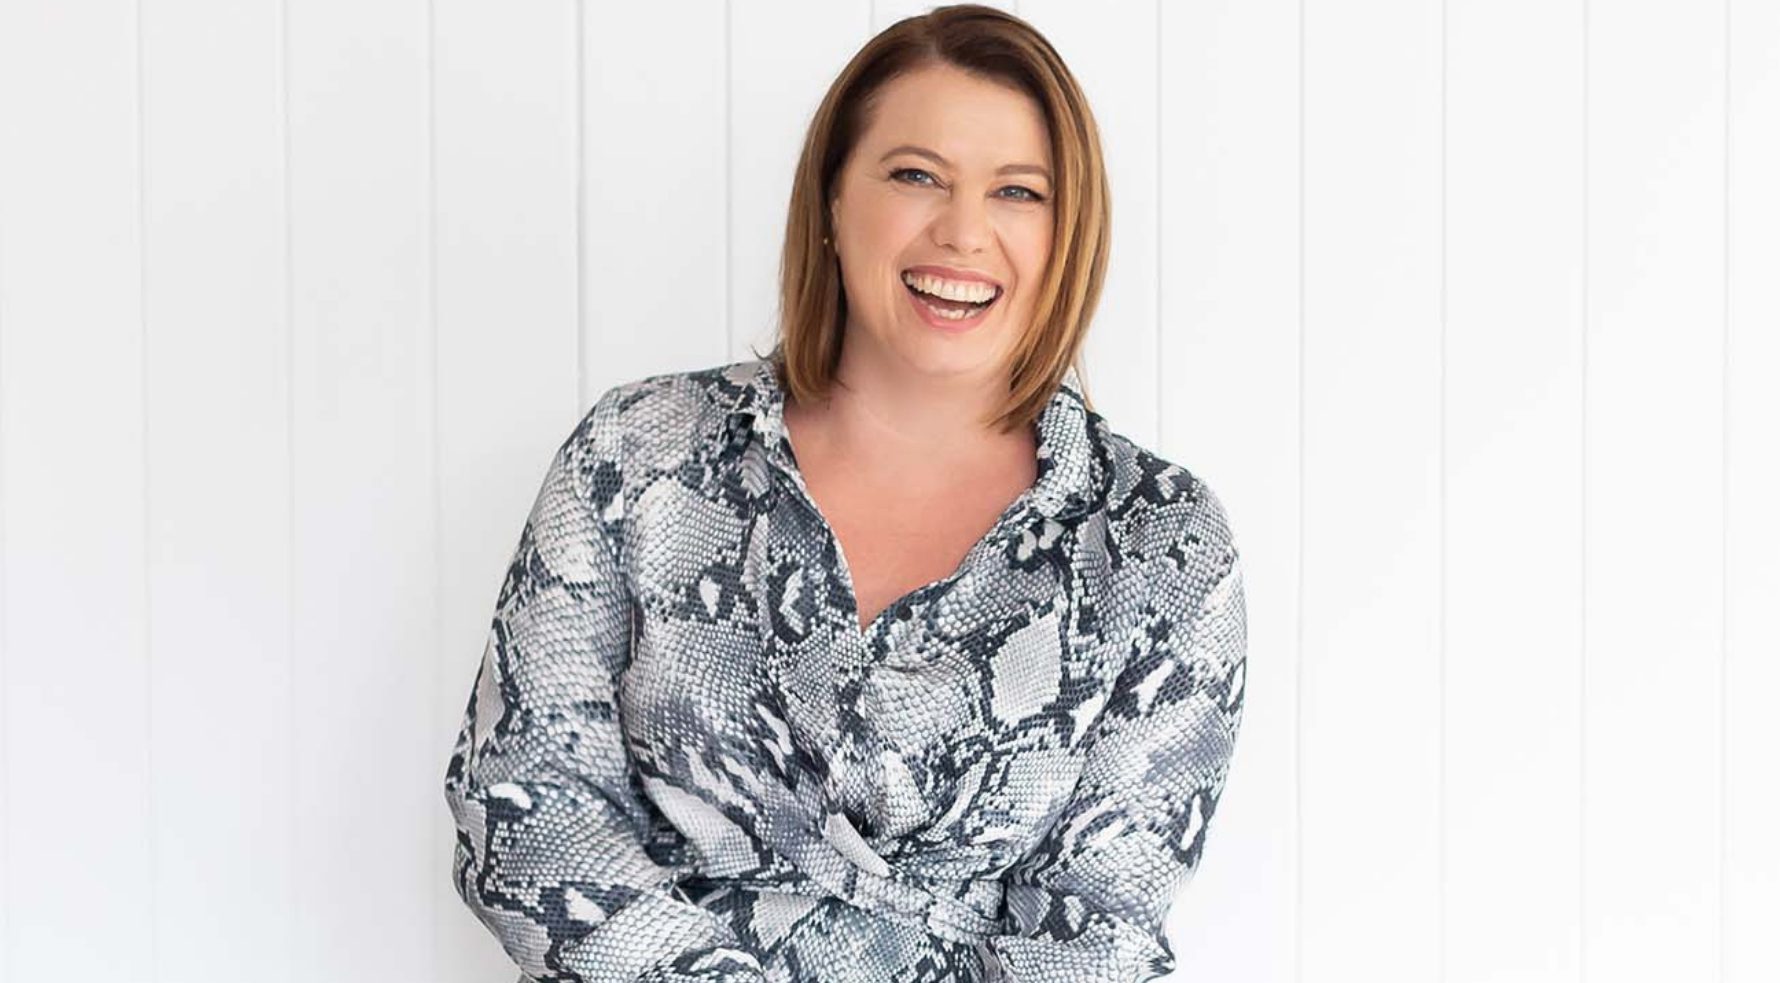
Rabbit Advisory founder.
A clothing allowance provided by her parents and then a part-time job during high school was the first taste of financial freedom for Nicola Beswick.
She quickly became a spender rather than saver, but she’s changed her tune over the years.
The founder of financial advice firm White Rabbit Advisory left behind a successful career in intellectual property law a year ago to become a financial adviser because she realised the potential that financial education could have on someone’s life.
Her journey began after coming across the book Rich Dad Poor Dad some years ago, which opened her eyes to the power that money could have on her life. This marked a time when she became serious about her finances.
“Financial education and investing over time can have a huge impact on a person, and that book got me thinking about money and financial education in the first place,” she says.
Nicola says years ago, her father was diagnosed with multiple sclerosis. When dealing with the devastating news and an uncertain future, her father discovered he was eligible to receive an income protection payout.
“This was the stone that rippled his pond and mine. A new complex world of finance opened up and I discovered my calling – helping people plan for a financially secure future.”
She hasn’t looked back. “Commercial law was very transactional. I don’t regret quitting at all. I’m much happier now helping people get their finances in order. Financial planning helps people change their lives. That was a really big driver for me.”
The Melburnian admits she’s learned plenty of lessons along the way as she embarks on the process of building wealth. She uses superannuation as an investment vehicle, favouring its tax advantages.
“I also built a nest egg outside of super, because you never know when the rules will change,” she says.
She prefers to set a financial goal and save up for something specific over time than rush out and make a purchase.
“It’s a really powerful thing to wait before making a purchase,” she says.
Her current financial goals involve renovating her heritage-listed home. “We will keep the façade and gut it to rebuild. That’s a major expense for us on the horizon.”
While holidays are rare, she will spend on overseas trips on occasion. “I’m terrible at taking time off. I’m always working.”
Sam Riley: CEO, Drova
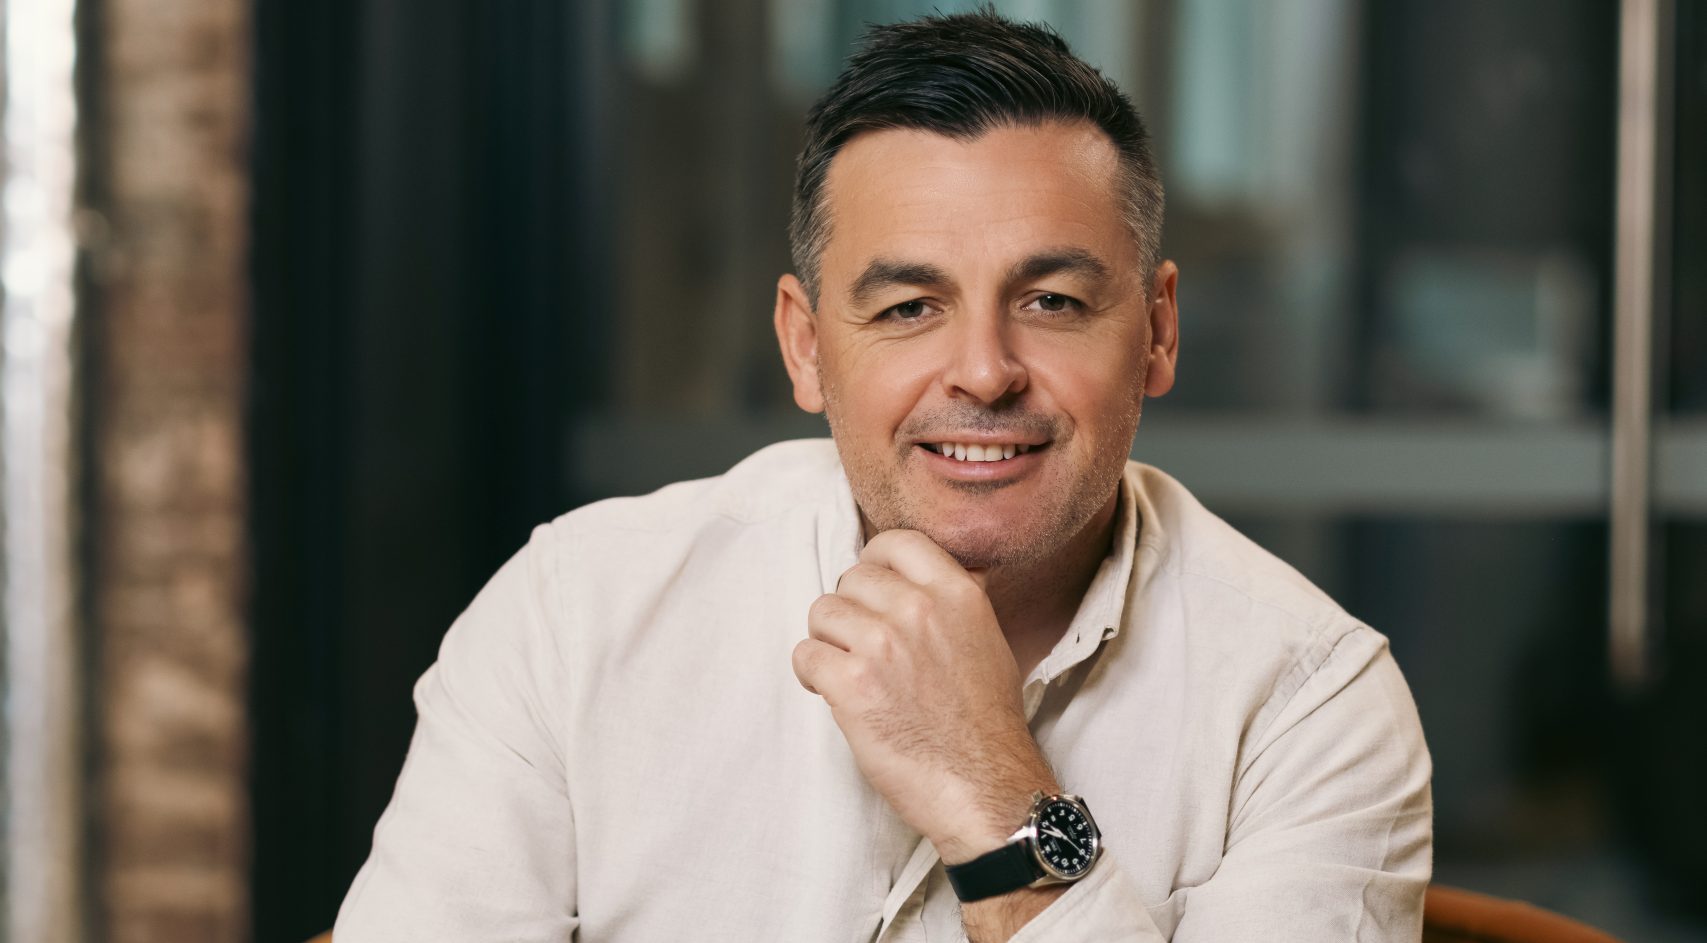
Sam Riley was in his 20s when he set out to amass enough money to be able to retire by the age of 40 if he wanted to.
“The goal was always to be doing something by 40 that kept me engaged enough that I didn’t actually want to retire because I was happy,” he says.
An entrepreneur at heart, Sam started a juice and espresso bar when he was 21, which didn’t work out. His next venture was a technology business, Ansarada, an ASX-listed company he ultimately sold nearly two years ago for $250 million.
The sale set him up for life, but he’s not one to rest on his laurels, launching into the complex world of artificial ntelligence with his next technology play, a company called Drova.
The technology startup simplifies risk, compliance and resilience for small businesses. Sam believes it’s got potential to become a tech juggernaut in time.
Having early financial success has meant he has the luxury of slow mornings and working in short bursts throughout the day, problem solving, experimenting with what works and figuring out how to harness AI.
“I favour a more sustainable approach to working these days. More frequent breaks. Making sure not to deteriorate my capacity,” he says.
It was a hard slog. He admits he touched the fringes of serious burnout when he was younger, which he works hard to avoid these days.
“Every business venture has exposed a gap in my skills that I’ve worked to close. Whether that’s marketing or managing people, closing those gaps along the way is how you get more effective at generating wealth,” he says.
The secret to his success has been finding ways to bolster value in the corporate world, finding ways to bring more to the table. Sam admits he spends too much money on travel, food and niche vinyl audio equipment, like turntables. He prefers to invest in experiences rather than things.
But it can get expensive. Like a recent trip to Antarctica to stay in a lodge for a week. “The thing is I didn’t like having these experiences on my own, so I have to bring family or other people and then pay for them.”
Sam describes his investment portfolio as balanced. While he continues to invest in entrepreneurial ventures, he admits he has a safe foundational platform to his investment approach.
“Over the years, I’ve added a lot more dividend stocks and protective assets like gold and silver, and some index funds.
“When I was younger, I didn’t appreciate the value of being safe and boring in the investment world.”
He says a lot of his investments used to be leading edge and visionary. “Some of them work, and some of them don’t. I didn’t really have much balance in my portfolio. I still invest in entrepreneurial things, but am much more conscious of taking a more even-handed approach,” he says.
his article appeared in the Winter 26 issue of Kanebridge Quarterly, which you can buy here.
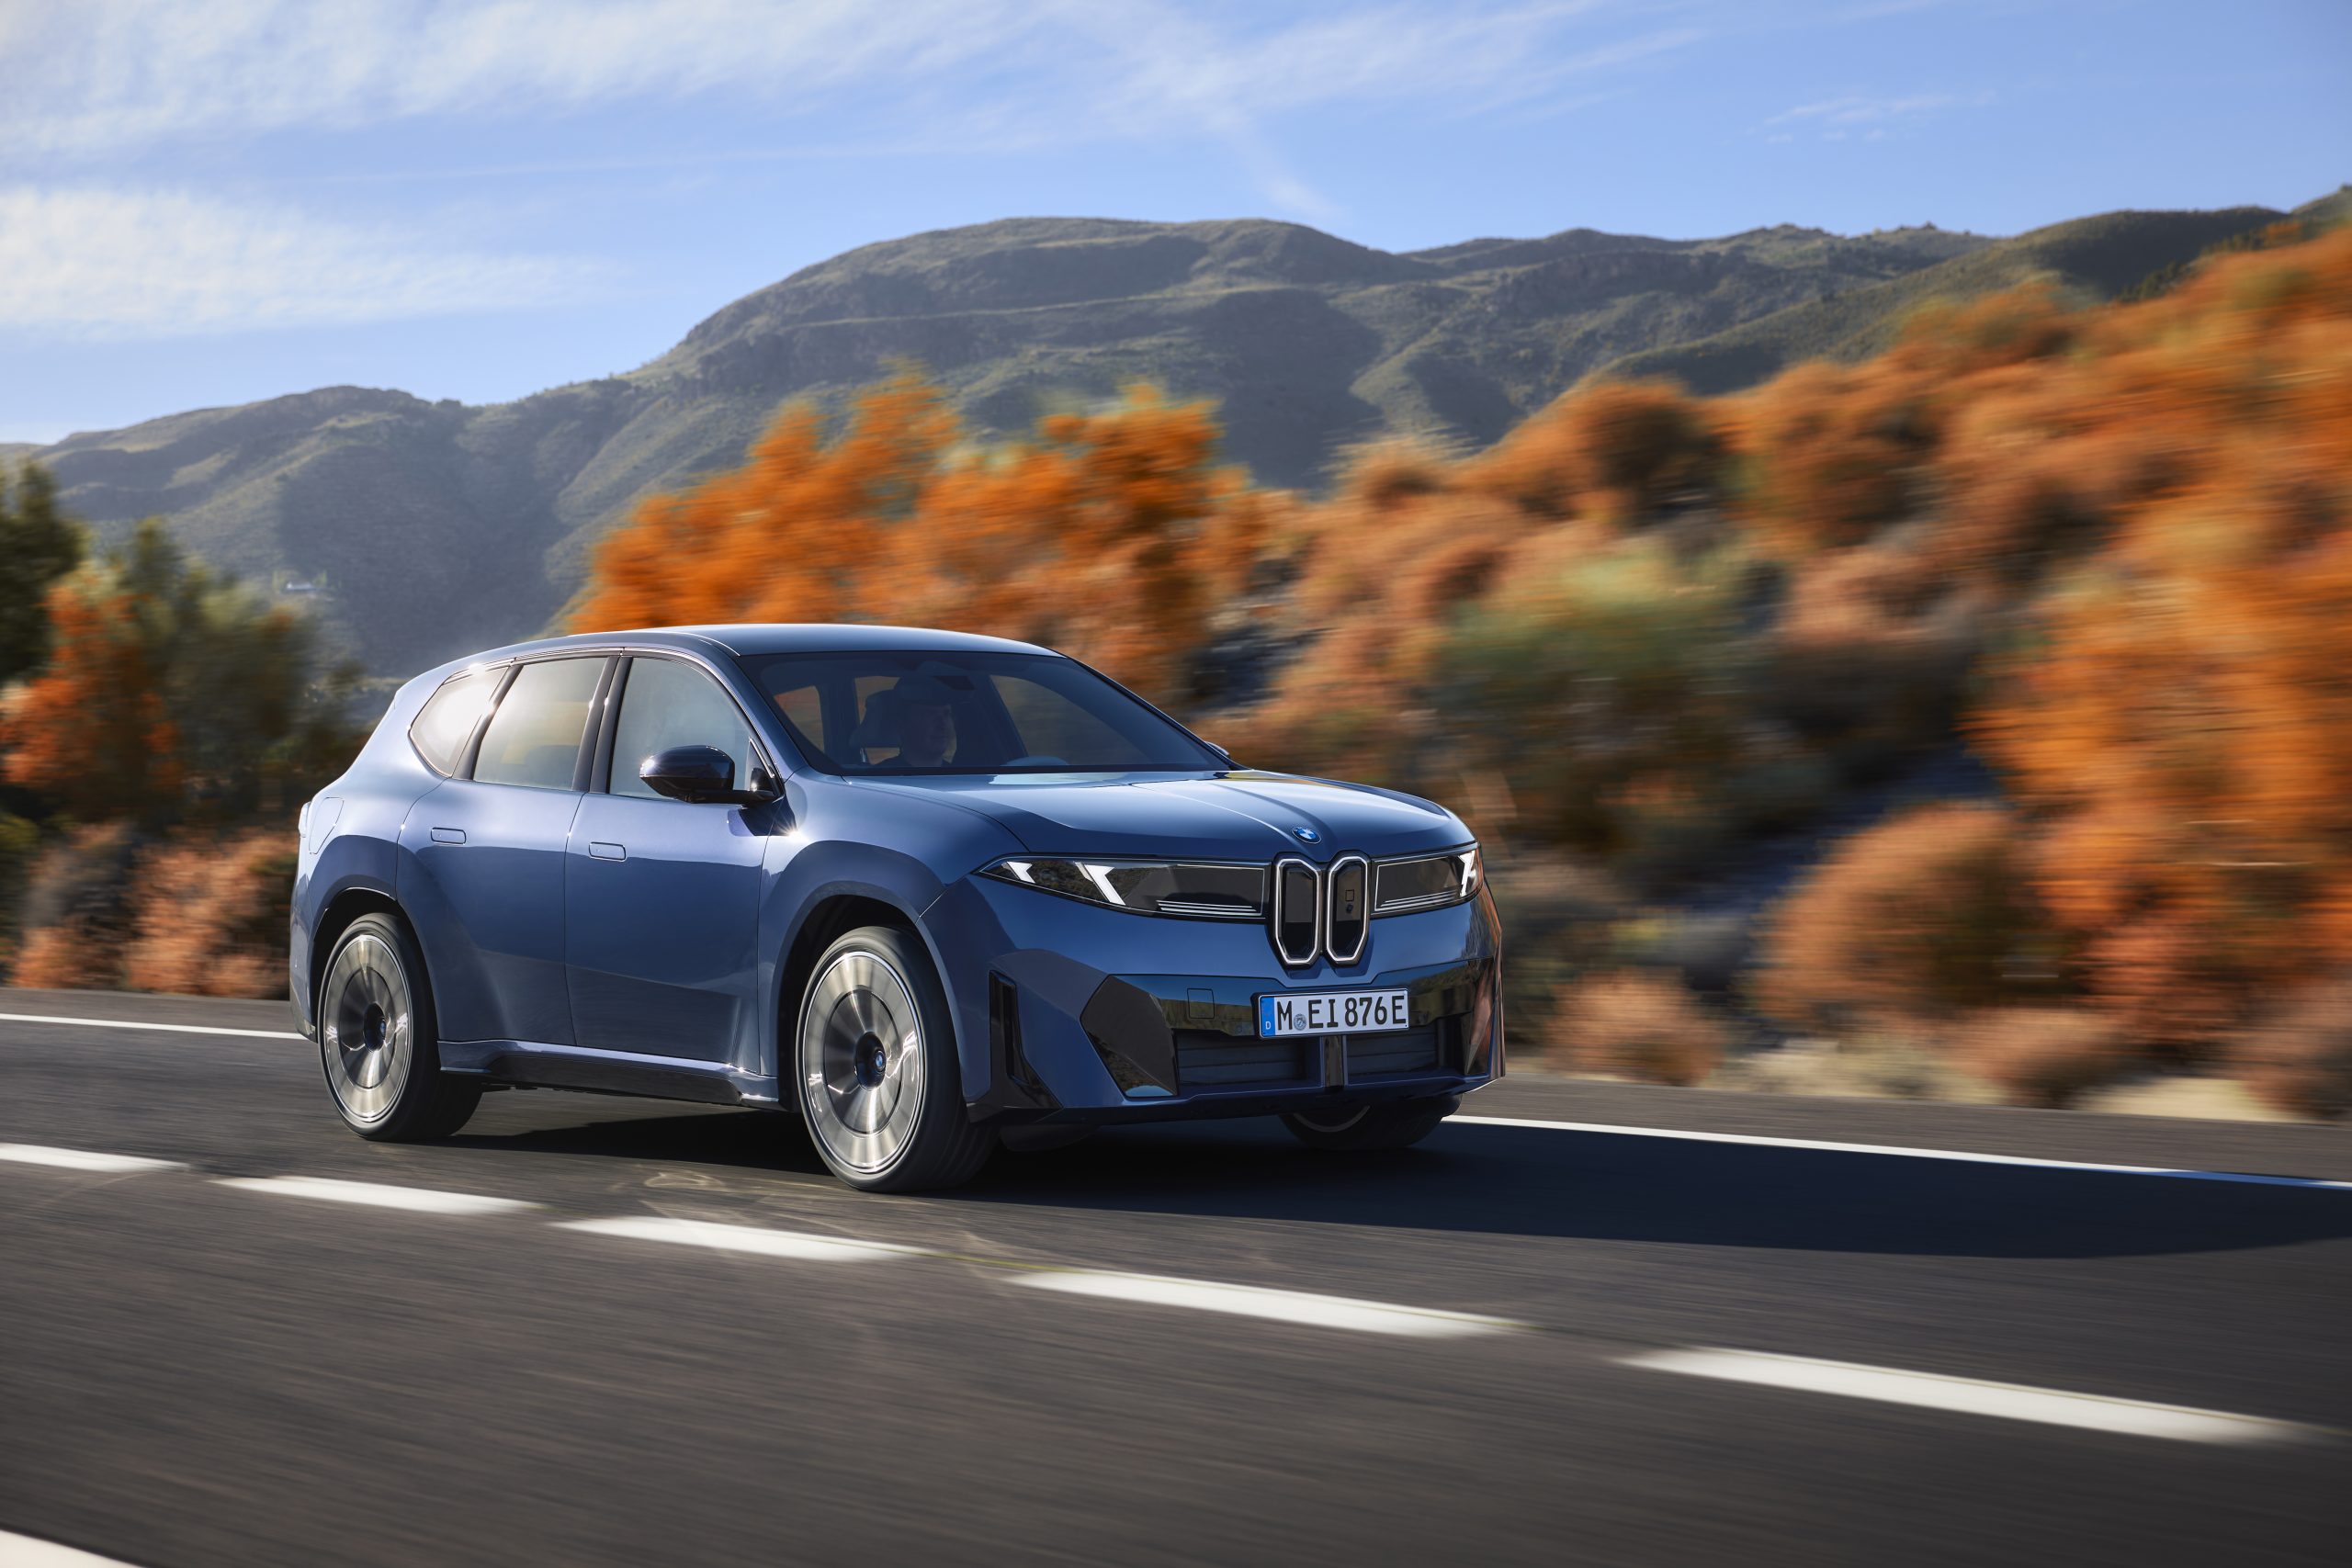
BMW has unveiled the Neue Klasse in Munich, marking its biggest investment to date and a new era of electrification, digitalisation and sustainable design.

French luxury-goods giant’s results are a sign that shoppers weren’t splurging on its collections of high-end garments in the run-up to the holiday season.