

Higher Rates Are Biting — But the RBA Says Most Borrowers Are Still Holding Up
The RBA says most Australian borrowers remain resilient, but around 2 per cent of variable-rate owner-occupiers face a cash-flow shortfall.
 3 min
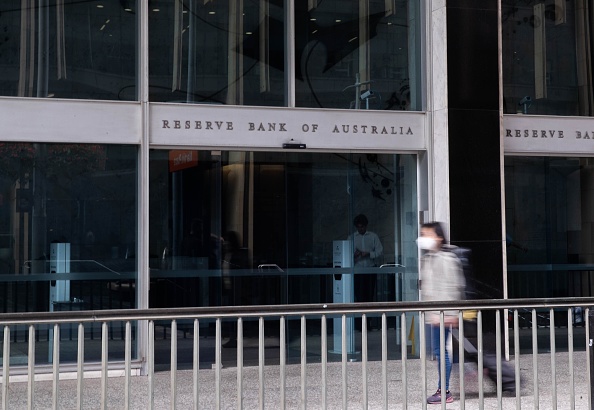
The Reserve Bank’s October stability review finds that most borrowers remain resilient, even as a small but important group experiences cash-flow shortfalls and investor activity remains a source of potential market amplification.
Australian borrowers have absorbed higher interest rates better than many feared, but the averages conceal a small group under genuine pressure.
The Reserve Bank’s October 2026 Financial Stability Review estimates that around 2 per cent of variable-rate owner-occupier borrowers are experiencing a cash-flow shortfall — meaning essential spending and scheduled mortgage payments exceed income. That is a minority, yet in a mortgage market containing millions of loans it is not insignificant.
The broader picture is more resilient. Most mortgagors continue to service their debts, helped by strong employment, income growth, savings buffers and the capacity to reduce discretionary spending. Many households also entered the tightening cycle with substantial equity, limiting the risk that a forced sale would leave debt outstanding after the property changed hands.
For owner-occupiers, the report reinforces the difference between repayment discomfort and insolvency. A household may feel materially poorer after a rate increase without being unable to pay. The danger rises when several stresses arrive together: reduced working hours, illness, separation, expiring interest-only terms or a major unexpected expense.
That is why borrowers should focus on liquidity, not only equity. A home can be worth considerably more than its mortgage while the owner still struggles to meet this month’s repayment. An offset balance or accessible savings buffer can therefore matter more in the short term than a strong paper gain.
Investors face a different calculation. The RBA notes that investor housing activity can amplify property-price cycles because investors may respond more quickly than owner-occupiers to changing expected returns. Rising rates increase holding costs, while rent, vacancy, maintenance, land tax and insurance determine whether an asset remains cash-flow sustainable.
Investor lending has moderated from elevated levels, although it remains an area watched by regulators. APRA’s June-quarter data showed investment loans represented 31.2 per cent of outstanding residential mortgage credit and 35.6 per cent of new residential lending. It also showed that 8.9 per cent of new investor loans had a debt-to-income ratio of six times or more, compared with a lower share across new lending overall.
High debt-to-income lending is not automatically poor lending. A borrower may have substantial assets, reliable income or a clear deleveraging plan. But leverage leaves less room for error when rates rise or income weakens. Investors should stress-test repayments above the current rate, allow for periods without rent and budget for irregular capital expenses rather than treating gross rent as spendable income.
The RBA’s assessment does not amount to a forecast that mortgage stress will disappear. Financial stability can remain sound while individual households experience serious hardship. Borrowers who expect difficulty should contact their lender early; hardship arrangements are generally more effective before arrears compound.
For prospective buyers, the practical message is not to assume that system-wide resilience makes every loan safe. Purchase price, deposit, loan structure and cash reserves still determine personal risk. For investors, the discipline is sharper: evaluate the property on net cash flow, realistic rent and a conservative interest-rate assumption, not on the hope that capital growth will solve an overextended balance sheet.
Australia’s mortgage market is bending rather than breaking. The RBA’s two-per-cent estimate shows, however, that resilience is not evenly shared — and prudent borrowers should build their finances for the possibility that their own circumstances will not resemble the average.
Borrower dashboard
Variable-rate owner-occupiers in cash-flow shortfall: Around 2 per cent, RBA estimate
Total residential mortgage credit: $2.5585 trillion at June 2026, APRA
Investor share of outstanding residential credit: 31.2 per cent
Investor share of new residential lending: 35.6 per cent
New investor loans at DTI of six or more: 8.9 per cent
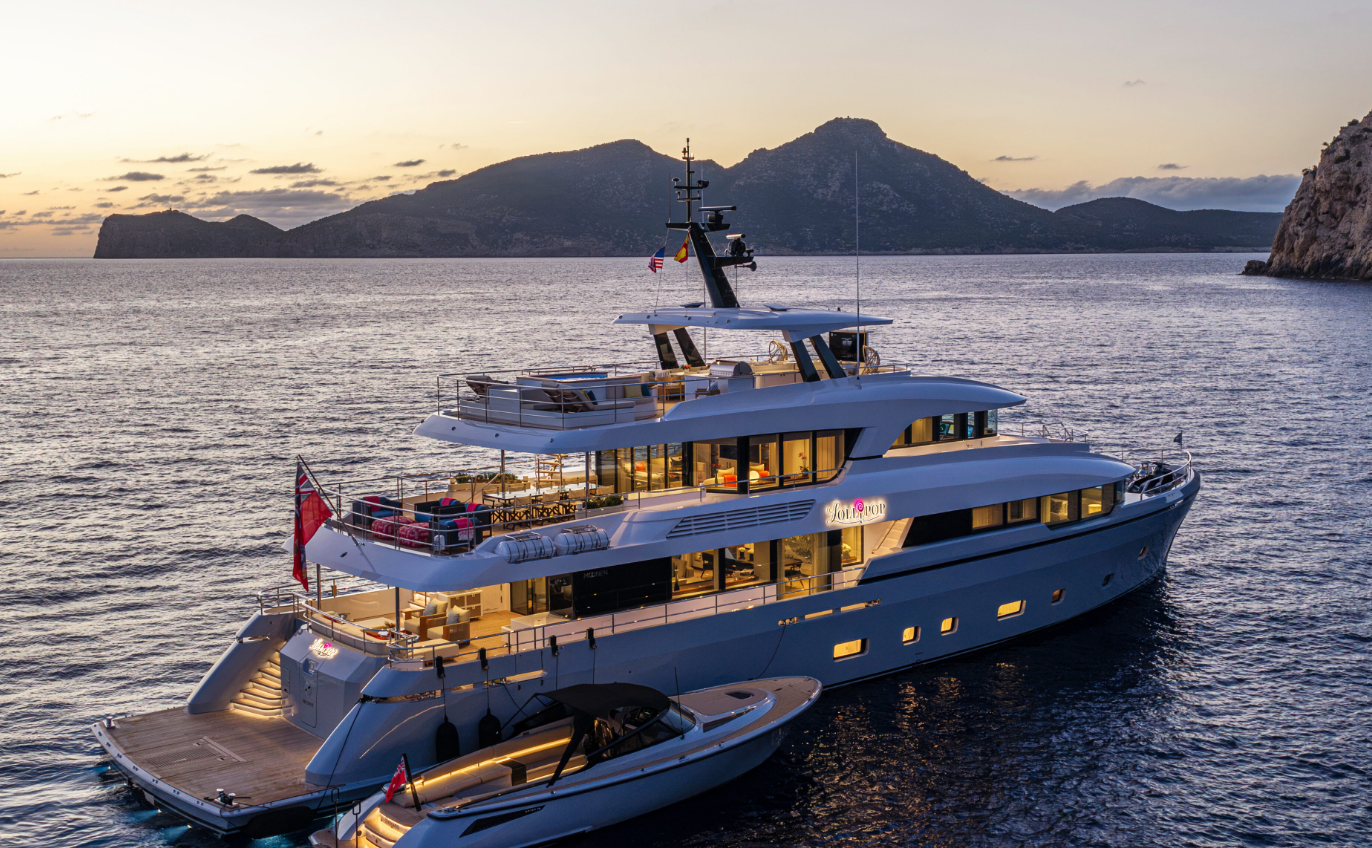
Dutch studio Vripack took cues from a Shirley Temple song for Lollipop, a 37.4-metre Moonen superyacht built for long-range cruising.
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
 2 min
Sydney had roughly 4,300 more vacant rentals in October than it did a year earlier, giving tenants a wider pool of properties to inspect. SQM Research counted 13,872 vacancies in the city, up about 45 per cent on October 2025. The vacancy rate held at 1.8 per cent, compared with 1.3 per cent a year earlier.
Melbourne’s vacancy rate rose to 2 per cent, the highest of any capital, with 10,833 properties available. Together, Sydney and Melbourne accounted for more than half the 44,275 vacancies SQM recorded nationally. The national rate edged up to 1.5 per cent, from 1.4 per cent in September and 1.2 per cent a year earlier. SQM’s measure counts online rental listings that have been advertised for at least three weeks.
That three-week threshold matters. A rental let quickly can come and go without entering the count. A bigger pool of listings that have been advertised for at least three weeks suggests more properties are taking longer to lease. SQM noted that Melbourne’s rise in vacancies came as asking rents softened across houses and units during spring, when rents would usually pick up.
Sydney’s house and unit rents are moving in different directions
Sydney unit asking rents fell 0.7 per cent over the 30 days to 12 November, to about $744 a week. House asking rents rose 1.6 per cent to about $1,175. In Melbourne, both fell for a second consecutive month, with units down 1.6 per cent and houses down 0.4 per cent. Melbourne’s combined asking rent was still 5.7 per cent higher than a year earlier.
The Sydney figures put the weekly gap between house and unit asking rents at about $431. The averages cover different properties across the city, but the size of the gap helps explain why a household looking for an extra bedroom or outdoor space may experience a tighter market than someone looking for a unit.
Smaller capitals are still tight
Perth and Adelaide both recorded vacancy rates of 0.6 per cent, while Hobart had the lowest capital-city rate at 0.4 per cent. Brisbane moved up to 1 per cent, the same as a year earlier, and its combined asking rents were still 7.1 per cent higher over the year. Canberra, at 1.9 per cent, was closer to Melbourne and Sydney on availability. Darwin recorded a monthly fall in advertised rents, yet annual growth there was still 11.8 per cent.
A separate Cotality review puts the recent easing in perspective. Its national series recorded rental growth of 0.5 per cent in the September quarter, down from 1.6 per cent in June and 2.1 per cent in March. Even after that slowdown, Cotality estimated national unit rents were $208 a week higher than five years earlier, while house rents had risen $195 a week.
On SQM’s measure, national advertised rents were still 6.4 per cent higher than a year ago. The clearest signs of relief are in Melbourne and in Sydney’s apartment market, where asking rents have eased as more rentals have become available. For renters looking for a detached house in Sydney, the latest figures still point to rising asking prices.

A 30-metre masterpiece unveiled in Monaco brings Lamborghini’s supercar drama to the high seas, powered by 7,600 horsepower and unmistakable Italian design.

French luxury-goods giant’s results are a sign that shoppers weren’t splurging on its collections of high-end garments in the run-up to the holiday season.