Residential real estate tops $10 trillion as Australians bank on bricks and mortar
Property remains the investment of choice for most Australians
 2 min
The old adage ‘safe as houses’ has been given a shot in the arm with news that the value of Australia’s residential real estate has topped $10 trillion.
According to CoreLogic’s Monthly Housing Chart, it’s the first time national home values have hit double figures since June 2022 and places real estate as the top source of wealth for Australians.
The value of residential real estate exceeded superannuation on $3.5 trillion and listed stocks on $2.9 trillion. The commercial real estate market comes in fourth, worth $1.3 trillion.
In a volatile global economy, it’s clear that most Australians still prefer to invest in bricks and mortar with figures showing 56.3 percent of household wealth is tied up in housing.
While overall housing values in capital cities and regional centres were a mixed bag over the past 12 months to August, with the exception of Hobart, all the capital cities saw consistent growth in values over the past quarter.
Head of research at CoreLogic, Eliza Owen, said a lack of supply, net overseas migration and buyers drawing down savings, equity or profits from previous properties were all contributing factors to the steady increase in values over the past three months.
Whether this level of growth will continue, however, is uncertain.
“While there is a growing expectation that the RBA board is done hiking the cash rate, borrowing remains constrained by a relatively high serviceability buffer,” Ms Owen said. “APRA data to June showed the weighted average home loan assessment rate was just below 9 percent, and ABS housing lending data shows mortgage lending has fallen for three of the past four months.
“Economic performance is also set to unwind, and while this is good news for the inflation and cash rate trajectory, a rise in unemployment may create a higher degree of risk for mortgage serviceability.”
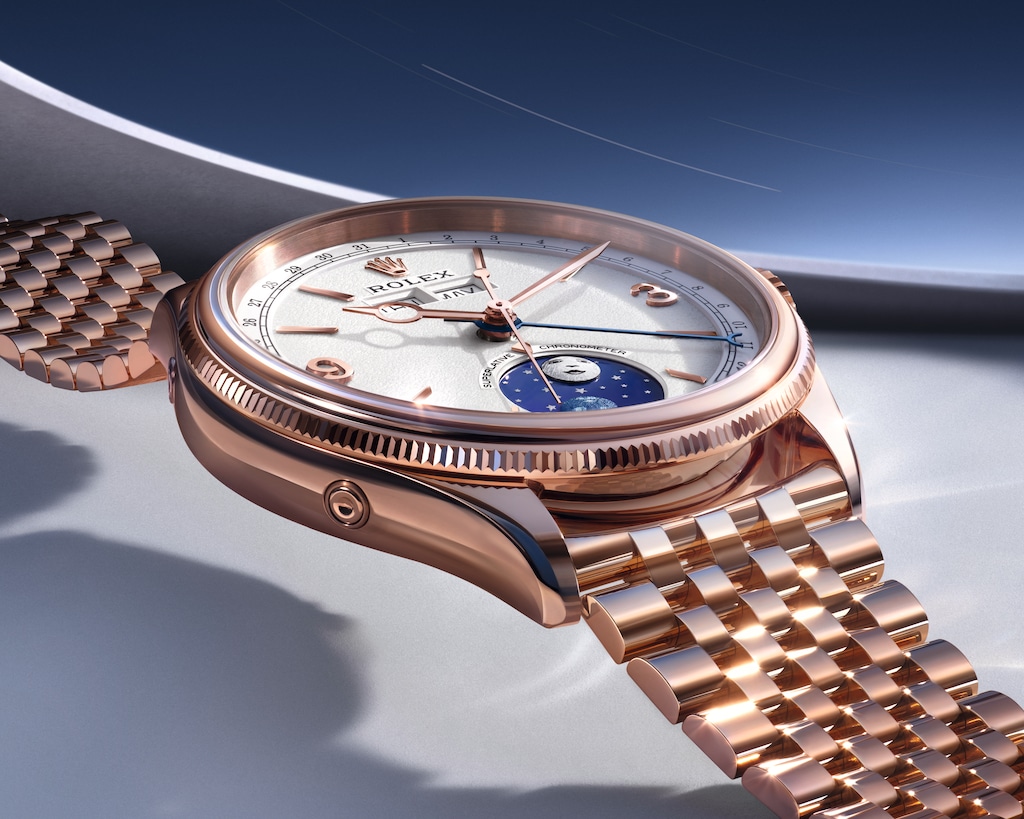
The Perpetual Padellone draws its name from the coveted reference 8171 while introducing an instantaneous complete annual calendar to Rolex’s modern Perpetual collection.
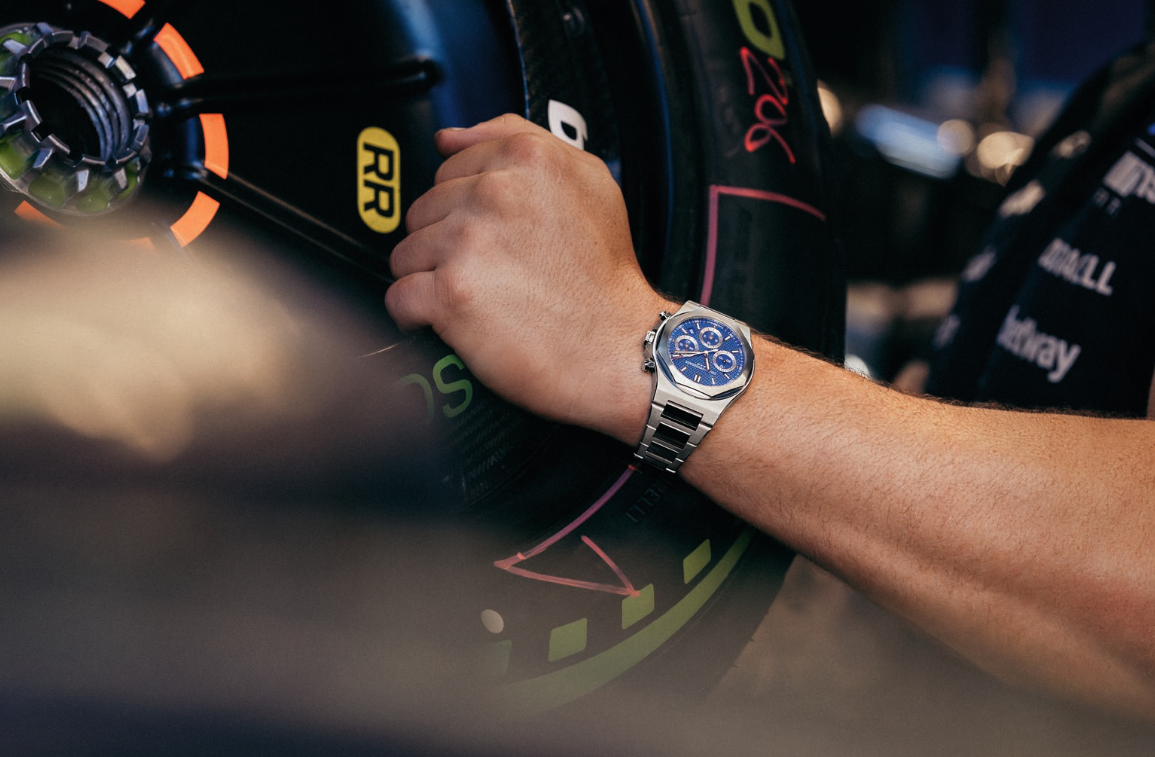
The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
Australia’s housing challenge is increasingly about conversion: moving approved projects through finance, commencement and completion.
2 min
Australia’s housing debate often treats a development approval as though it were a completed home. In practice, the distance between those two milestones can stretch for years—and a growing number of projects never cross it.
The National Housing Supply and Affordability Council reported in August that approximately 308,000 homes had been completed since the Housing Accord period began, roughly one quarter of the national target. It also identified 244,000 dwellings under construction in the March quarter, the largest pipeline recorded since 1984, while approvals and commencements had improved against their pre-Accord comparisons.
Those numbers show activity, but they also expose the conversion challenge. A planning consent establishes what may be built. It does not lock in the price of labour and materials, guarantee a construction loan or persuade enough buyers to sign unconditional contracts.
For apartment developers, the first hurdle is feasibility. Land, consultant, authority, finance and construction costs must be covered by realistic sales revenue. When building prices rise faster than achievable apartment values, a project can be approved and still be economically unbuildable.
The second hurdle is debt. Financiers typically require substantial equity, a fixed or sufficiently certain building contract and presales to acceptable purchasers. Valuers may discount speculative pricing, while lenders can treat contracts with long settlement periods or highly concentrated buyer profiles cautiously.
Presales form the third constraint. Owner-occupiers may prefer to see construction under way before committing; developers often need commitments before construction can begin. This circular dependency is particularly difficult for first-time developers and projects in untested locations.
The practical metric for policymakers and the industry is therefore not approvals in isolation, but conversion: how many approved dwellings progress to finance, commencement and completion, and how long each step takes.
There are no simple fixes. Faster planning can reduce holding costs, but cannot rescue an unviable scheme. Government-backed finance can help suitable projects, but should not disguise unrealistic land values. Standardised design and modern construction methods may improve productivity, provided procurement risk and quality control are addressed.
For buyers, an approval or sales launch should be viewed as the start of the delivery process—not proof that a home will exist on schedule. The most relevant questions concern finance, builder appointment, sunset provisions, deposits and the developer’s record of completing comparable projects.
Australia has made progress in filling the front end of the housing pipeline. The next challenge is getting those homes out the other end.

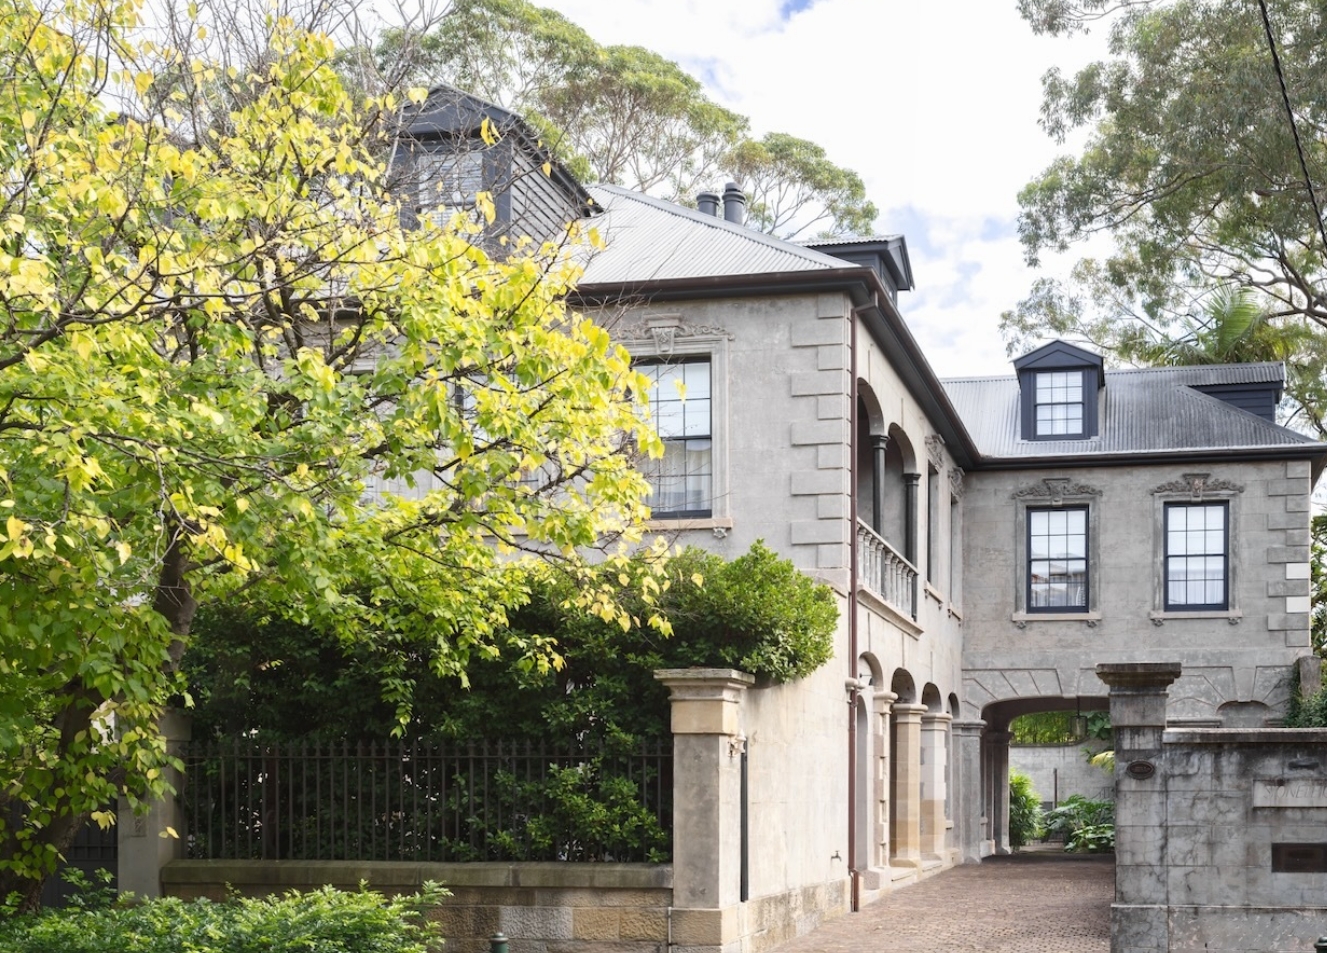
Wealthy Aussies are swapping large family homes for high-end apartments, with sales of prestige units tripling over the past decade.
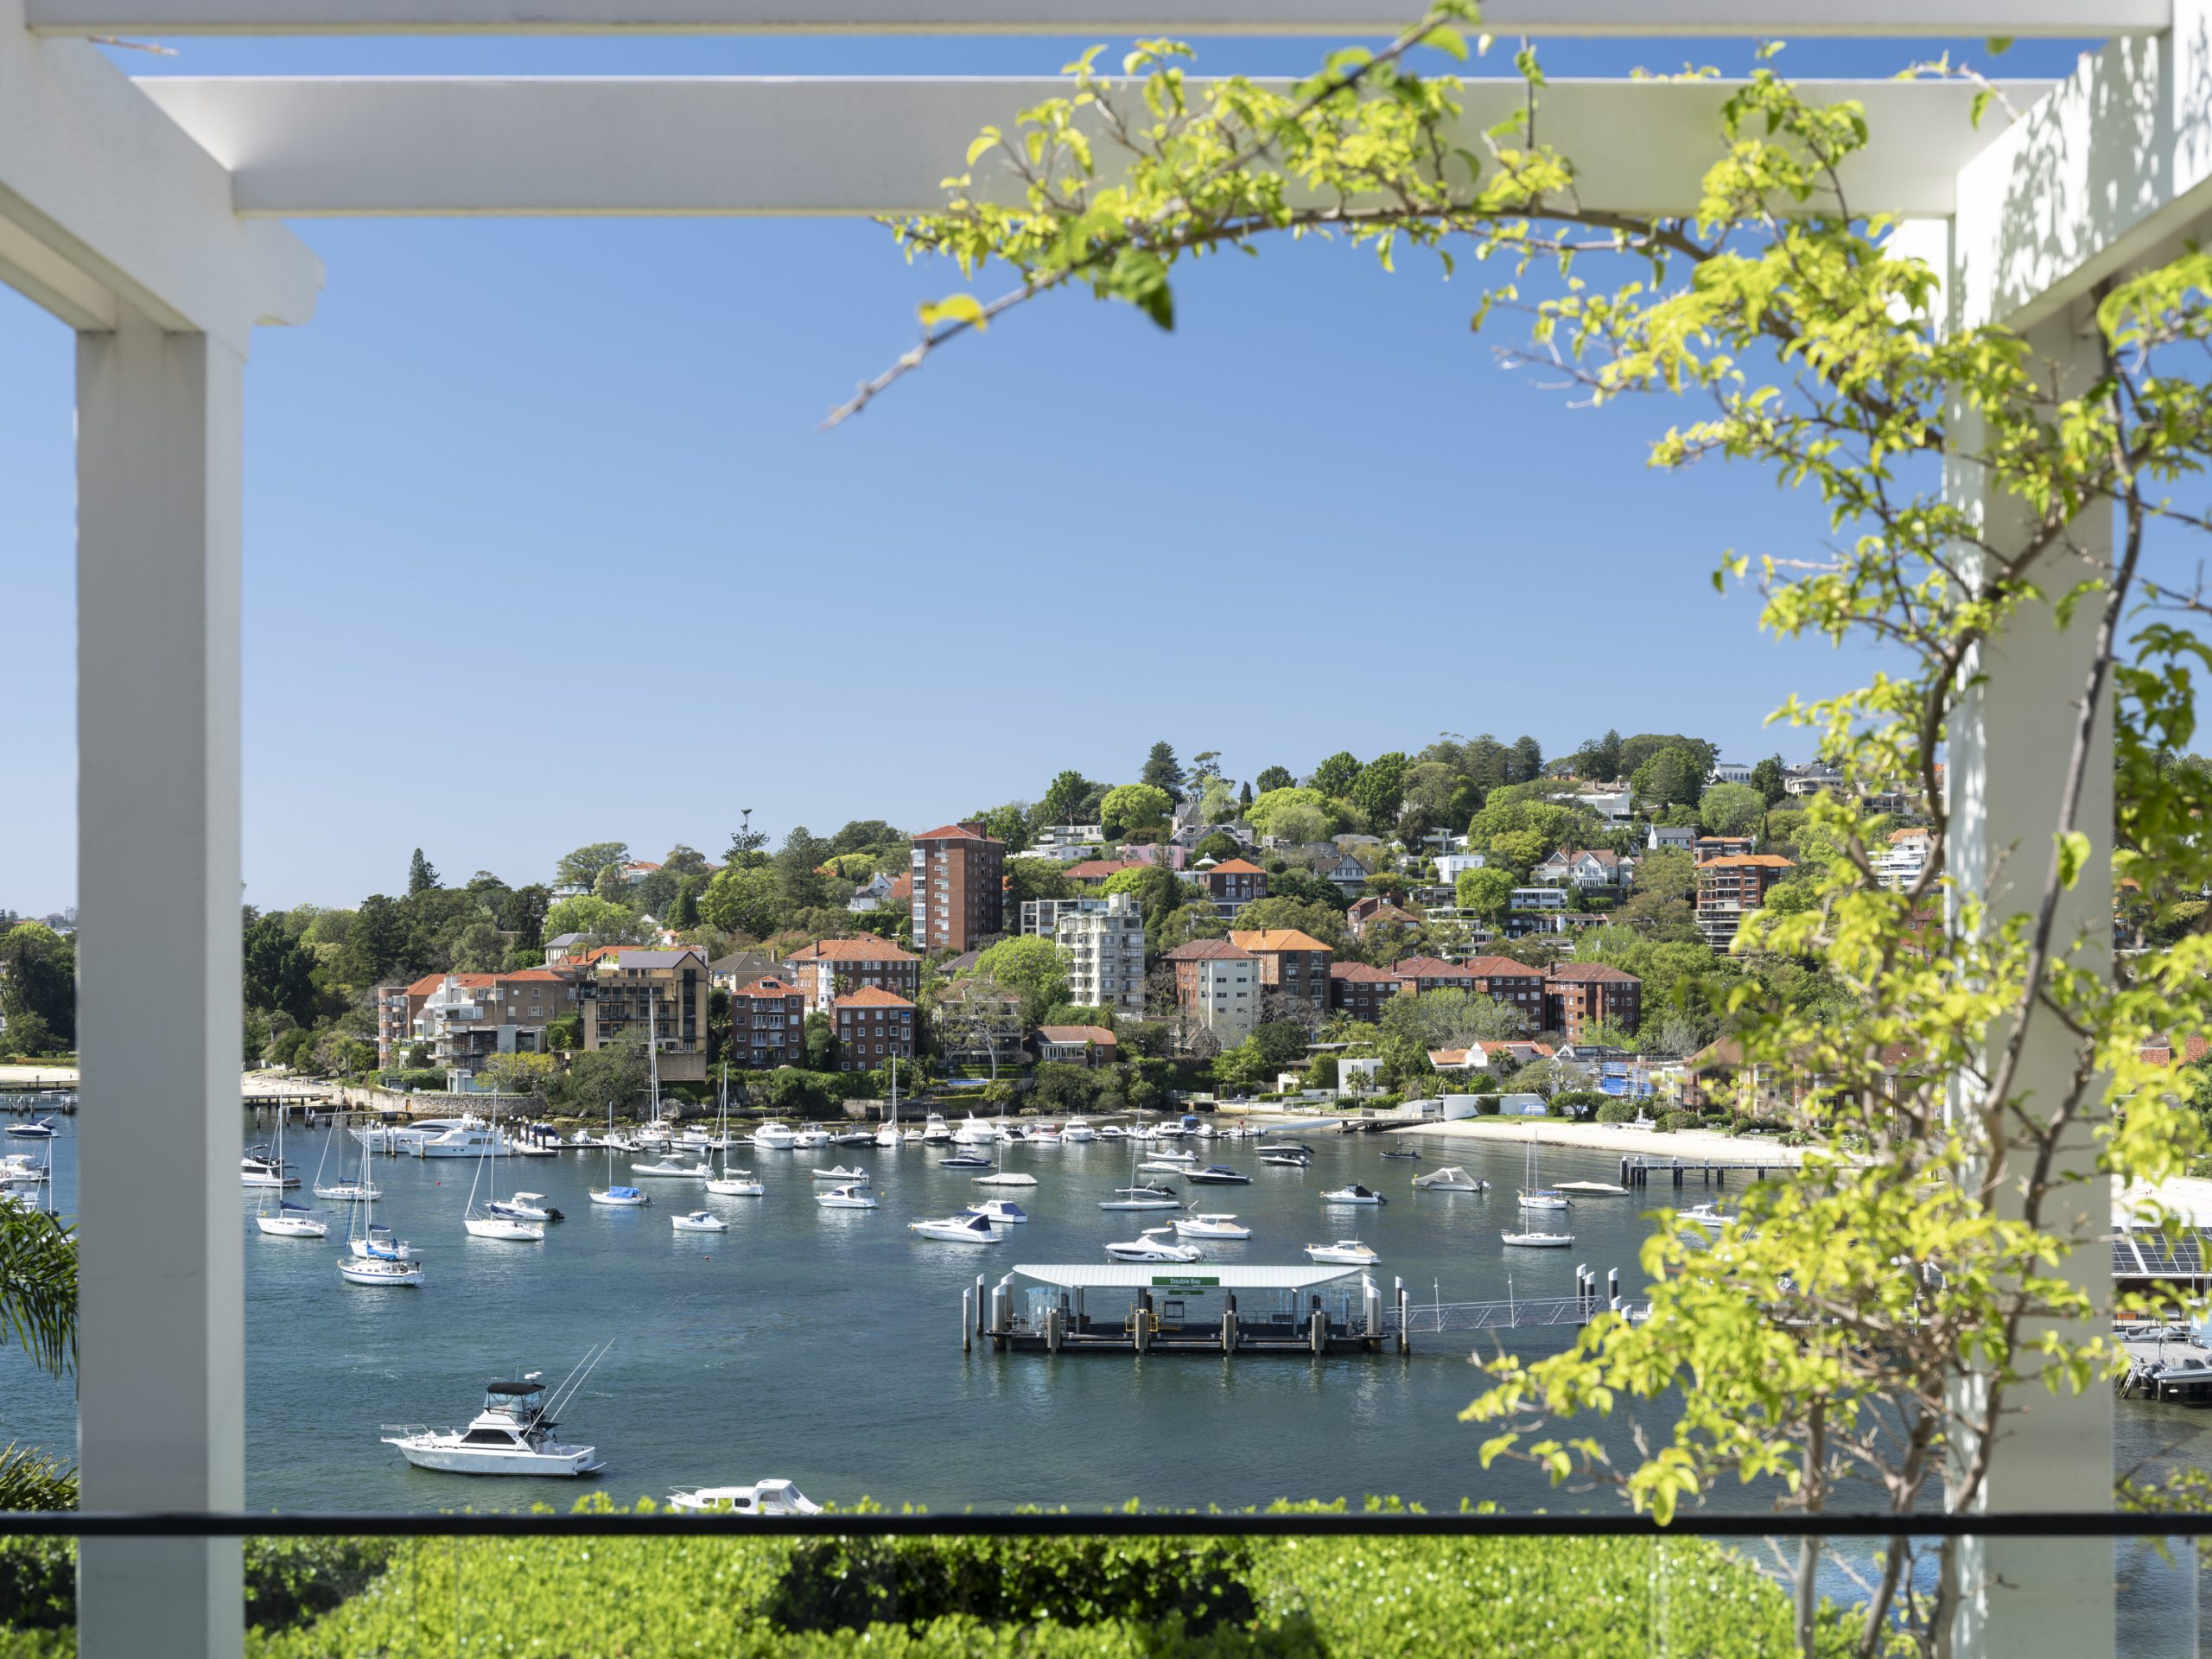
The grand harbourside residence combines sweeping Sydney Heads views, resort-style entertaining and refined designer finishes with a reported $36 million price guide.