Scammers Tried to Sell Graceland. How to Prevent Your Home From Being Next.
Even if you don’t lose your property, title fraud can have real consequences

 4 min
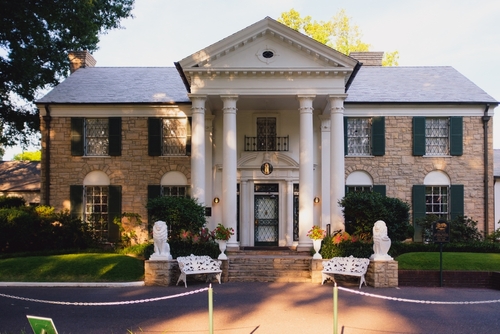
When a company tried in May to auction off Graceland, the iconic former home of music legend Elvis Presley in Memphis, a Tennessee court stepped in to stop it.
The court stopped the sale because the company that was trying to auction off the property was fake. Also fraudulent were the supporting documents the fraudsters presented that purported to show that Lisa Marie Presley, Elvis’s late daughter, had defaulted on a loan they claimed they made to her for which she used Graceland as collateral.
While this audacious and complex attempt at defrauding a famous family made national news, most other cases of attempted title theft or mortgage fraud don’t. But homes such as Graceland, where the original owners are deceased, are popular targets for scammers, according to Victor Petrescu, a real-estate attorney with Levine Kellogg Lehman Schneider & Grossman in Miami.
Homes with out-of-state owners, vacant plots of land and investment properties owned by limited liability companies are also particularly vulnerable, he said.
Here’s how it works: A fraudster targets your house and assumes your identity, using tactics similar to identity thieves to acquire your personal information and create fake IDs. He or she then tries to sell it to an unsuspecting buyer by executing a forged deed in your name. An alternative scam is to submit a mortgage application in your name to get cash out of the house.
The good news is that except in very rare circumstances, a fake deed won’t transfer your title, even if it initially gives the appearance of a transfer in public records, nor will a forged mortgage create any obligation for an innocent homeowner to pay. The bad news is that restoring your title and clearing the property of any fraudulent mortgages can be a lengthy and expensive process.
Sarah Frano, a vice president and real-estate fraud expert at First American Title Insurance Co., said there has been a sharp rise in seller impersonation fraud over the past few years, where a fraudster impersonates an owner by forging a deed conveying property to an unsuspecting buyer.
Several factors are driving the increase, including the rising popularity of remote closings and notarizations, where the parties aren’t present in person at the closing table. Home equity, which hit a record $16.9 trillion in the first quarter of 2024, according to data provider Intercontinental Exchange , is also contributing to the incidence of fraud. For scammers, that equity, which can be unlocked by a sale of a home, a cash-out refinance or a second mortgage, is an opportunity to sell the property out from under you or to steal your identity to mortgage your house.
“If you bought a house and have a big mortgage, the chances of it being stolen from you are quite slim,” said Richard Howe, register of deeds of the Northern District of Middlesex County in Lowell, Mass. “The key for this is for the wrongdoers to get a loan against the property or sell it, and nobody’s going to buy a property or put a loan against it if there is a big mortgage on it.”
Petrescu said he’s also seeing a rising number of title theft cases involving investment properties owned by limited liability companies, where a partner who was recently kicked out of the LLC continues to act and executes documents trying to transfer the property when he’s no longer part of the company or authorised to sell it.
Still, the actual risk of losing your home to title theft is quite low. “There would have to be an extreme set of facts showing the owner was aware of the issue and took no action to correct it before that deed could be deemed as valid,” said Petrescu.
But there are ramifications nonetheless. If a homeowner discovers a fraudulent deed or mortgage while applying for a home-equity loan, for example, that could push the loan application back six months or more while title gets cleared, Petrescu said. And, if they are attempting to sell the property, a title company may not want to insure the property if there is a rogue deed recorded in the county records even if it is apparent that it wasn’t a valid transfer. “So, this has real consequences,” he said. “Even if someone is not going to lose title to their property, it could be a huge setback for them.”
Here are some things you can do to avoid becoming the victim of home-title theft.
Be alert to the early signs . After targeting a vulnerable property, a home-title thief will usually try to impersonate you using forged documents, such as a Social Security card or driver’s license. There are telltale signs that someone may be trying to steal your identity. Credit inquiries will show up on a credit report, so be sure to check your credit reports regularly or consider subscribing to one of the paid services that monitors credit on your behalf. You can also freeze your credit, which restricts access to your credit report. If you receive strange bills in the mail or phone calls from lenders you haven’t contacted, or if strangers start asking questions about who owns your vacant vacation home, those can also be signs that home-title theft may be under way.
Monitor your title . Many counties offer free title monitoring services that notify owners if a new document is recorded against their property. In the Northern District of Middlesex County in Lowell, Mass., owners can register up to three residential properties, according to Howe, who noted that in his 29-year career he has only seen one case of title fraud, in January 2024, and that involved a property that was vacant because the owners were deceased. Frano suggests setting up a free Google alert for your property address. That way, if a fraudster lists your property for sale, an alert may help you stop it before it happens.
Buy the right type of title insurance . While lenders require title policies to insure their own interests when a property is mortgaged, it is a good idea to also purchase an owner’s policy when you purchase a house. There are two different types of owners’ policies, and, unfortunately, they are similarly named, which can get confusing. A standard American Land Title Association (ALTA) Owner’s Policy provides coverage only for forgeries that took place before you purchased your home, such as fake deeds in the chain of title before your closing. But this type of policy won’t protect you against forgery occurring after your property purchase. For that, you may want to consider the more comprehensive Homeowner’s Policy of Title Insurance, which does cover forgeries occurring after your closing, according to Steve Gottheim, ALTA general counsel. That enhanced coverage, available in most states, comes at an additional cost, though, which varies based on the location and purchase price of your home. Either policy will cover you for losses you incur due to fraud or forgery, including attorney fees and expenses incurred to clear title, up to the policy limit, but only the Homeowner’s Policy will cover fraud after you purchase the home.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
Automobili Lamborghini is turning its attention to something considerably more difficult to define: what makes Italian excellence uniquely Italian?

Mirvac’s 45-level Trielle has topped out at Yarra’s Edge, pairing riverfront apartments with wellness facilities, private dining and resident services.
3 min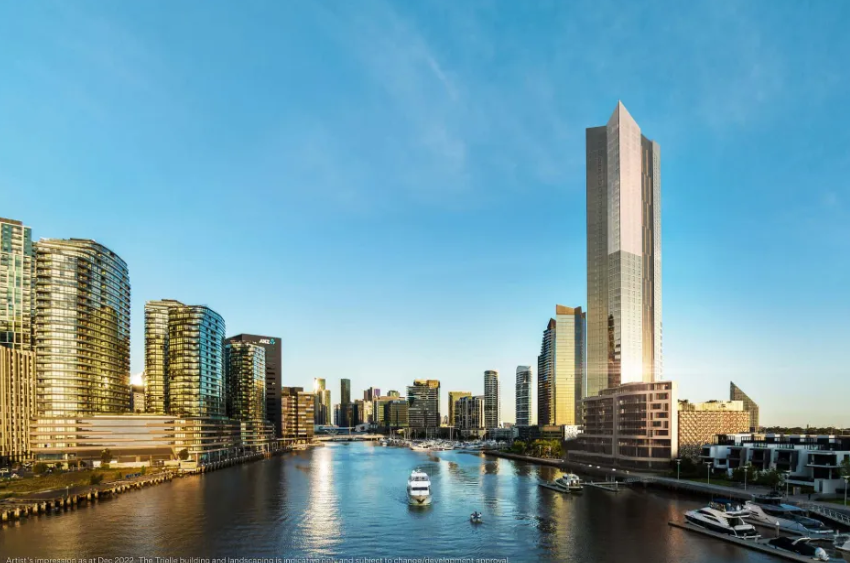
Mirvac has topped out Trielle at Melbourne’s Yarra’s Edge, with more than 70 per cent of the riverfront development sold and approximately 80 per cent of purchasers intending to make their apartment a home.
The figures, released on September 22, point to an owner-occupier audience for one of the precinct’s final residential towers. Mirvac began developing Yarra’s Edge in 2003, and its latest addition occupies one of the remaining absolute riverfront sites.
Mirvac CEO of Development Stuart Penklis said existing residents were among those moving up within the neighbourhood.
“Many purchasers already have a connection to Yarra’s Edge,” Mr Penklis said, describing buyers whose changing needs were encouraging an upgrade within the precinct.
“As one of the final residential towers within Yarra’s Edge, Trielle represents the culmination of more than two decades of creating one of Melbourne’s most established and sought-after waterfront communities,” Penklis said.
“Positioned on the Collins Street axis with absolute river frontage, Trielle offers residents a rare opportunity to enjoy sweeping views across the Yarra River, Melbourne skyline and Port Phillip Bay, while remaining seamlessly connected to the CBD. With Trielle now more than 70 per cent sold, we’re continuing to see strong demand from buyers seeking quality homes in established locations.”
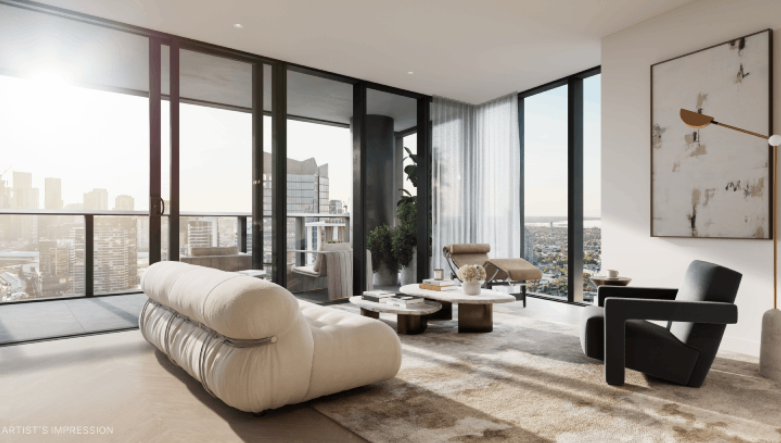
The developer also flagged a penthouse and sub-penthouse collection with larger layouts, premium finishes and broad outlooks. The planned wellness centrepiece, The Oasis, encompasses a 900-square-metre elevated urban rainforest.
Mirvac General Manager Residential Development Victoria Elysa Anderson said Trielle had resonated strongly with buyers seeking a rare lifestyle offering in Melbourne.
“Opportunities to secure a new luxury residence on a riverfront site of this calibre are incredibly rare, particularly within a community like Yarra’s Edge,” Anderson said.
“What makes Trielle unique is the combination of exceptional views, world-class residential facilities and the lifestyle that already exists around it. Residents are buying into a mature waterfront community with parks, promenades, dining, wellness and strong community connections already in place.”
The 45-level tower brings a substantial new presence to that waterfront. Its residential offering spans one-, two-, three- and four-bedroom apartments, with Signature, Prestige and Sub-Penthouse collections accommodating different household sizes. The north-facing position connects the apartments visually to the river and city beyond.
Seven storeys above the promenade, the planned Oasis combines planting and a running stream with a Scandinavian-inspired wellness club developed with spa specialist Naomi Gregory. Facilities include a 25-metre lap pool, hot magnesium pool, sauna, hydrotherapy, a gym, yoga and Pilates room, and treatment spaces.
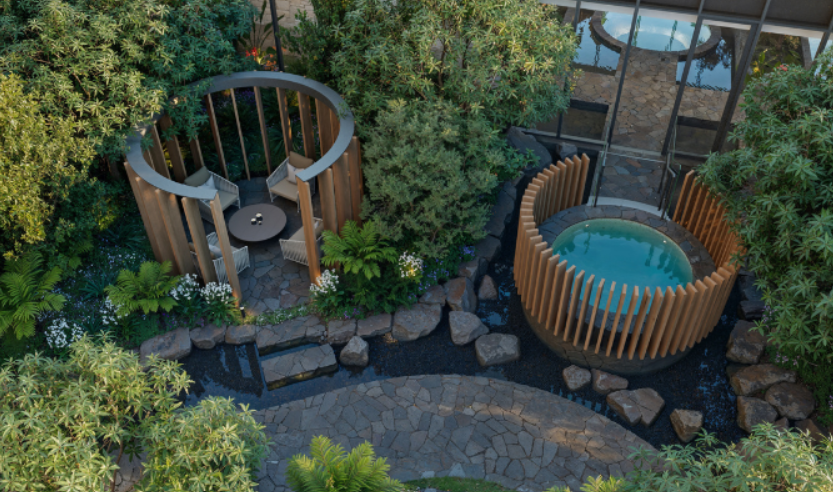
The amenity extends beyond exercise. Residents will have access to The Biblioteca library and workspaces, ground-floor work pods, and The Salone piano lounge. A private Chef’s Table dining room offers a setting for larger gatherings, while a cinema, games room and sports lounge broaden the entertaining options. Concierge services and a dog-wash area support everyday routines.
Trielle comprises a collection of one, two, three and four-bedroom residences. Reflecting strong demand from owner occupiers, approximately 80 per cent of purchasers to date intend to live in their homes, highlighting the project’s appeal to those seeking a long-term waterfront lifestyle.
Mirvac has recently delivered The Albertine, a premium apartment development on the edge of Melbourne’s CBD, and is nearing completion of Prince & Parade in Brunswick, further strengthening its portfolio of thoughtfully designed apartment communities in some of Melbourne’s most sought-after urban locations.
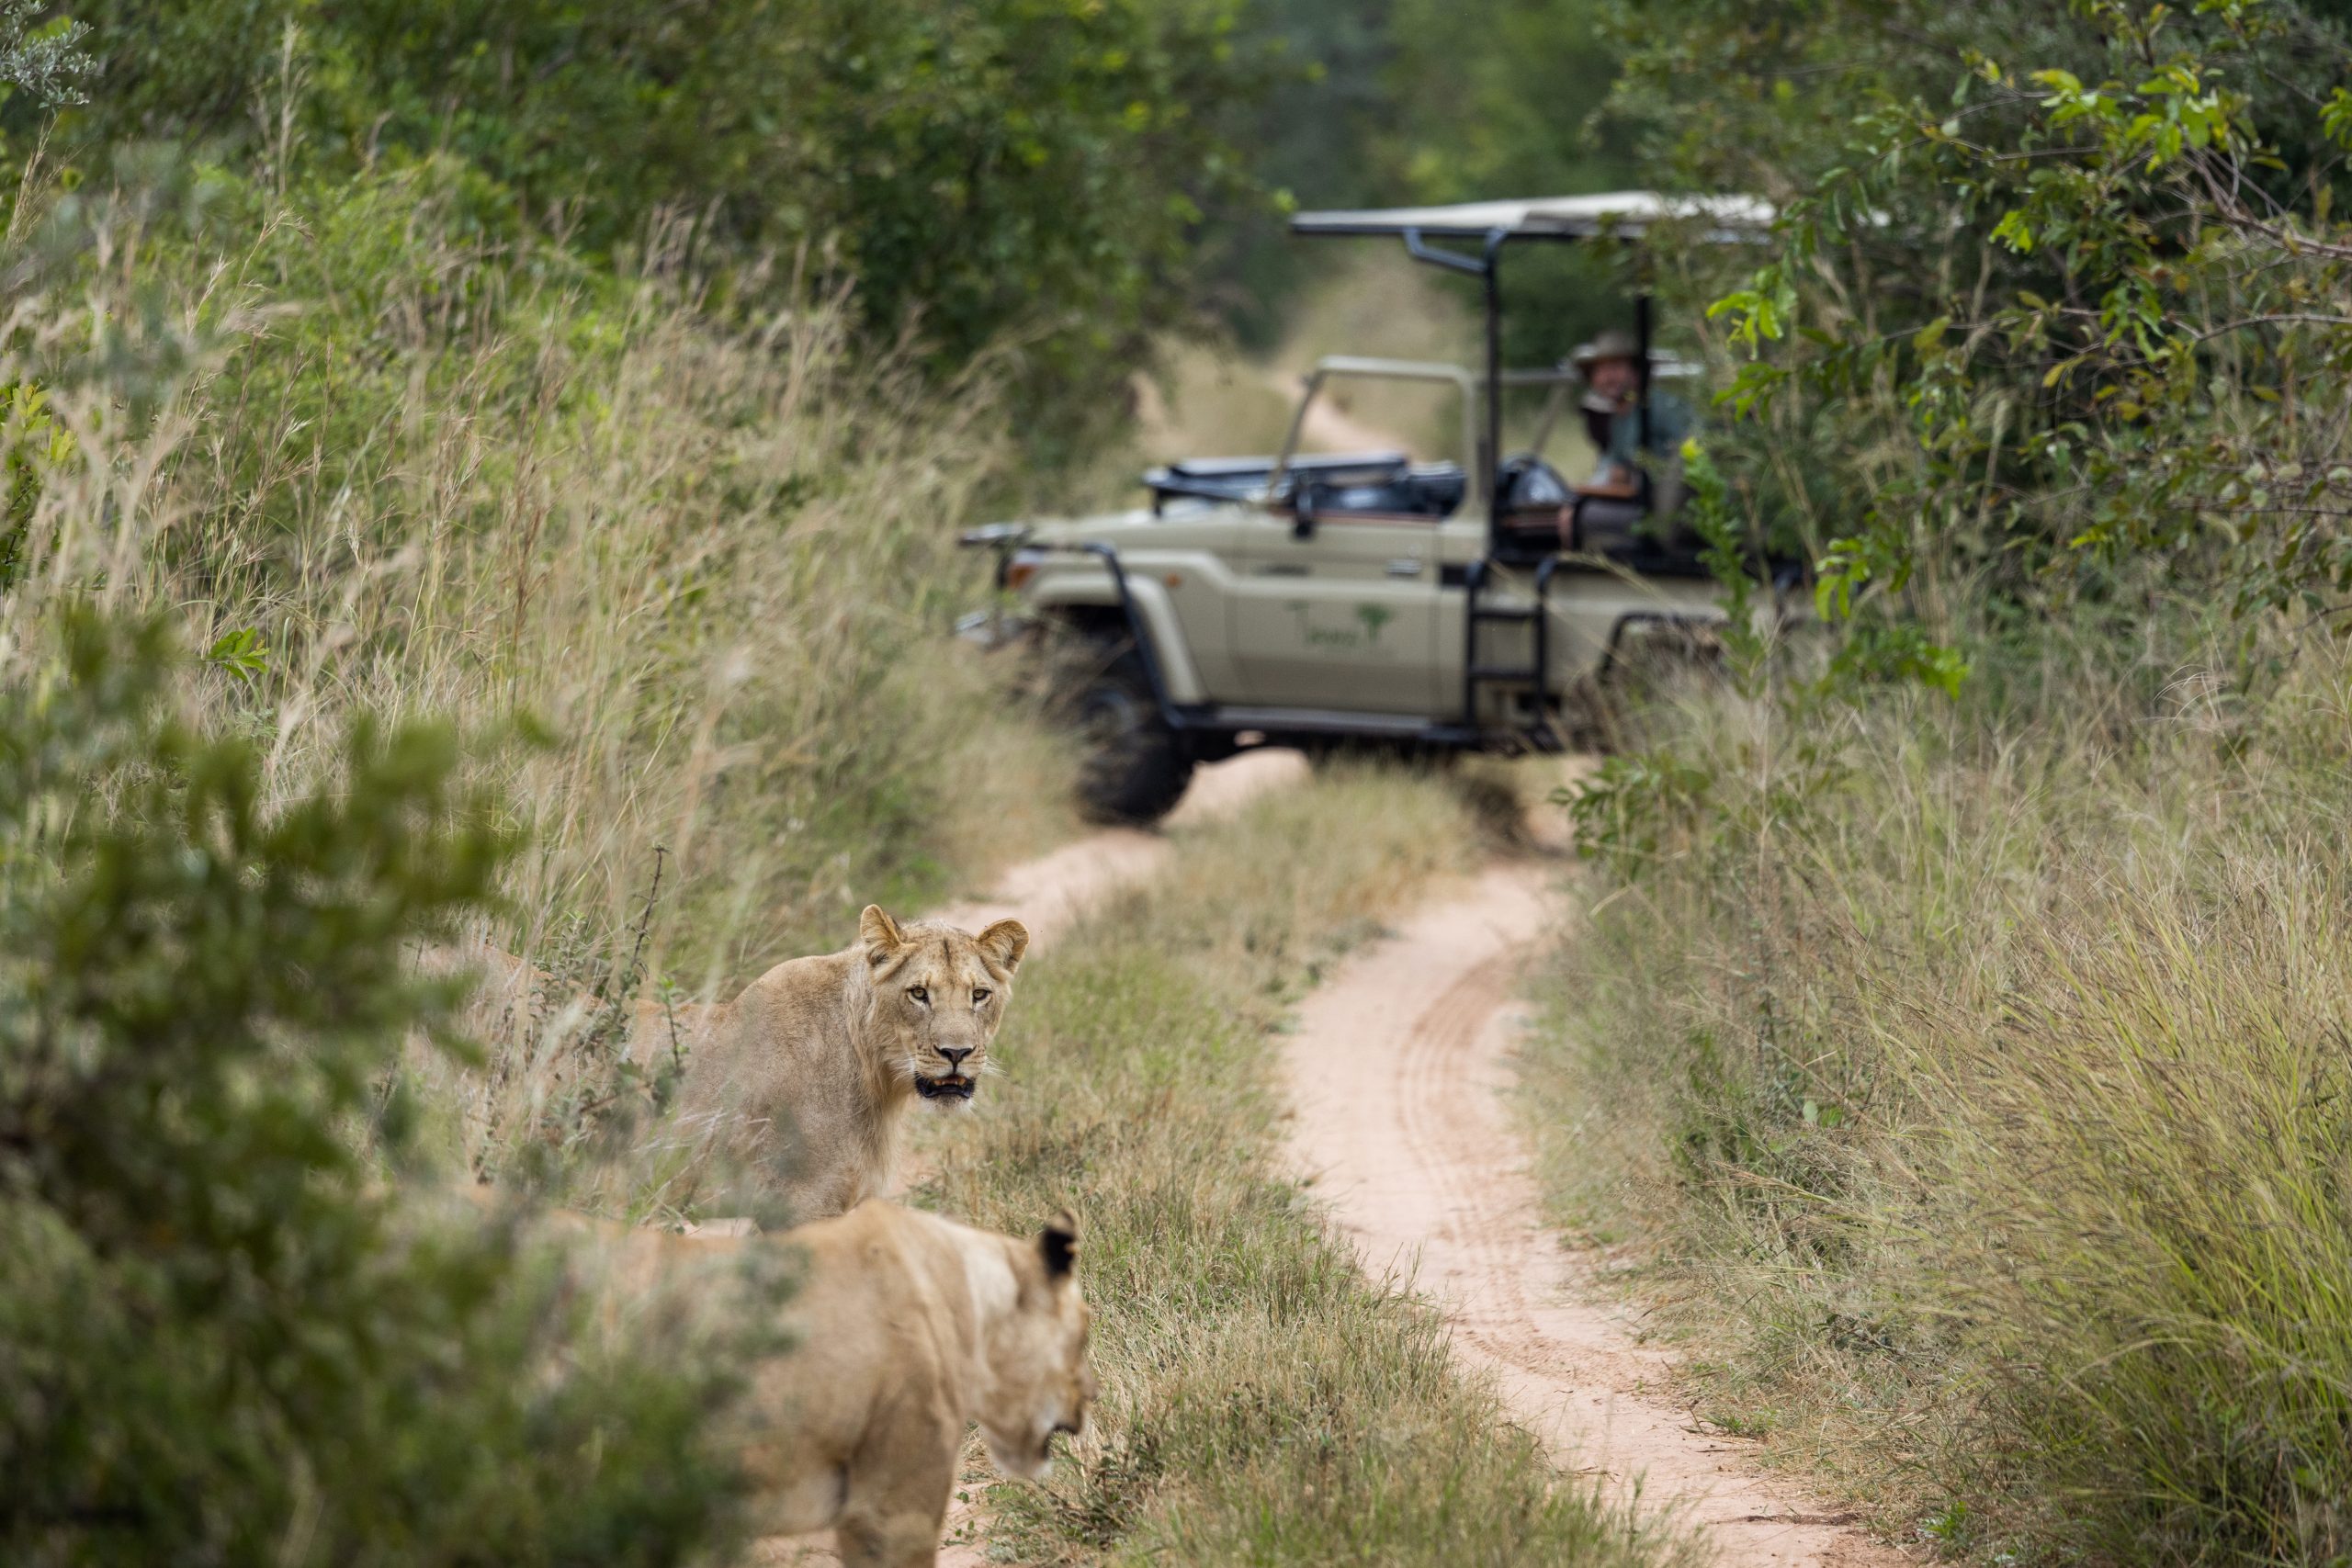
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.
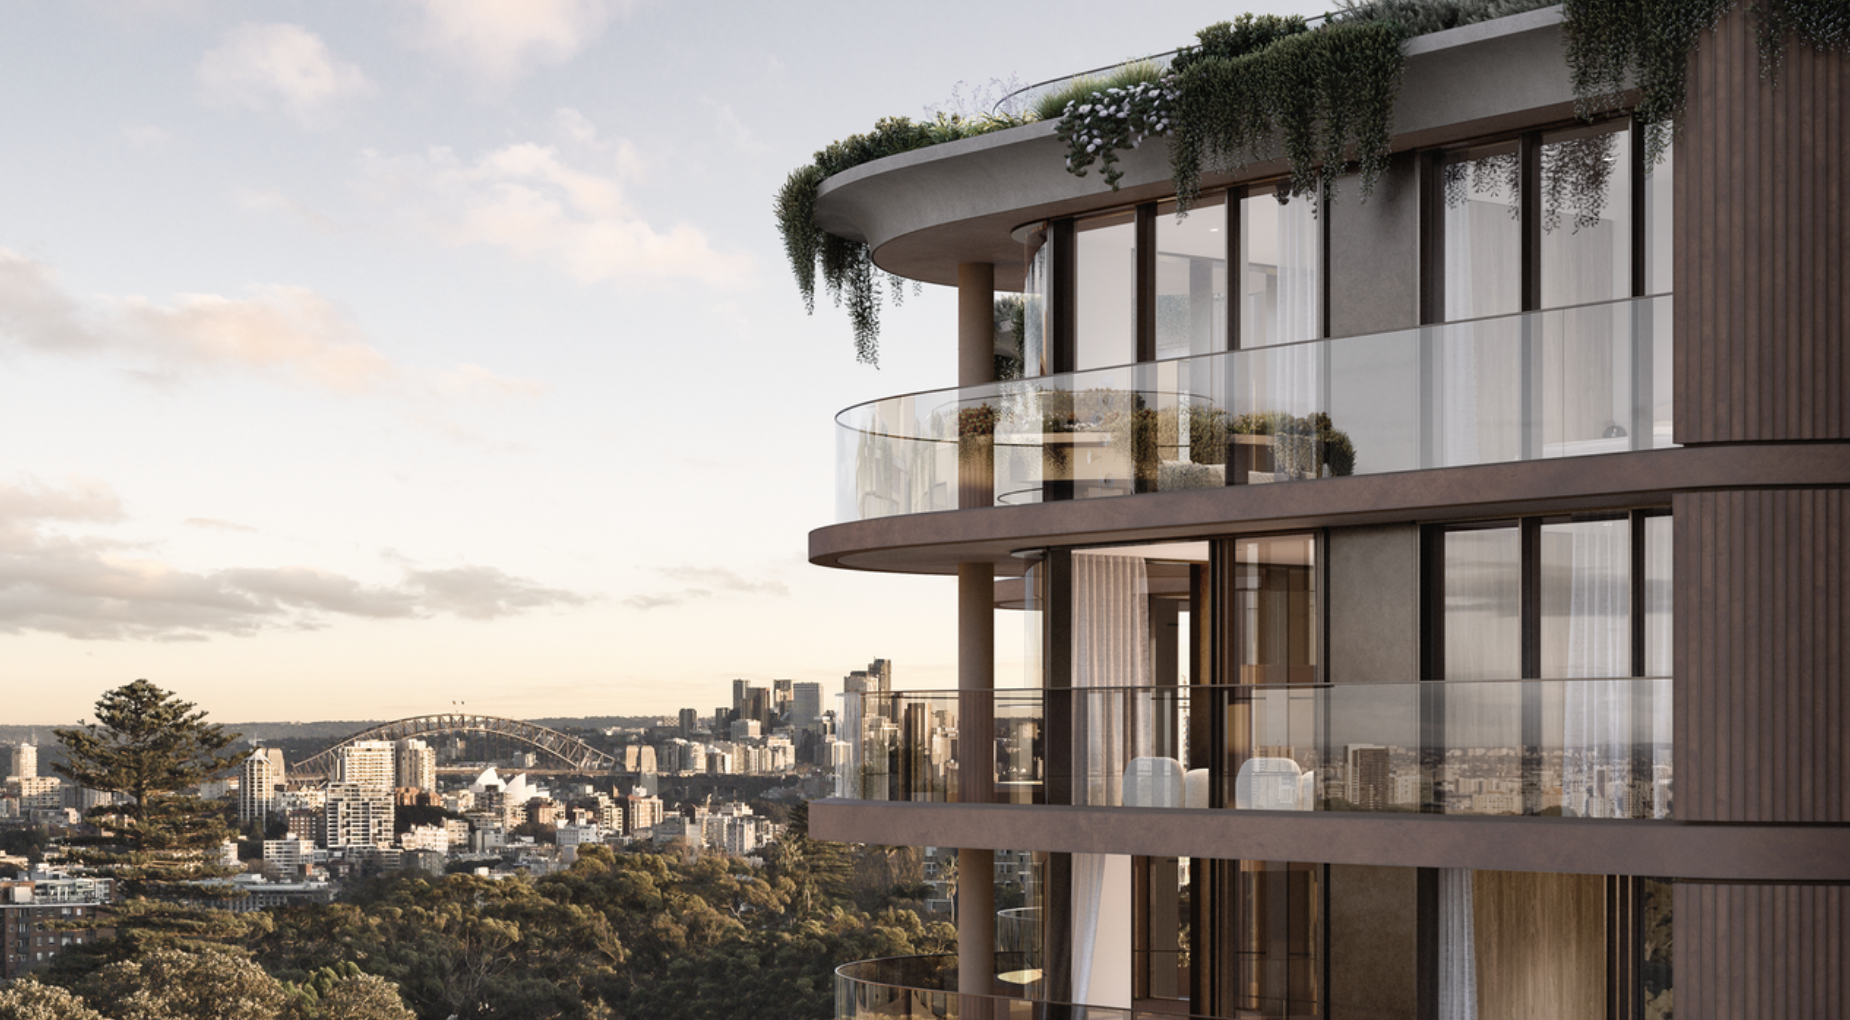
A record-breaking $11 million sale at The Centennial Collection has set a new benchmark for luxury apartment living in Bondi Junction.