The new broom bringing confidence back to the multi-residential market
Buyers had more chance of winning $20 million in the lottery than buying into a building with no defects, one expert says
 5 min
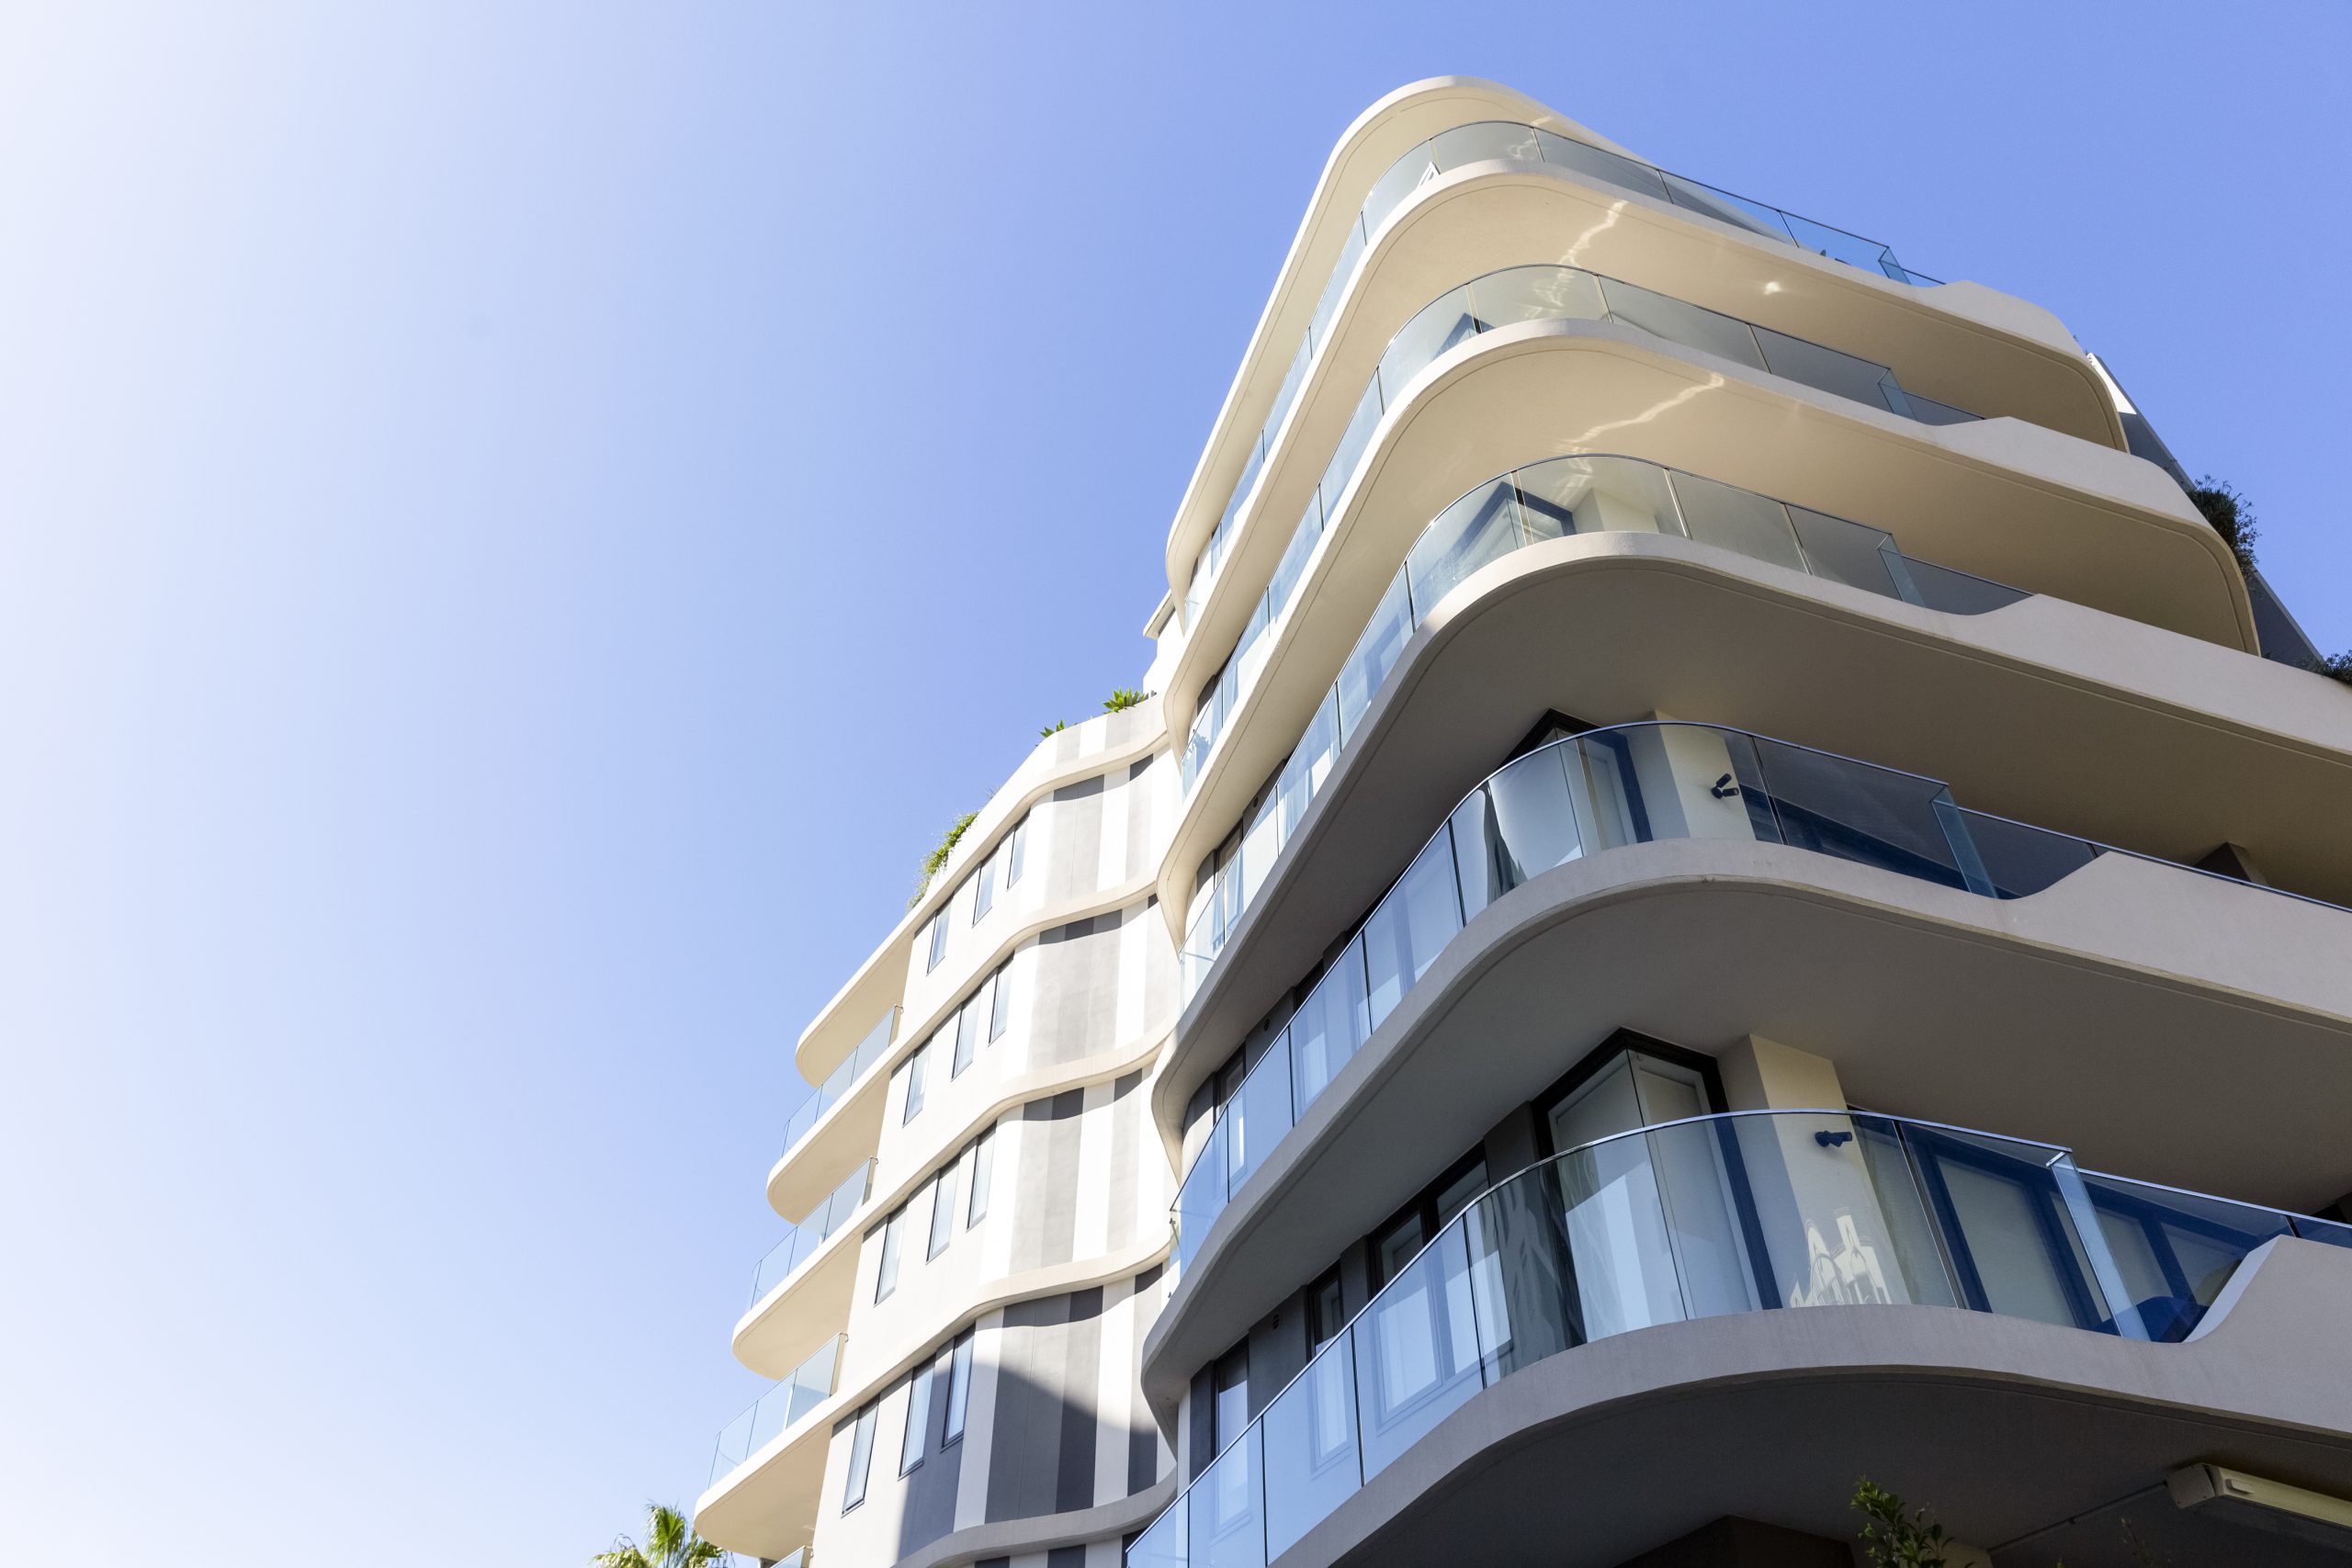
Most of us watched in disbelief as the nightly news flashed reports about the thousands of residents evacuated from their western Sydney apartment block on Christmas Eve 2018. The dire warning of a possible collapse in the Opal Tower came after several residents reported hearing loud cracks in the apartment block of 392 homes at Sydney Olympic Park. Structural cracks were found in the pre-cast concrete panels.
Months later, 130 residents were given hours to flee their 10-storey Mascot apartment building after cracks were discovered in the basement raising concerns of collapse. They were never able to move back in.
These homeowners became the very public face of the poor standards plaguing the $24 billion NSW building and property development industry. But you didn’t have to end up on the six o’clock news to empathise.
Four in 10 new residential apartment blocks in NSW have serious defects at an average cost of more than $330,000 a building, according to the Strata Community Association of NSW, with waterproofing and fire safety the most common problems.
And up until recently, the only avenue homeowners had to seek help was negotiating directly with the builder or developer, or embarking on a lengthy and expensive legal battle to get the defects rectified.
For more stories like these, order your copy of the autumn issue of Kanebridge Quarterly magazine here.
When the first NSW building commissioner was appointed in 2019 under the Berejiklian government, changes came swiftly. David Chandler, a 40-year veteran of the building industry, was armed with legislative powers to overhaul the state’s residential building sector — the RAB or Residential Apartment Buildings (Compliance and Enforcement Powers) Act — in what was called once-in-a-generation reforms.
And he wasted no time doing exactly that. The reforms included the power for Chandler to issue developers with orders to rectify serious defects before granting them an occupation certificate.
“The RAB Act was a turning point, it was an important piece of legislation which is quite unprecedented in the country…I’m the only regulator who has the powers that are in the RAB Act,” Chandler says. “It really needed to be brought in; it switched the balance to give consumers a much better standing than perhaps they have had in the past. In effect, it allows me to stop the issuance of an occupation certificate, and therefore consumers ultimately being forced to settle on their apartments.
“I use those powers very, very cautiously, but I have used them.”
Chandler also backed moves to give more power to apartment owners, pointing out that they had less consumer protection than someone buying a toaster or washing machine. To this end, he supported the creation of a ratings system for developers — the independent Construction Industry Rating Tool or iCIRT — to help homeowners arm themselves against buying apartments with defects.
Prior to this, homeowners had few, if any, resources to have defects fixed. A 2012 report by the UNSW City Futures Research Centre found 72 percent of apartment blocks in NSW had defects and in newer units it was as high as 85 percent.
An unregulated industry where tight deadlines and budgets to complete major works were written into contractual agreements between builders and sub-contractors led to cost cutting and a rise in defects.
“It was shocking,” says executive director of the Owners Corporation Network of Australia, Karen Stiles, about the state of the residential apartment sector before Chandler’s appointment.
“You had more chance of winning a $20 million lottery than you did of having a building with no defects.”
“Unfortunately most of us fall in love with the glossy brochure. That’s why iCIRT is so good. We are so used to seeing a ratings system on electrical appliances and cars but until now there has never been one on builders and developers.
“I’m hearing reports of people taking back their deposits when they discover a developer is not rated. It’s a really powerful card to play for a prospective buyer.”
Mirvac was the first major property developer to be rated on iCIRT and is the only company to have a five-star rating. Mirvac was awarded the five-star rating following a detailed, independent and rigorous review and Stiles hopes their addition will encourage other major developers to come forward and be added to it.
“Raising the standard of construction in NSW is critically important to protect purchasers and restore confidence in buying off the plan and newly built apartments,” says Mirvac’s head of residential Stuart Penklis about iCIRT.
Stephen Brell, president of the Strata Community Association of NSW, believes a new scheme called Project Intervene — which allows homeowners to bypass the courts and engage directly with a developer to fix defects with the support of NSW Fair Trading and the NSW Building Commissioner — is the most exciting new reform to come out of Chandler’s reign.
“It’s a really cost effective program and removes the often combative and expensive legal element from the process of having defects rectified,” he says.
“Before, the onus of proof was on the owners corporation, so you would spend tens of thousands of dollars to identify the defects and then tens of thousands to get it through the courts. But Project Intervene only works if the builder has not gone into receivership.”
Another positive move is the introduction of a decennial insurance product which allows owners corporations to have serious defects fixed by builders for up to 10 years after the building is first occupied. Brell says the positive changes Chandler has brought in don’t just help homeowners, but all elements of the industry, including the vast majority of honest builders who now have a way to distance themselves from the dodgy developers in the market.
With Chandler set to retire in August, there is hope that the sweeping changes he made will be upheld.
“Chandler has set up a legacy system for NSW,” says Brell. “He has a great team and two significant and brand new pieces of legislation: the Design and Building Practitioners Act and the Residential Apartment Buildings (Compliance and Enforcement Powers) Act. This will give the commissioner’s office certain powers to last beyond Chandler’s retirement.”
Chandler himself is hopeful for the future of the NSW residential apartment industry and wants to pass on this positive outlook to a new generation.
“I am (hopeful) because the industry doesn’t want to go back to where it came from,” Chandler says. “The other challenge we also have is to make sure we have tomorrow’s workforce; we were facing a situation where young people were hearing such horrendous stories about our industry that their parents were doing everything in their power to dissuade them from coming into our industry, which is a great industry.
“So we’re working with TAFE, we’re working with a whole range of employer groups to attract the next workforce, which has got to be a composition of male and female.
“If by 2025 we can lift the number of women in our industry up to 20 per cent that would be a great outcome, and if a few years down the track we can raise it to another level, that would be great.”

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.

A 30-metre masterpiece unveiled in Monaco brings Lamborghini’s supercar drama to the high seas, powered by 7,600 horsepower and unmistakable Italian design.