The real driver of Australian population growth
With the number of local births on the decline, Australia is increasingly looking to other sources to meet ongoing labour demands
 2 min
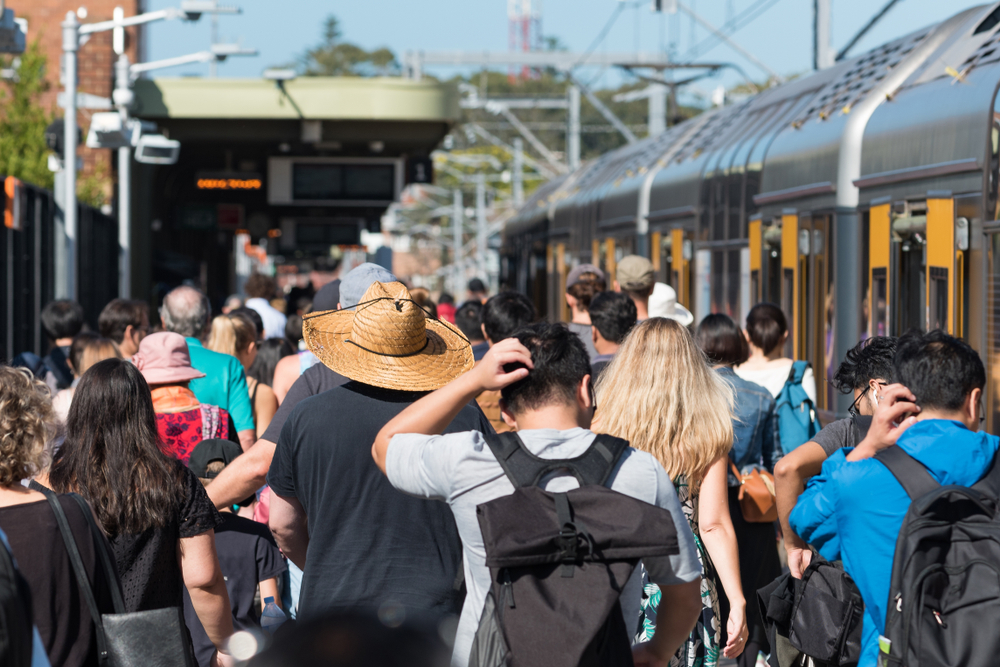
Australia’s population grew by 2.5 percent to 26.8 million people over the 12 months ending 30 September, according to new figures from the Australian Bureau of Statistics (ABS). This was an annual increase of 659,800 people, with migrants making up 83 percent of the increase at 548,800. Natural increase, which is births minus deaths, contributed to a net gain of 111,000 people.
Natural increase was 3.9 percent lower than the same period in 2022, reflecting a trend in Australian women having fewer babies. Migration was 60.3 percent higher than the same period in 2022, however the data from this period was impacted by the border closure until February 2022. Most migrants arriving in the 12 months to 30 September 2023 were international students and workers on temporary visas. The overwhelming majority of migrants are coming from India, China, and the Philippines. Of the 548,800 net migrants that relocated here over the 12 months, 34 percent settled in New South Wales, 29.5 percent settled in Victoria and 16 percent settled in Queensland.
Western Australia had the fastest population growth rate, up 3.3 percent, followed by Victoria at 2.9 percent, Queensland 2.7 percent, New South Wales 2.3 percent, Australian Capital Territory 2.1 percent and South Australia 1.7 percent. The lowest growth was in Tasmania at 0.3 percent.
Drivers of Western Australia’s highest population growth rate since 2009 include record employment and a booming economy. The state government upgraded its state final demand forecasts for FY24 from 3 percent to 4.5 percent in December.
While the biggest contributor to the state’s population growth is international migration, Professor Amanda Davies, Head of Social Sciences at the University of Western Australia, comments that strong interstate migration is resulting from “‘push’ factors operating in major east coast states, and in particular high costs of living and housing.” Strong buyer demand has pushed the Perth median house price up 18.6 percent, which is the strongest annual rate of growth anywhere in Australia.
The Perth median house price is $718,560, according to CoreLogic. Real Estate Institute of Western Australia CEO Cath Hart commented: “We can expect to see house prices and rents continue to rise, homes to sell and lease quickly, and the rental vacancy rate to remain low for some time yet.”
The ABS also tracks interstate migration, which is the movement of Australian residents between states and territories. Over the 12 months to 30 September, Queensland had the highest rate of net interstate migration at 32,625 people, followed by Western Australia with 11,233.
The state that lost the most residents was New South Wales, with a net 33,302 people moving elsewhere and the bulk of them departing Sydney. This net outflow is much higher than other parts of Australia. The second highest loss through interstate migration was in the Northern Territory with 3,606. Victoria lost just 1,119 people. NSW Productivity Commissioner Peter Achterstraat AM recently warned that Sydney is losing many residents aged in their 30s and 40s due to unaffordable property values. He says Sydney “could become known as the city with no grandchildren”.

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
International AI strategist Justin Kabbani will headline the Kanebridge Property Summit in Sydney on June 18, with tickets selling fast.
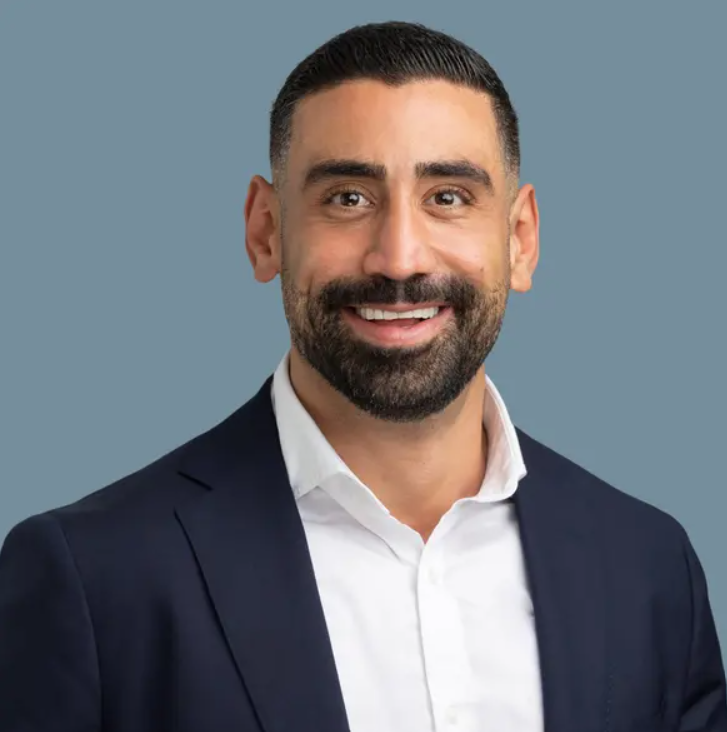
Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices