

What Aussies Are Doing To Cope With The Cost-of-living Crisis
Limiting spending, refinancing loans, moving back home with mum and dad and working a side hustle are popular options being adopted today
 3 min
Mortgage holders are limiting household spending and refinancing their loans, while a rising number of young Australians are moving back home with their parents. These are some of the ways in which people are dealing with today’s cost-of-living crisis, which has been caused by the highest inflation rate in two decades along with rising interest rates and rents, according to research by Finder.
Three in four Australians surveyed in September said they were somewhat or extremely stressed about their financial situation. This includes 84% of mortgage holders, up from 76% in September 2021. Finder says almost $15,000 in extra interest costs have been added to the annual repayments of an average Australian home loan. And that was before the Reserve Bank of Australia raised the official cash rate again this week. The RBA raised rates by 25 basis points to 4.35%. That was the 13th increase since May 2022 and takes the cash rate to its highest level since 2011.
The research cites data from the Australian Bureau of Statistics showing the total monthly value of refinanced home loans peaked at $22 billion in June. Finder says more than 70% of refinancing borrowers were going to a new lender rather than renegotiating with the existing one. However, the savings were fairly small. On average, refinancers went from a variable rate of 5.01% to 4.78%.
Graham Cooke, Finder’s Head of Consumer Research, said “the willingness of homeowners to refinance for even marginal gains underscores the pervasive cost-of-living crisis, reflecting a desperate search for any fiscal relief.” He added that millennial homeowners were struggling the most today. “This could be a sign that they jumped in when rates were at record lows and were unprepared for an environment where rates and repayments increased.”
Finder says young renters are increasingly moving back in with their parents to escape rising rents or to save to buy a home. Unaffordable rents prompted 30% to move back home. A further 30% did so to save money for a home deposit, while 14% said the loss of a job forced a change in living arrangements. Mr Cooke said interest rate rises were actually having a higher impact on renters, given landlords typically pass on higher costs to tenants through rent increases.
Cutting discretionary spending is another method of coping with rising costs. The Finder research shows 45% of Australians have cut back on dining out or ordering home delivery, 32% are shopping around for better prices, 23% have reduced beauty and self-care treatments, and 19% have cancelled a holiday. A small proportion (3%) have moved their child to a different school with lower fees.
Refinancing advice
Mr Cooke said it was important not to rush a refinancing decision. “There is a significant gap in rates offered by different lenders for comparable loan products. The best thing you can do is take the time to review and compare your home loan options to ensure you’re getting the most competitive rate. It’s never too late to find a better home loan deal.”
Advice if you’re moving back home
Mr Cooke said there was no point ‘returning to the nest’ without changing your spending habits. “Prioritising a budget is critical. Start cutting out non-essentials and look for ways you can save money. Working out all your expenses to the smallest detail will give you an idea of how much capacity you have to save.”
Tips for cutting spending
Finder says shopping around can help reduce non-discretionary spending as well. Finder recommends that consumers consider switching energy providers and insurers, and use a high-interest account for savings. RateCity recently reported that nine financial institutions on its panel are now offering savings account interest rates that are above inflation at 5.5% or more.
Take up a side hustle
Finder research also shows 35% of Australians are earning extra income through side hustle jobs like dog walking, mystery shopping, tutoring, freelancing and ride-share driving. Popular non-employed side hustles include recycling cans and bottles, making and selling goods, selling pre-owned goods and renting out a spare room or garage.
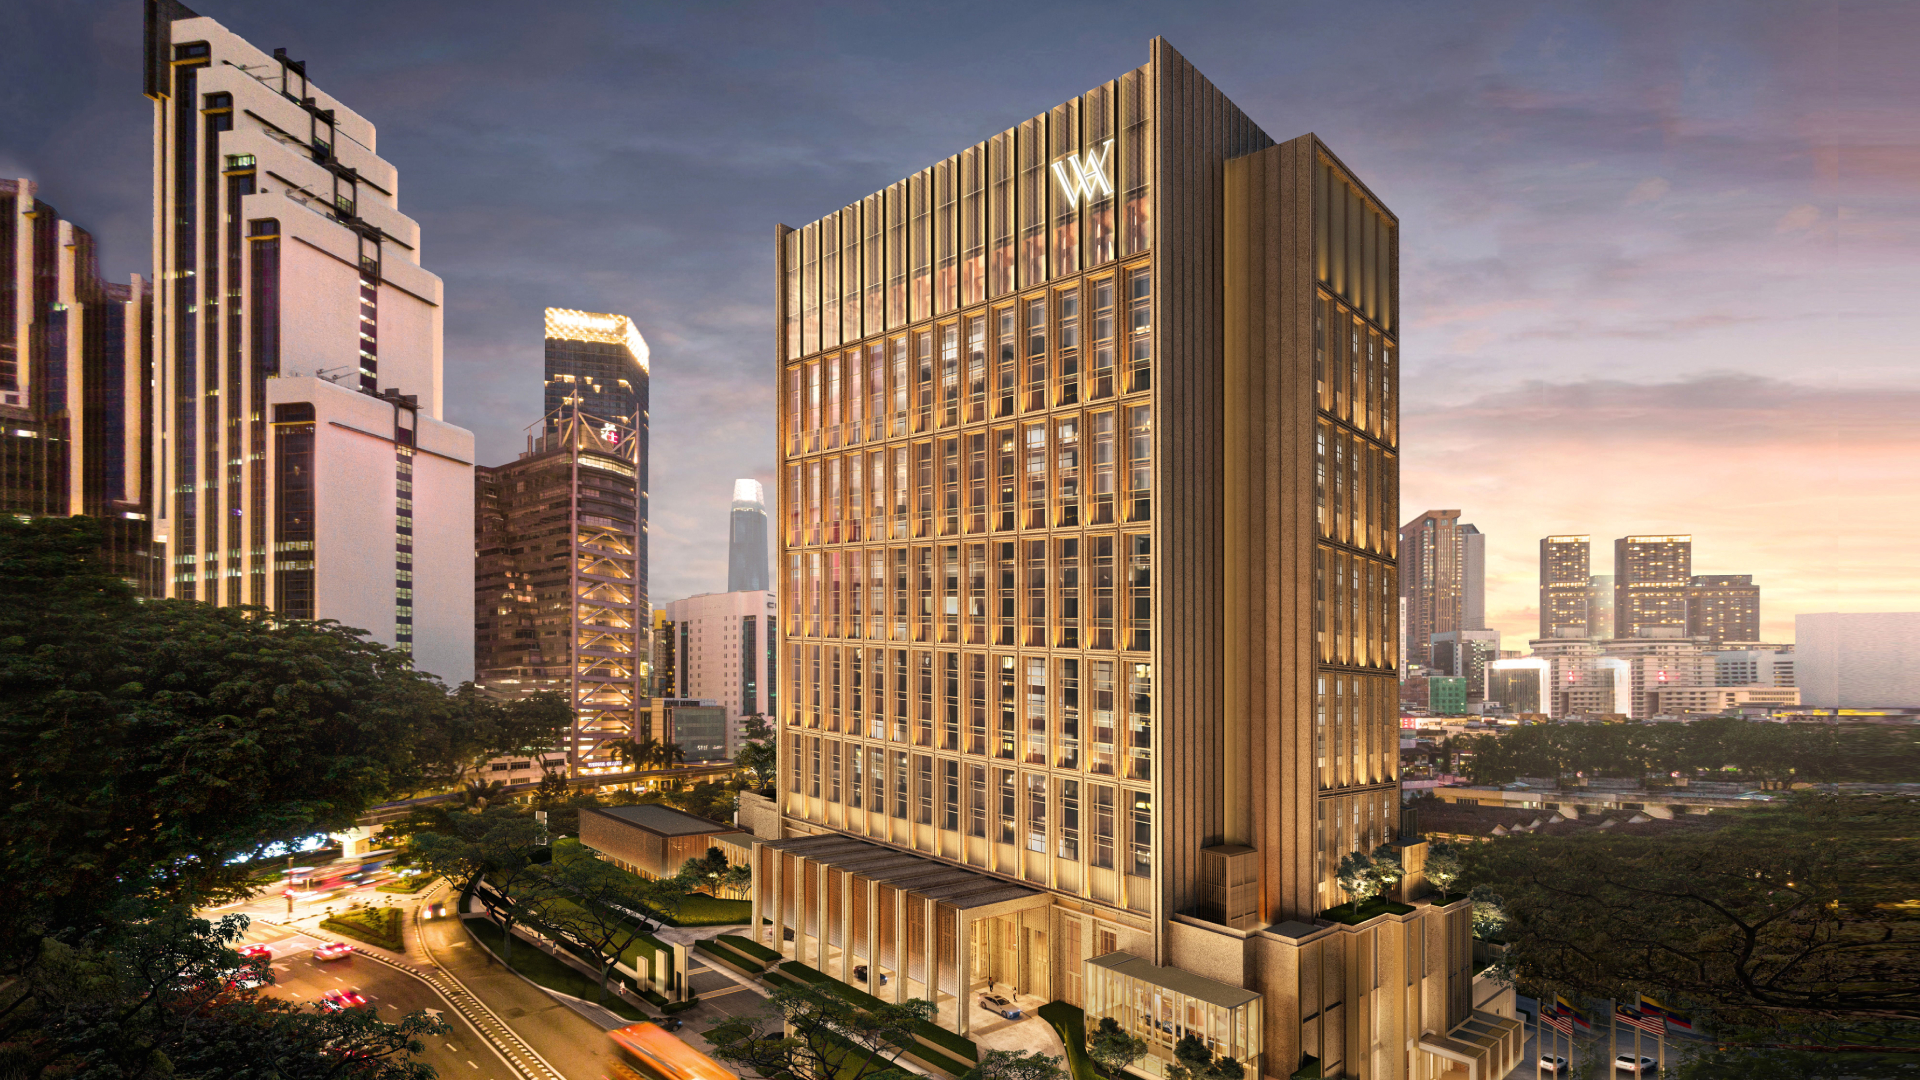
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.
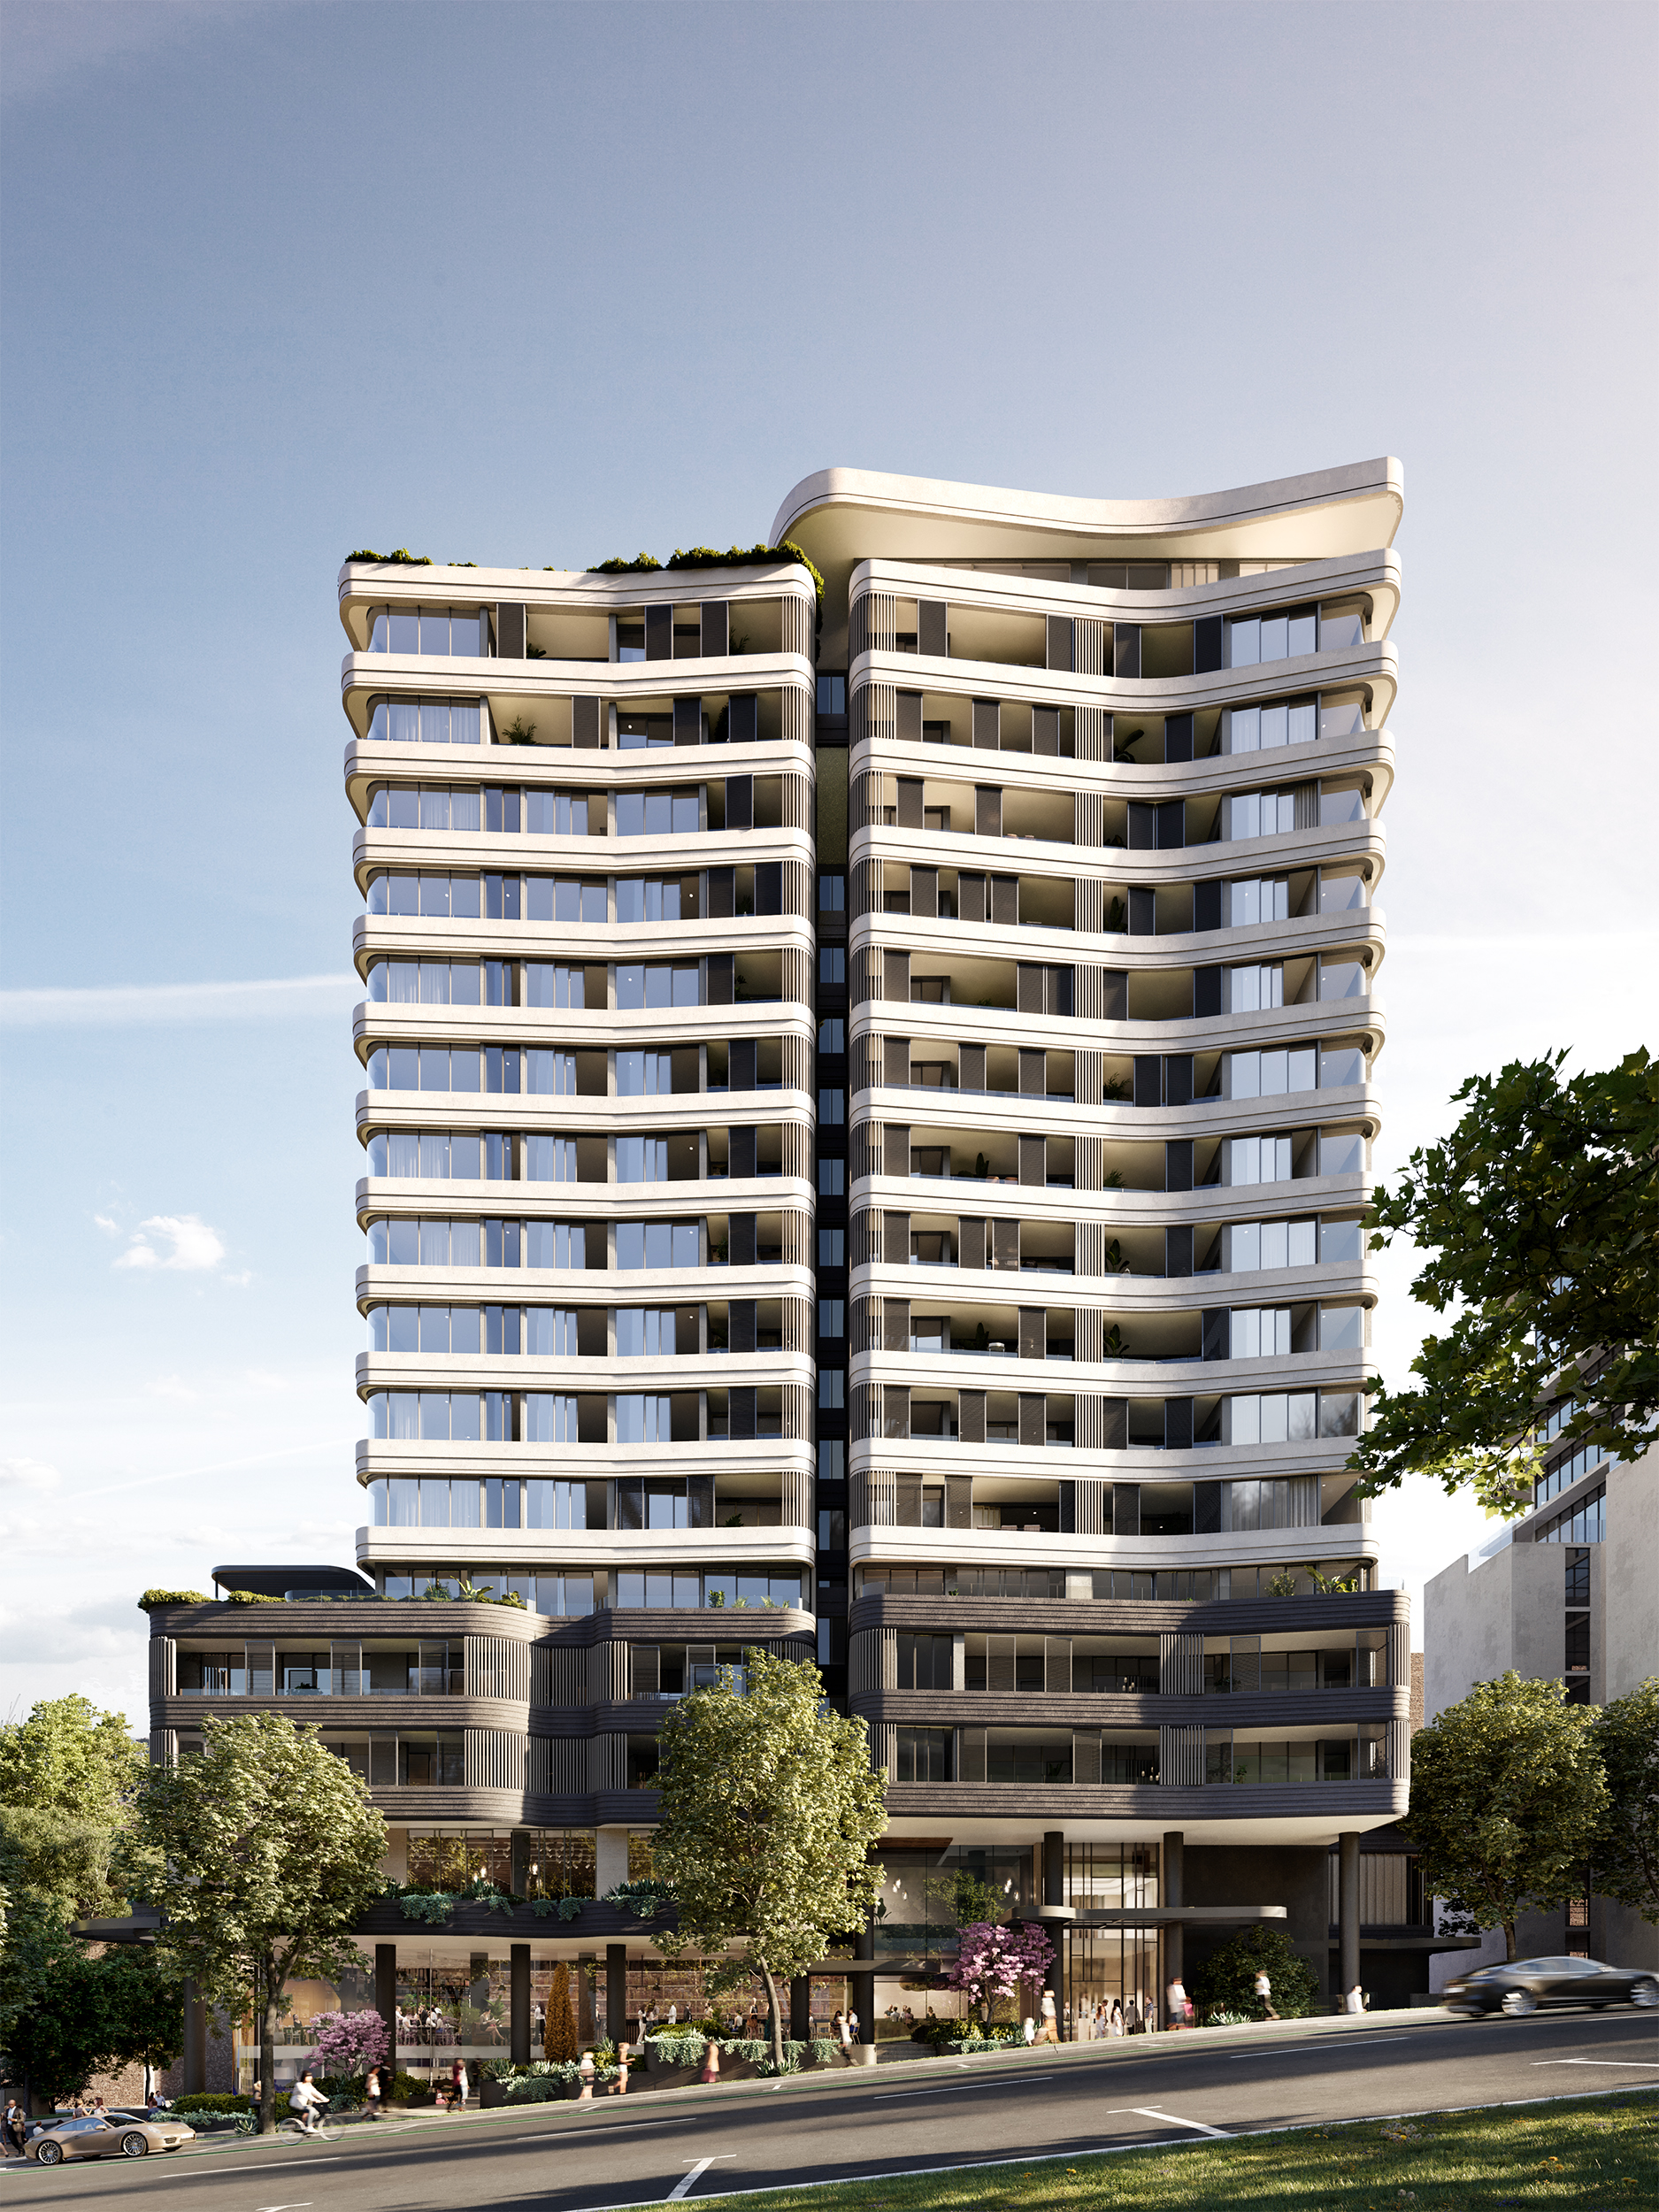
Located steps from Crows Nest Metro, the near-complete development brings luxury living to Sydney’s Lower North Shore.
Employment fell by 39,300 and unemployment held at a revised 4.7 per cent, giving the RBA more room to pause in November.
2 min
Australia’s labour market weakened in September, reducing—but not eliminating—the case for another Reserve Bank rate rise in November.
The seasonally adjusted unemployment rate was 4.7 per cent, according to the Australian Bureau of Statistics. August was revised to the same level, while September employment fell by 39,300 people. The number of unemployed Australians increased by 8,900 to 732,000.
The weakness extended beyond the headline rate. The employment-to-population ratio fell 0.3 percentage points to 63.6 per cent, participation declined 0.2 points to 66.8 per cent and underemployment edged up to 6.3 per cent. Part-time employment fell by 73,700, partly offset by a 34,400 increase in full-time work.
For the RBA, this is a clearer sign that restrictive monetary policy is cooling demand. Higher unemployment and falling employment reduce wage pressure over time and increase the risk that another rate rise would push the economy harder than necessary.
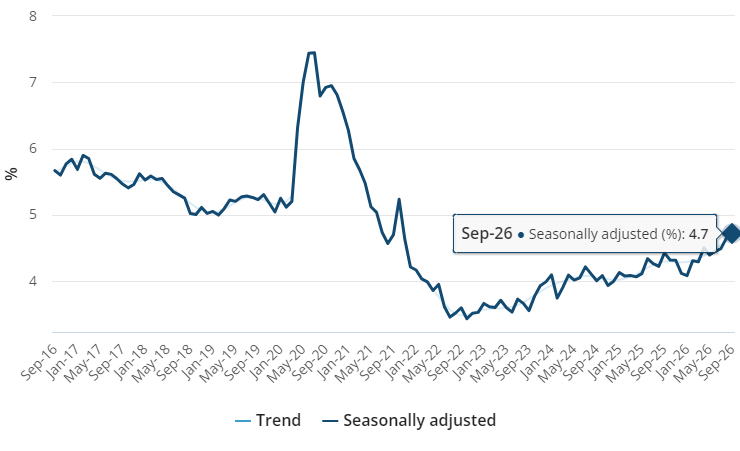
That makes a November increase less certain. It does not make a hold inevitable. The RBA must balance labour-market softness against inflation, and the September-quarter consumer price index due later in October will carry more direct weight in the decision.
For mortgage holders and property investors, the practical conclusion is not to trade one data release. Borrowers should continue testing repayments at higher rates, preserve liquidity and avoid basing a purchase on an assumed near-term reversal. Refinancing decisions should be assessed against total cost, not simply the advertised rate.
Property markets may initially welcome a reduced probability of another increase because borrowing capacity and sentiment are highly rate-sensitive. But a weakening labour market is not unambiguously positive for housing: job security supports mortgage serviceability, rental demand and buyer confidence.
The September numbers have given the RBA a credible reason to wait. Inflation will determine whether it can use it.
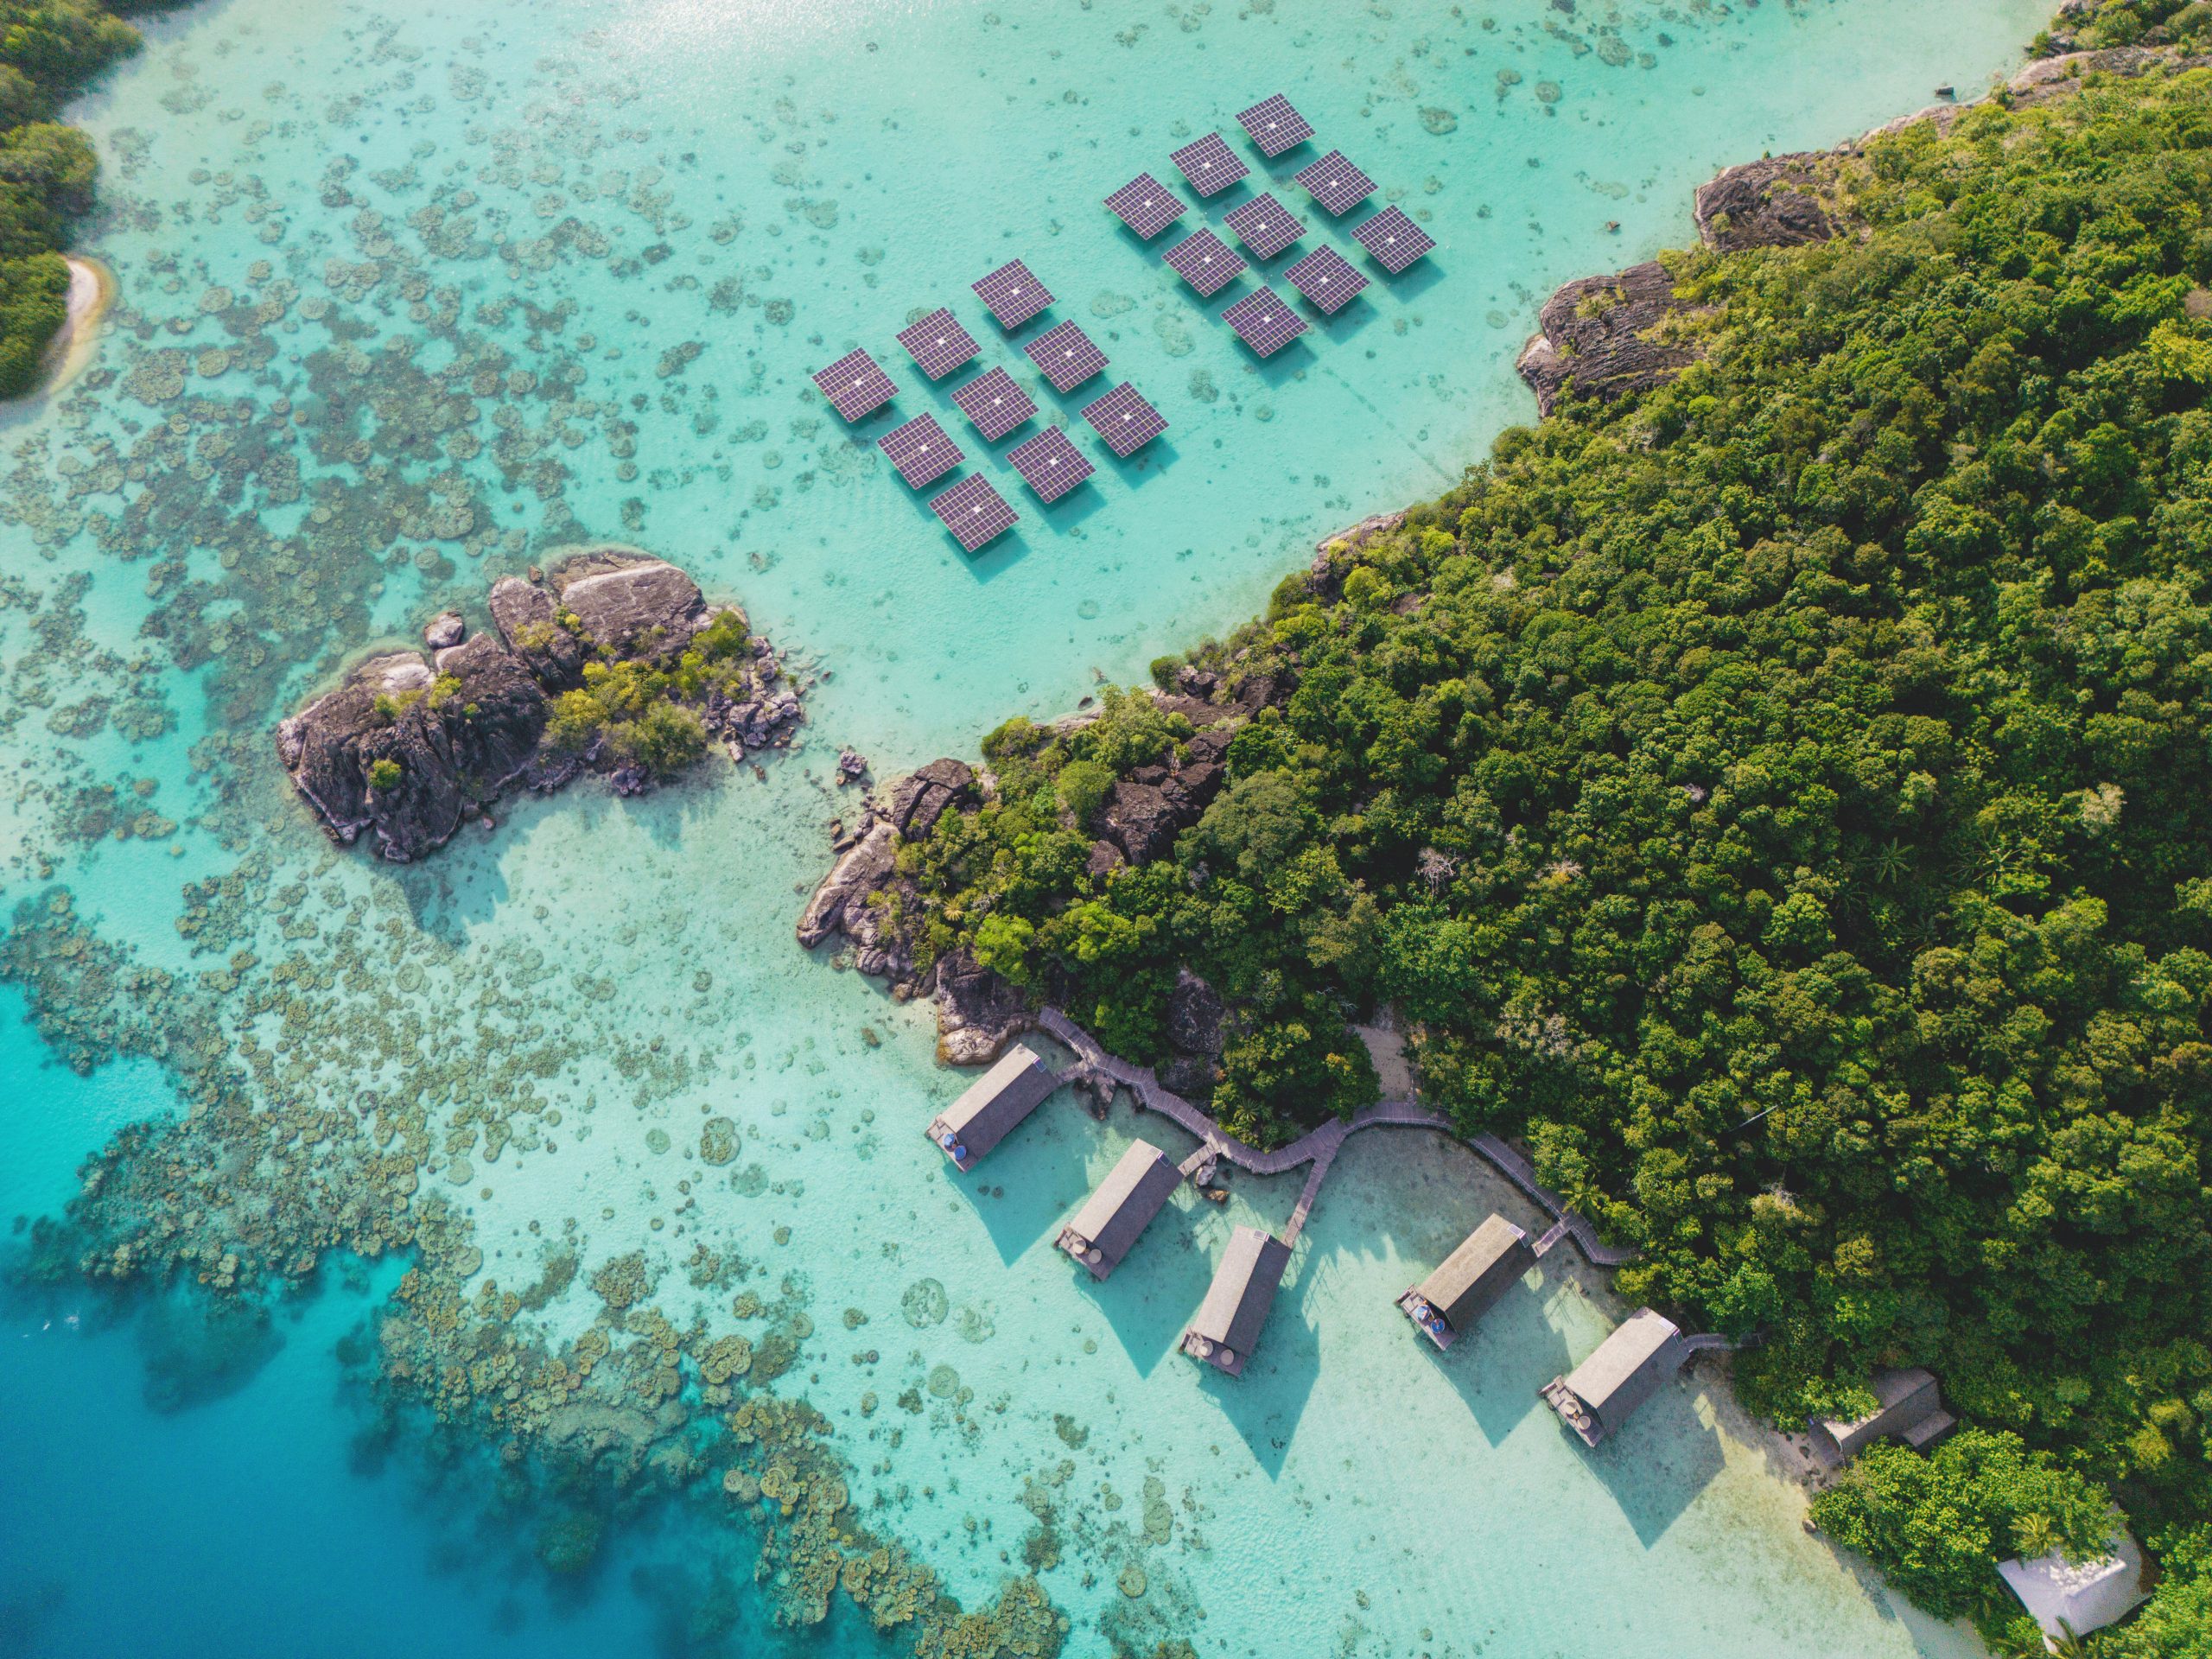
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.
As interest rates, inflation and market sentiment fluctuate, investors are being urged to focus on data, not panic.