Why Inflation Erupted: Two Top Economists Have the Answer
Former Fed chair, IMF chief economist say it wasn’t pandemic or stimulus; it was the pandemic, then the stimulus

 4 min
For two years debate has raged over what caused the highest inflation since the 1980s: government stimulus or pandemic-related disruptions.
Now two of the country’s top economists have an answer: It’s both. Pandemic-related supply shocks explain why inflation shot up in 2021. An economy overheated by fiscal stimulus and low interest rates explain why it has stayed high ever since. The conclusion: For inflation to fade, the economy has to cool off, which means a weaker labour market.
The study, released Tuesday, is by Ben Bernanke, former chair of the Federal Reserve, and Olivier Blanchard, former chief economist of the International Monetary Fund. Bernanke is now at the Brookings Institution and Blanchard is at the Peterson Institute for International Economics. The two are among the world’s most cited academic economists.
When Congress passed President Biden’s $1.9 trillion American Rescue Plan in early 2021, which included checks to households, enhanced jobless benefits and aid to state and local governments, inflation was around 2% and unemployment, though coming down, still above 6%.
At the time many forecasters thought the stimulus could push demand above the economy’s potential to supply goods and services and unemployment below its long-run natural rate of around 4%. Yet few thought this would meaningfully raise inflation. In previous decades unemployment had remained similarly low without raising price pressures.
A few disagreed, notably former Treasury Secretary Lawrence Summers and Blanchard. Both warned the stimulus was so large it would push the economy dangerously into overheating territory.
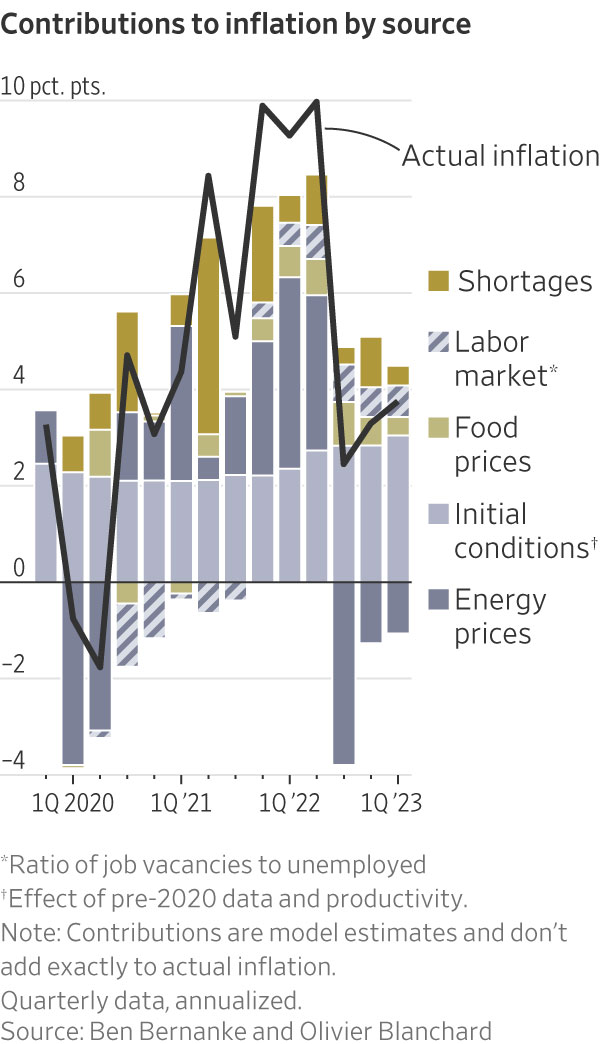
Not the inflation critics expected
Inflation did shoot up, hitting 7% that December, 5.5% excluding food and energy. “The critics’ forecasts of higher inflation would prove to be correct—indeed, even too optimistic—but, in substantial part, the sources of the inflation would prove to be different from those they warned about,” Blanchard, one of those critics, and Bernanke write in their study.
To tease out the sources of inflation, Bernanke and Blanchard build a relatively conventional model in which inflation is a function of, among other things, the gap between the supply and demand for labor, the public’s expectations of inflation, and commodity prices. They include a variable for supply-chain disruptions derived from Google searches for “shortage.”
Usually economists judge labor market tightness from how far unemployment is above or below its natural rate. But this time the labor market heated up before unemployment got that low. So instead, Bernanke and Blanchard use the ratio of job vacancies to unemployed workers. Finally, their model lets all these factors interact, with varying lags.
If stimulus had overheated the economy, it should have shown up in the labor market, i.e., an unusually high ratio of vacancies to unemployed. In fact, labor market conditions put downward pressure on inflation through the third quarter of 2021, the authors concluded. Instead, the inflation that year was driven almost entirely by shortages and energy prices. (To be sure, many shortages reflected restricted supply interacting with demand boosted by stimulus.)
Demand shifted abruptly from services to goods in the early months of the pandemic. The overall effect should have been a wash as prices rose for goods and fell for services. It wasn’t, because goods producers faced supply constraints, which caused costs and prices to spike, while costs to service producers didn’t decline much. “These sectoral mismatches between demand and supply proved more intractable and longer-lasting than many had expected,” the authors note.
The legacy of stimulus
These pandemic disruptions did eventually subside. Why didn’t inflation then fall? The reason, the authors conclude, is that by this point demand was so strong, reflecting the legacy of low interest rates and fiscal largess, the labor market was significantly overheated with the ratio of vacancies to unemployed up dramatically. Moreover, the initial surge of inflation had an echo: It lifted workers’ expectations of short-term inflation, which then partly found its way into their wages.
If anything, the study might understate the effect of pandemic disruptions. The labor market didn’t just overheat because of excess demand, but reduced supply, as well. The rising ratio of vacancies to unemployed, which the model equates with a tighter labor market, reflects employers struggling to fill vacancies. The authors note much of that struggle was because of the pandemic: Firms that had laid off employees had to find new ones, while some workers left the labor force because of family obligations, illness or work-life balance priorities.
This decline in supply-side potential hasn’t gotten much attention in the inflation debate, but its role could be significant. John Williams, president of the Federal Reserve Bank of New York, last week estimated that potential was 4.2% lower at the end of 2022 than its pre pandemic trend.
That stimulus wasn’t the inflation culprit it is often made out to be doesn’t entirely absolve the Fed and Biden. Arguably, they should have anticipated supply disruptions would amplify the risks of stoking demand. In 2020 the Fed introduced a new framework and guidance under which interest rates would stay near zero until maximum employment was restored, even if inflation topped its 2% target. That “contributed to delayed action and the inflation overshoot,” former Fed Vice Chair Donald Kohn and Brown University economist Gauti B. Eggertsson say in another paper to be presented Tuesday.
Bernanke and Blanchard conclude that because inflation today reflects a too-hot labor market, the solution is to cool it off. To bring inflation back to the Fed’s target, they estimate unemployment would have to rise above 4.3% from its current 3.4% assuming vacancies remain difficult to fill. But, they say, inflation could drop without a significant increase in unemployment if the ease of hiring returns to pre pandemic norms. The good news: There are tentative signs that is happening.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min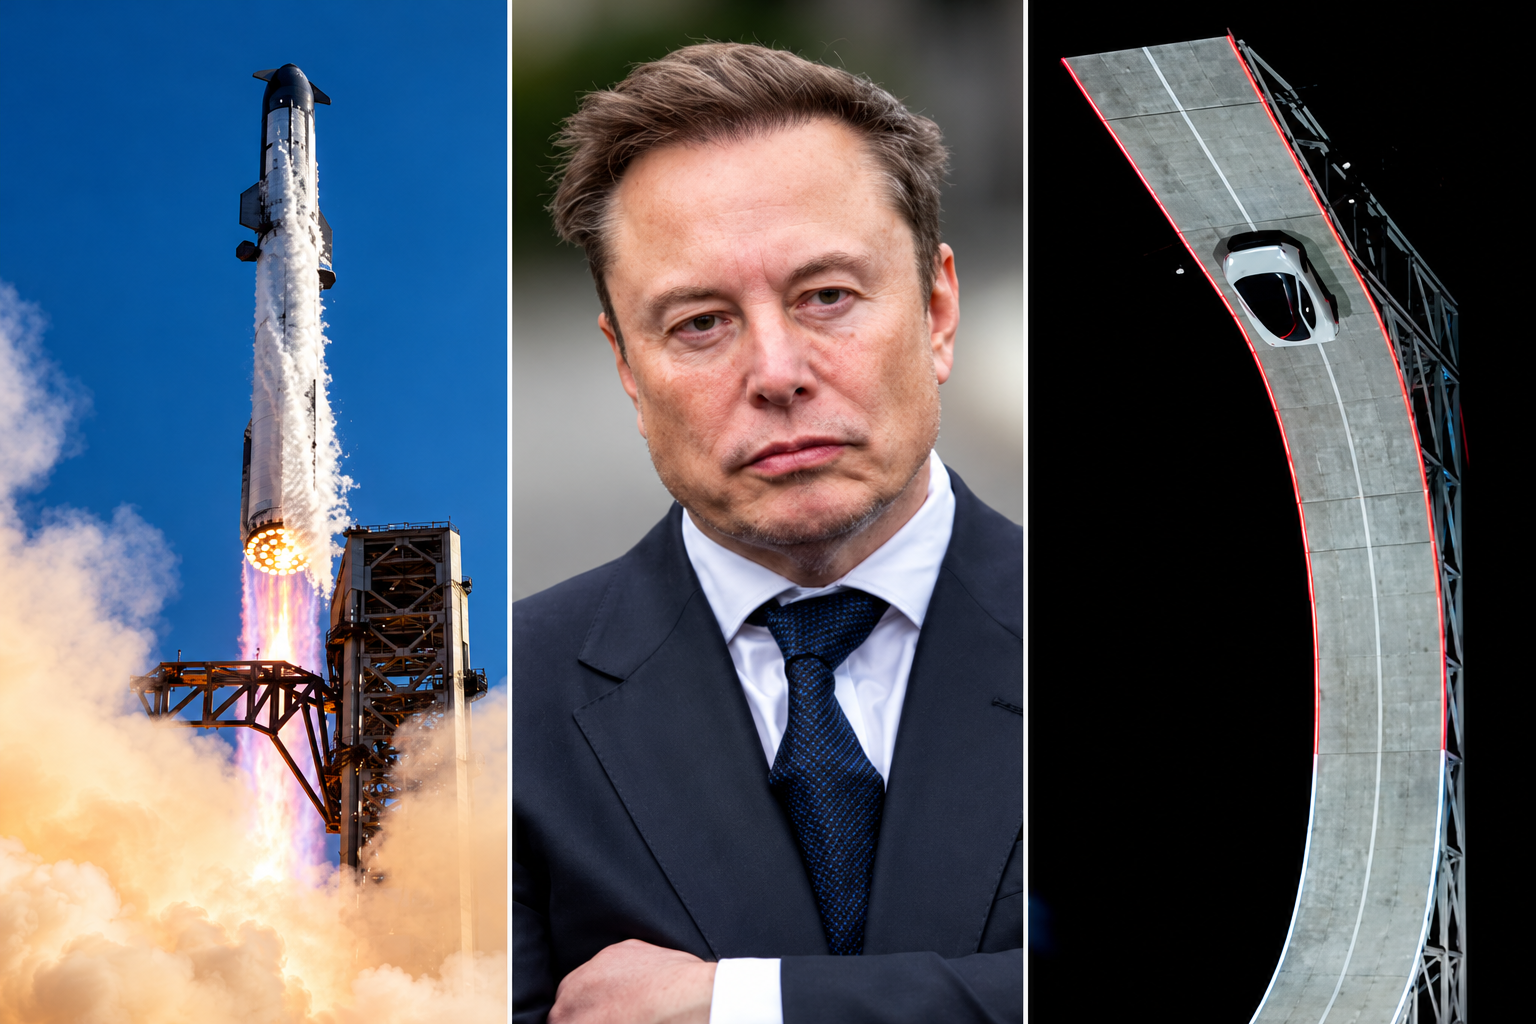
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
Ophora Tallawong has launched its final release of quality apartments priced under $700,000.
Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices