Australians Say Home Ownership Means Happiness
A new report shows 70 percent of Australians feel that owning a home contributes to their personal happiness in life.
 2 min
Most Australians feel that home ownership is important for their overall happiness, providing not only a sense of financial security but also contributing to their emotional wellbeing. Those are the findings of a research report undertaken by the customer-owned Great Southern Bank.
The research contains insights from almost 2,000 Australians on how they’re feeling about their current living situation. It found homeowners are significantly happier with their homes than renters, and the more equity they have in their homes, the happier they feel. Happiness is highest for mortgage-free homeowners, with 57 percent saying they were ‘very happy’ compared to 45 percent of homeowners with a mortgage and 29 percent of long-term renters.
Megan Keleher, Chief Customer Officer at Great Southern Bank, said: “What this report illustrates is the strong link between home ownership and happiness – in fact 7 out of 10 Australians say home ownership is important to their overall happiness,” Ms Keleher said. “Just 5 percent – or one in 20 – say it is not at all important. And perhaps not surprisingly, happiness with our home increases as we get older, and as we move towards becoming mortgage-free.”
The report found that 51 percent of renters are feeling heavily burdened by their financial commitments compared to 36 percent of homeowners. About 84 percent of long-term renters say they are concerned about current cost-of-living pressures compared to 73 percent of homeowners. And 80 percent are worried about housing affordability compared to 62 percent of owners.
Ms Kelaher said 29 percent of renters and 18 percent of long-term renters were still feeling confident that they could achieve their home ownership dreams. One in two renters said they were hopeful of buying a home to live in within the next three years, however saving a deposit is the key barrier.
“Of course, we acknowledge that the homeownership journey can be difficult and one of the biggest challenges faced by first home buyers is saving a deposit,” said Ms Keleher. “For those buyers who are finding it difficult to save a deposit, there is support available from several government initiatives. For instance, the Federal Government Home Guarantee Scheme’s expanded eligibility criteria is helping more first-time buyers, as well as those who haven’t owned a home for many years.”
One in 10 respondents who had previously planned to buy a home are now holding off, saying they feel deterred by rising property prices (60 percent), the cost of living (60 percent) or rising interest rates (45 percent). New CoreLogic data shows the national home value rose by 8.1 percent in 2023. Meantime, interest rates have risen dramatically since May 2022 from an emergency low of 0.1 percent to 4.35 percent today.
The report also asked respondents how satisfied they were with various elements of their homes, such as style and location.
About 72 percent of baby boomers were happy with their home’s location compared to 61 percent of Gen Xers, 58 percent of millennials and 48 percent of Gen Zs. About 62 percent of baby boomers liked the internal look and feel of their homes versus 51 percent of Gen Xers and 48 percent of both millennials and Gen Zs.
It appears many Australians are living in homes that are too big or small for them, with the size of homes recording some of the lowest satisfaction scores. Just 65 percent of baby boomers are happy with the size of their homes compared to 48 percent of Gen Xers, 42 percent of millennials and 40 percent of Gen Zs.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.
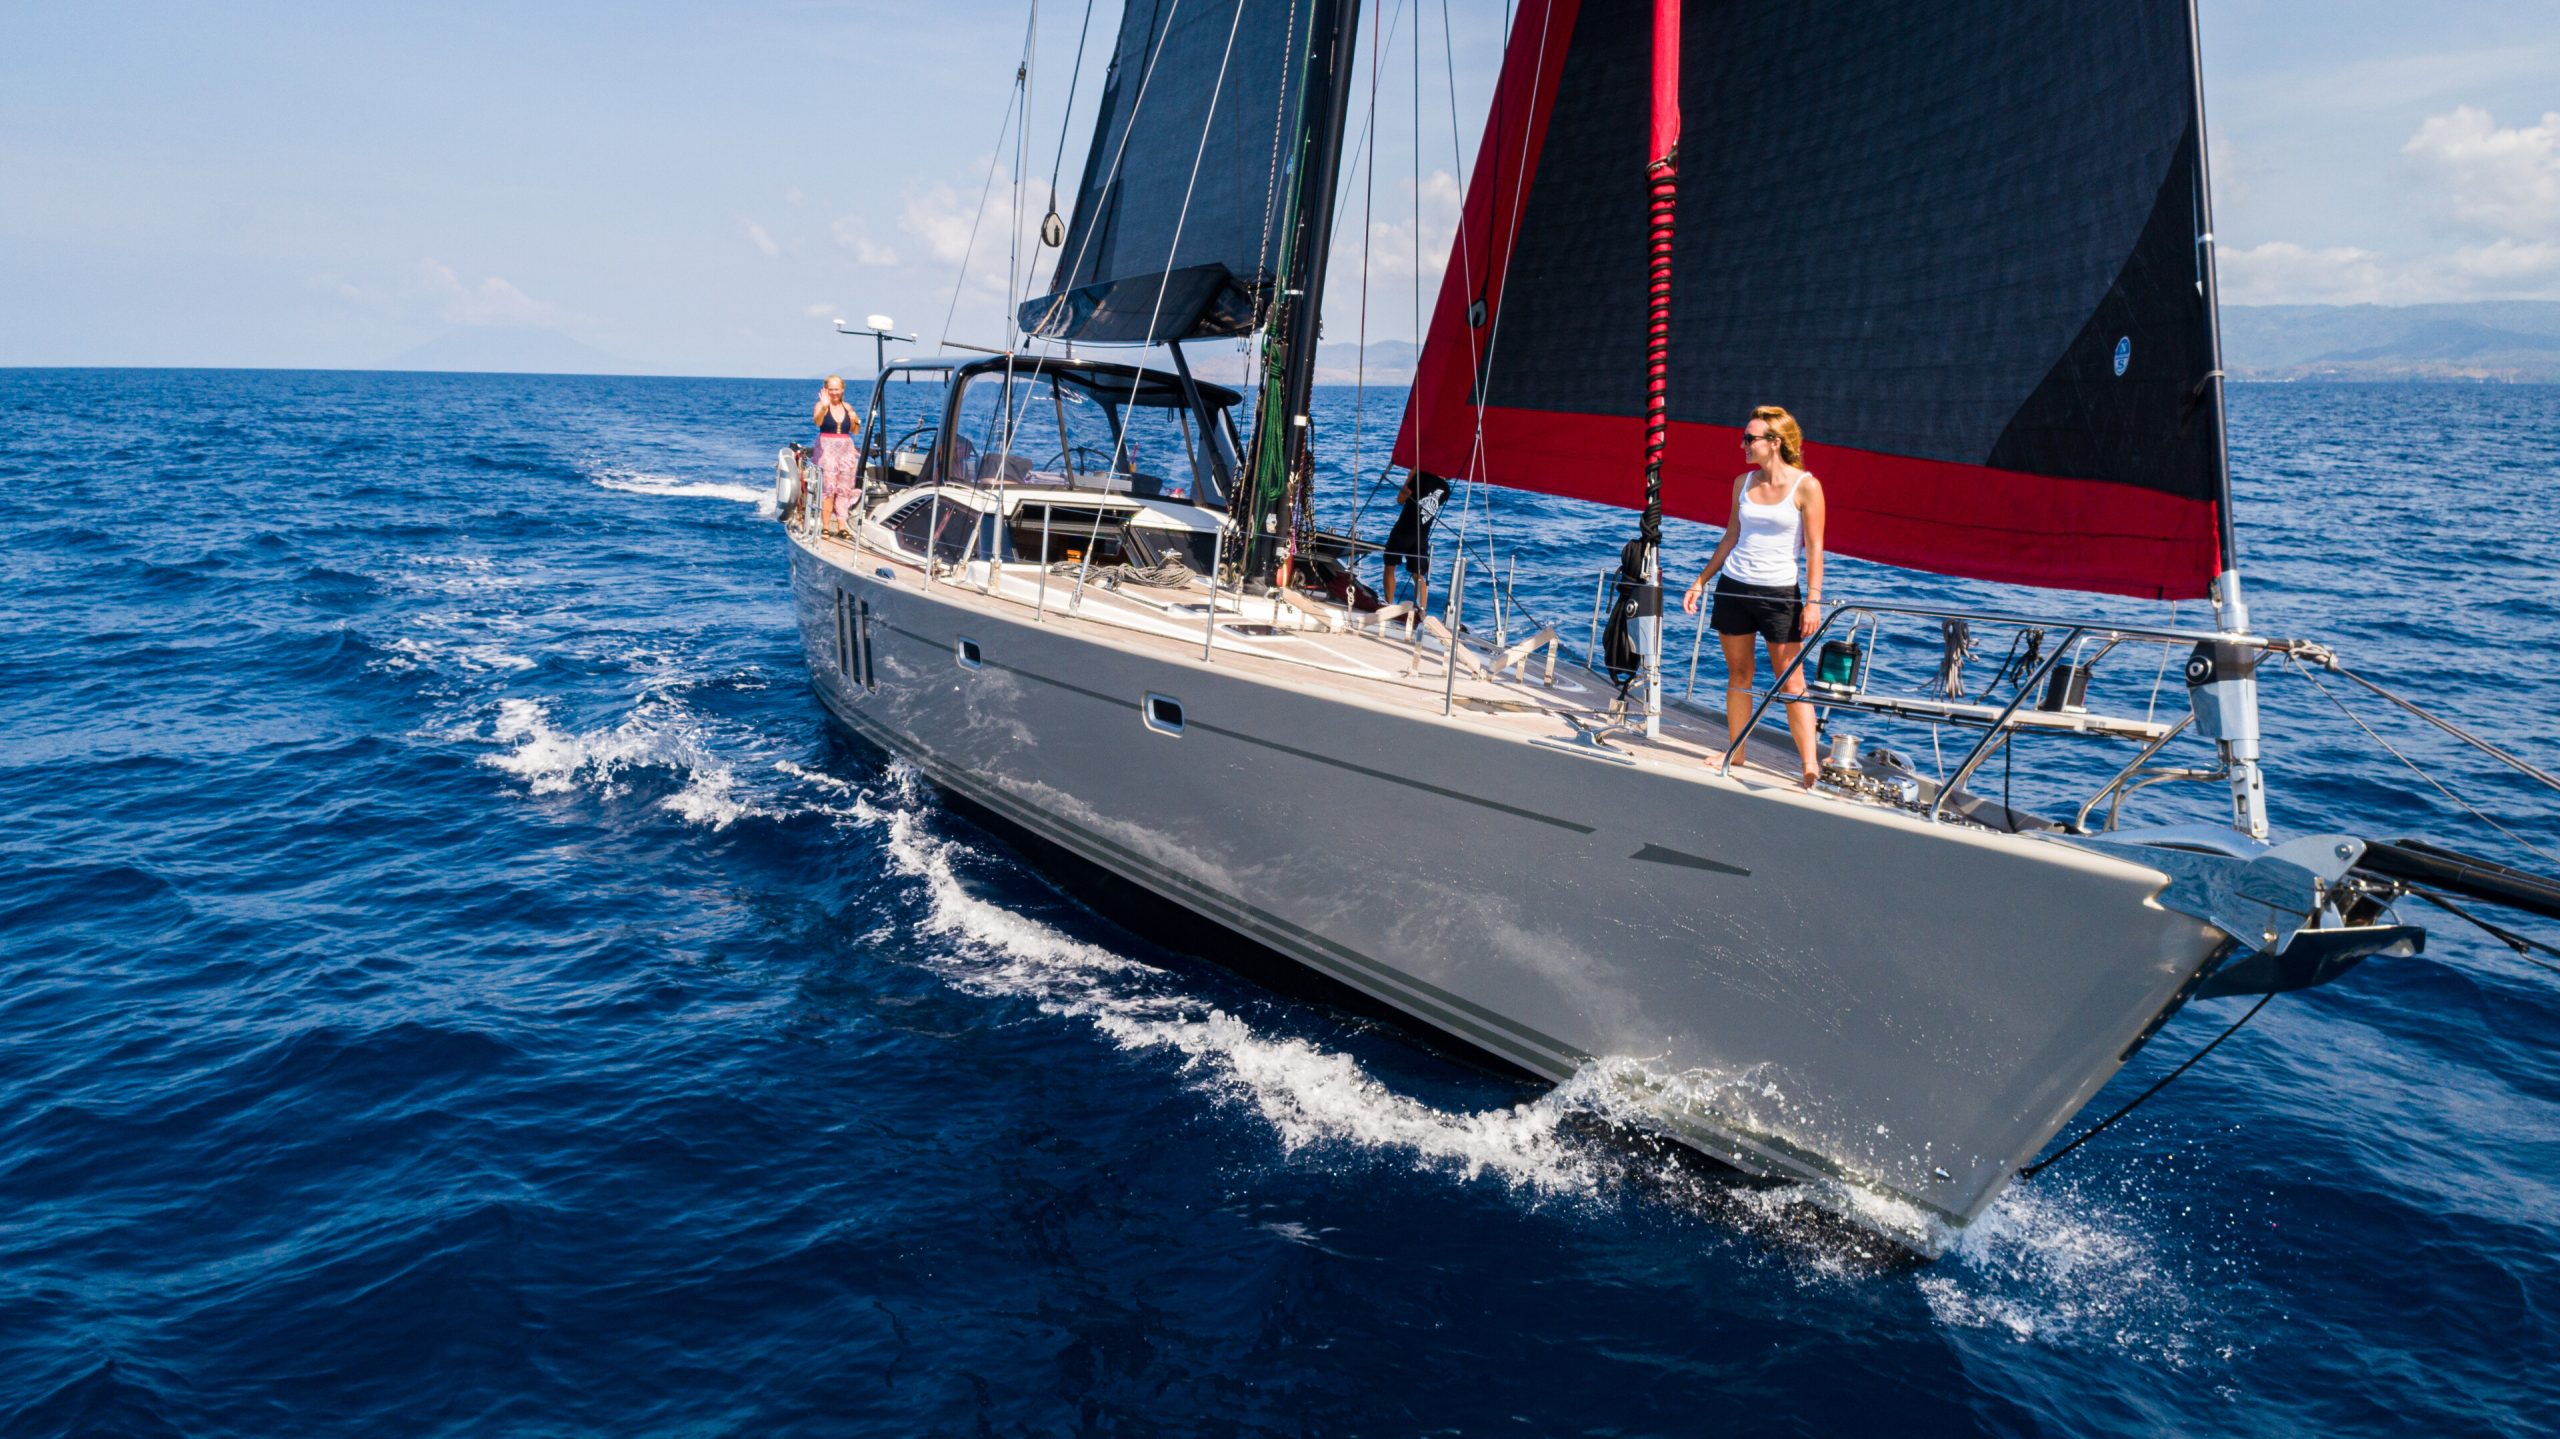
From the Caribbean to Australia’s east coast, Oyster’s latest world rally promises a bluewater voyage designed for owners seeking ultimate sailing experiences.
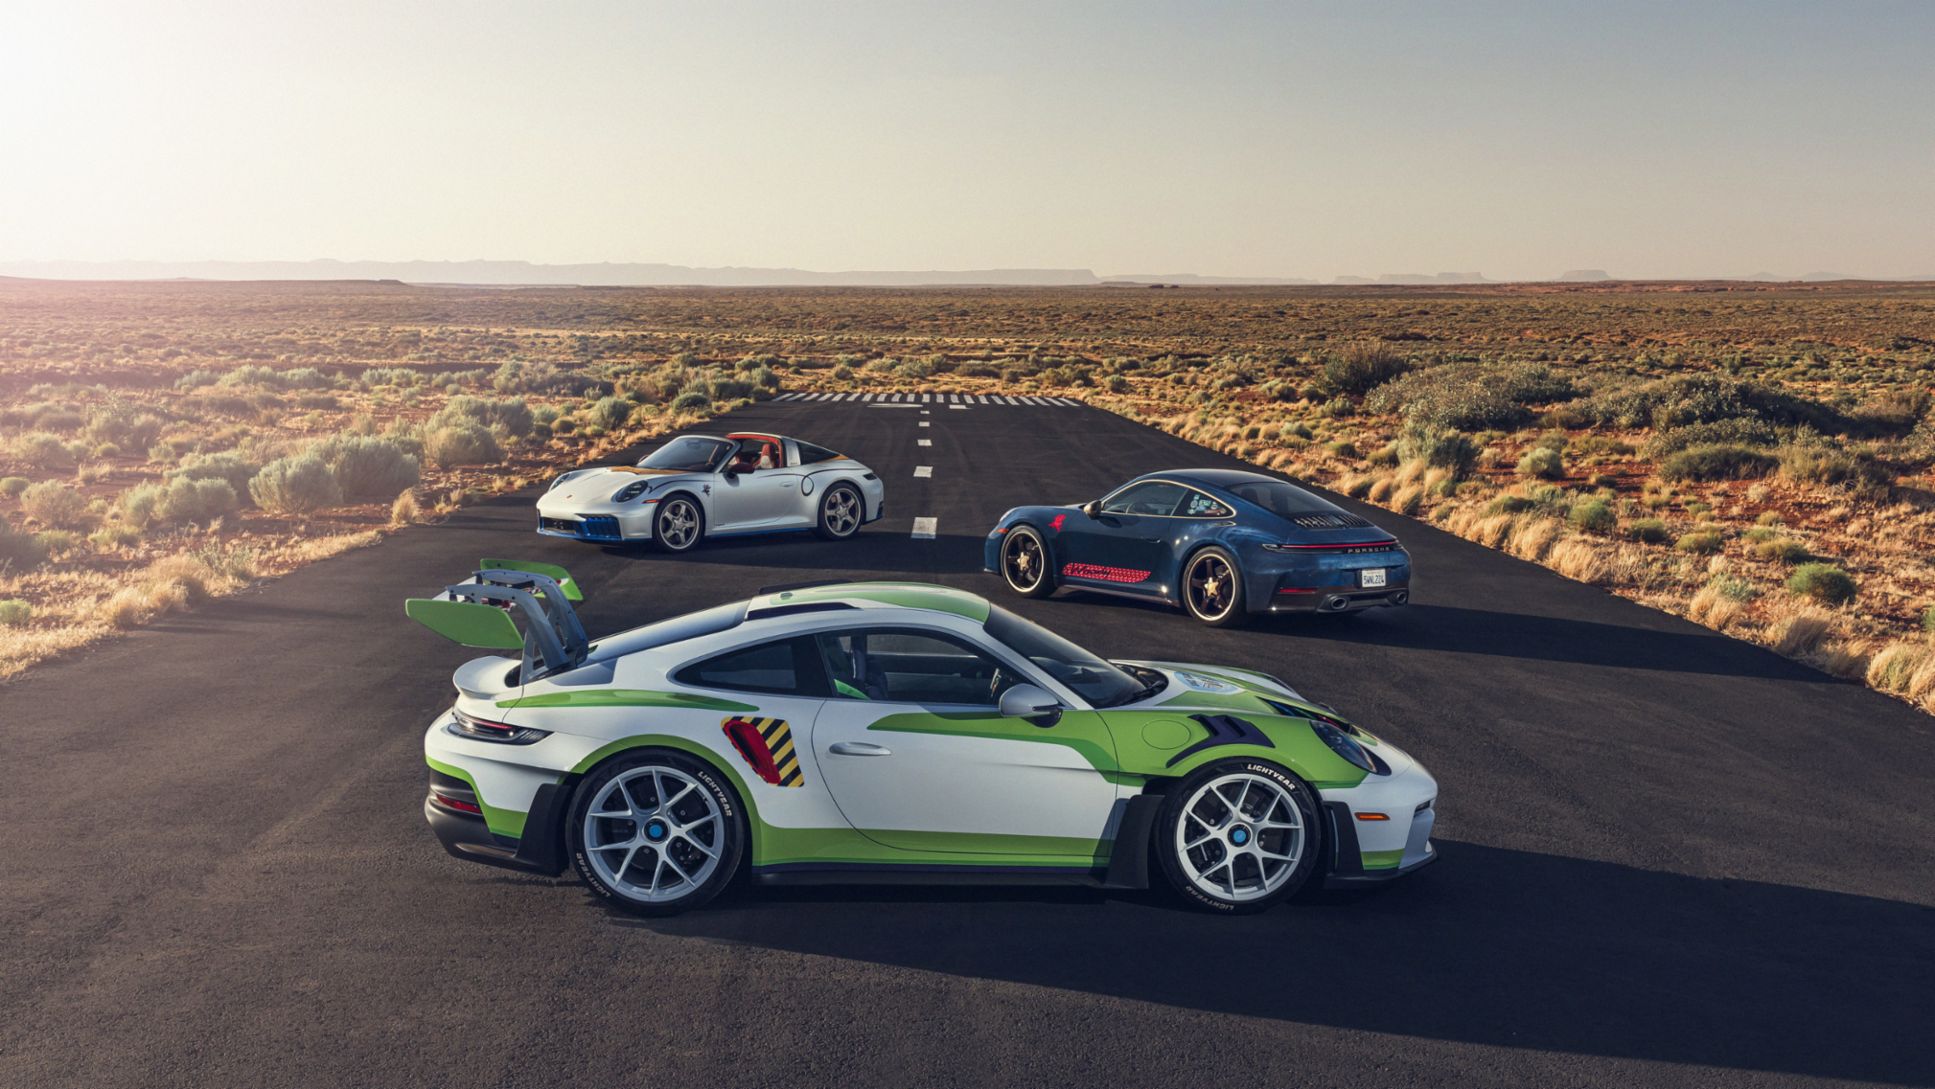
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation