John McGrath’s Best Suburb Selections for 2025: Where to Invest Next
A new market cycle is commencing as prices rebound in almost every market this Spring
 3 min
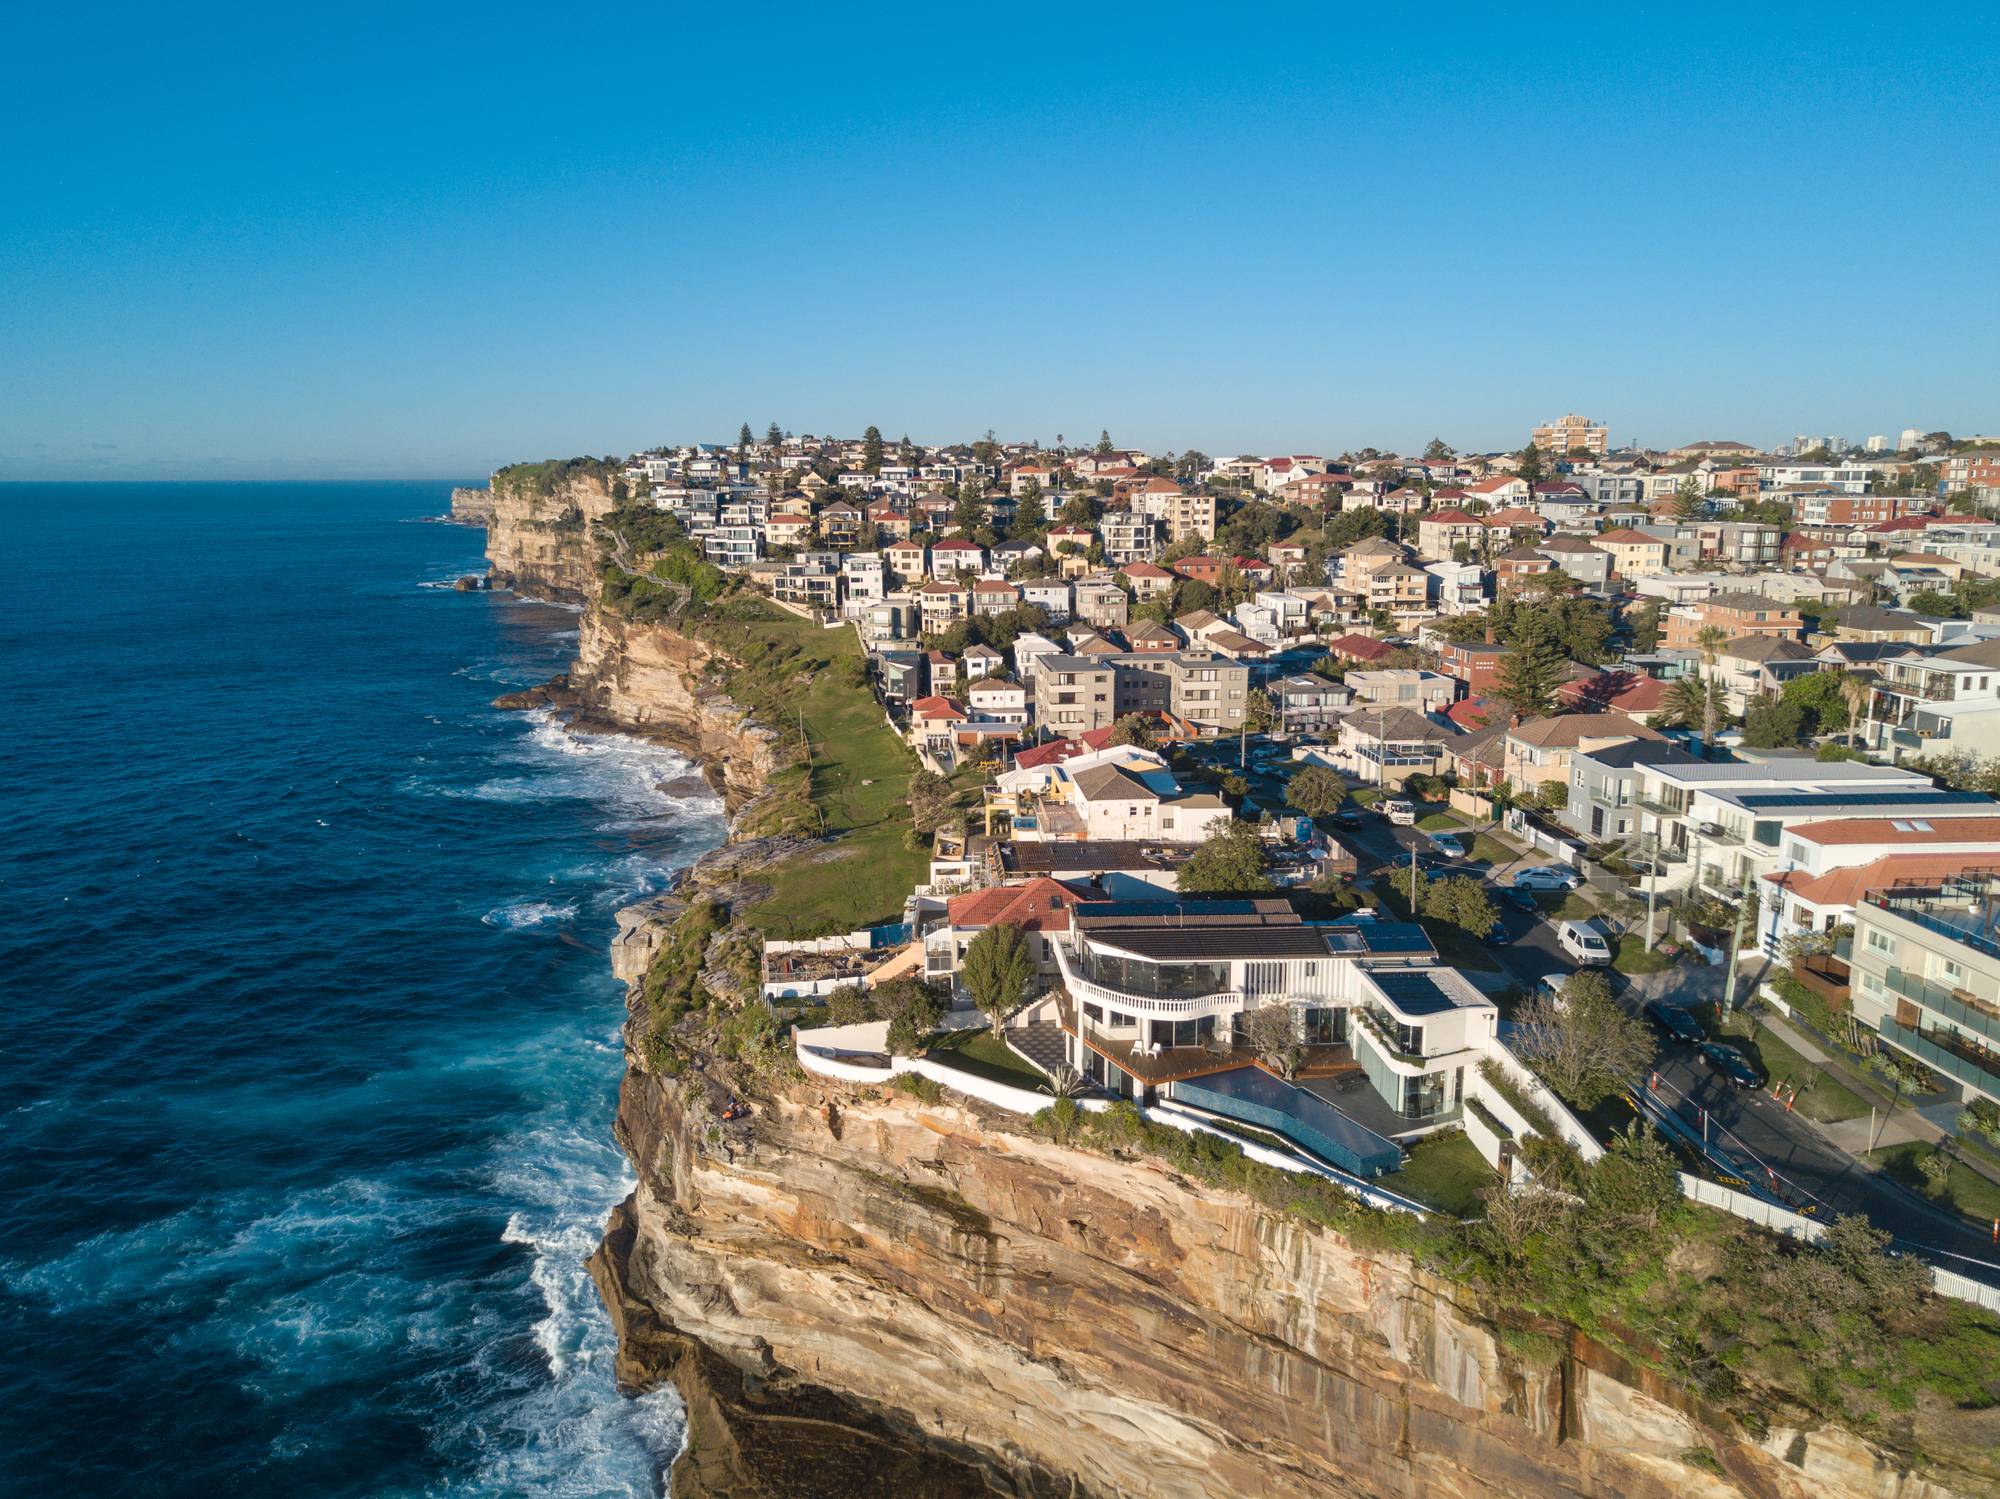
Australian property industry veteran, John McGrath says the next major market upswing is “just over the horizon” amid strong auction clearance rates this Spring and rebounding prices in many areas.
Mr McGrath says he expects greater market activity in 2024 as inflation continues to trend down, thereby bringing an end to the fastest interest rate hiking cycle in decades.
McGrath has just released its annual market report, in which Mr McGrath names his top suburb picks for 2024 across the East Coast of Australia and why these areas are poised for price growth.
Kanebridge News profiles 10 of Mr McGrath’s top suburb picks for 2024 below.
Fairfield, Sydney
Fairfield is one of Australia’s most multicultural communities, making it an attractive place to settle for some of the 715,000 net migrants expected to arrive in Australia over the next two years.
Mr McGrath says the Western Sydney International Airport will create a new local jobs hub when it opens in 2026. He notes that significant medium-density development “has led to affordable homeownership opportunities” for younger buyers, with the median apartment price just $410,000.
Chifley, Sydney
Mr McGrath says Chifley offers a great outdoorsy lifestyle with close proximity to national parks and reserves, walking trails, sports fields, an equestrian club and several golf clubs.
“The neighbourhood has had a facelift in recent years, with young family buyers replacing original houses with new, contemporary residences,” he says. “There is also a much higher-than-average number of semis and townhouses in Chifley, providing more affordable options for buyers.”
Point Cook, Melbourne
Point Cook is a well-established suburb that is packed with amenities and offers great value, with a median house price of $760,000, according to Mr McGrath.
“Prices have remained resilient during the recent downturn, and rents have grown strongly in the past year,” he said. “The suburb … has a good mix of housing stock and its proximity to the water is a big drawcard for residents.”
Spotswood, Melbourne
Spotswood has flown under the radar in the shadow of neighbouring hotspots Seddon and Yarraville, says Mr McGrath.
He points out that Spotswood has a solid track record of price growth and “strong growth fundamentals” for the future, including an expanding dining scene and good road and rail links.
Mansfield, regional Victoria
Mansfield was an extremely popular treechange destination during the pandemic, when many people left Melbourne and moved to the regions because they were able to work remotely.
Mr McGrath says there is still room for Mansfield home values to grow further, pointing out that “price growth has not yet reached the heights of high country lifestyle locations like Bright”.
Clontarf, Brisbane
Located at the southern end of the Redcliffe Peninsula, Mr McGrath says Clontarf was one of the top growth suburbs in the Moreton Bay region in 2023. He says the suburb is highly desirable among family buyers due to its transport links to Brisbane, sprawling beaches and waterfront parks.
Southport, Gold Coast
Southport offers a more affordable price point but the same attractive lifestyle amenities as Broadbeach, Burleigh Heads and Palm Beach. “The plethora of high rises here makes it an attractive option for those who like to live close to the action,” Mr McGrath says.
Coolum Beach, Sunshine Coast
Mr McGrath says Coolum Beach is known for some of the most consistent waves for surfers on the coast. He says the suburb is popular with family buyers and couples and sits in a central location within an easy drive of Sunshine Coast Airport and only 20 minutes south of Noosa Heads.
Moonah, Hobart
About 5km north of Hobart’s city centre, Mr McGrath says Moonah is “an up-and-coming suburb where you can still find houses for less than $650,000.”
He adds: “Its affordability and wide quiet streets make it a magnet for young families, as well as those buying their first home. Another drawcard is its thriving food scene clustered around Main Road, with renowned restaurants like St Albi.”
Riverside, Launceston
On the banks of the Tamar River about 4km from the CBD, Riverside is appealing to family buyers due to its proximity to the city and four local schools.
Mr McGrath says the Riverside market provides the opportunity to buy homes with water views, or homes on larger parcels of land a bit further out where many residents keep horses and chickens.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.

An opulent Ryde home, packed with cinema, pool, sauna and more, is hitting the auction block with a $1 reserve.

Micro-needling promises glow and firmness, but timing can make all the difference.