

Need More Closet Space? 6 Chic Interior Design Solutions
If your bedroom has too little (or no) storage for clothes, you can end up living in a stressful mess. Here, pros offer clever, great-looking ways around the problem.

 4 min

In the series How to Live With a Room You Hate, we ask design pros to solve everyday interior problems.
A ROOM with little or no closet space can leave you feeling bulldozed by your own belongings. “It’s unsettling when nothing has a home. Creating a system that maximizes your space can change your whole mood,” said Jamie Garson of Better Than B4, a custom organizing service in Manhattan. Here, six stuff-stowing techniques that offer relief when a bedroom is bereft of storage.
1. Increase Your Screen Time
When Gavin Smith, an architect with Perkins + Will, turned an attic space in his 1910 Craftsman home in Seattle into a bedroom for himself and his wife, he wanted to leave the space open and airy. So rather than building a traditional closet, he constructed cabinetry and clothing racks under the cathedral ceiling and shielded them behind a peek-a-boo screen of cedar slats supported by chic, blackened steel. “A solid drywall would be perceived very differently,” he said. “Because the screen is see-through, it creates a sense of depth.” Smith gave the partition—which also serves as a place to hang a flat-screen TV—a walnut stain to match a nearby dresser. If you want to skip construction, suggests Garson, tuck belongings behind a standing room divider.
2. Play Dress-Up
Interior designer Emilie Jacob gave a closet-less child’s bedroom in Dubai a clever theatrical fix by installing rods to hang clothing, many at a low level, and suspending drapes that, with a pull, can hide them on a whim. The drapes delineate a dressing area that lets the little girl don her duds in privacy. The curtains begin where a modular IKEA bed with underbed storage and attached wardrobe leaves off. “The linen curtains are really light, and there are no cords,” said Jacob, who founded local design firm Stella + the Stars and collaborated with Studio Tsubi, also in Dubai, on the room. “Any child can pull them open or closed.”
3. Broker a Separate Piece
When bad luck or circumstance has robbed you of a closet, a free-standing wardrobe makes for a classic solution. One with many benefits, contends Russell Pinch, the owner of Pinch, a furniture and lighting design firm in London. “It’s an investment…but one you can take with you.”

And importing a wardrobe rather than constructing storage can be kinder to architecturally valuable spaces, like the bedroom in Pinch’s vacation home in Charente-Maritime, France, in an 18th-century structure that was originally a cow barn. “We wanted to preserve the….beautiful parquet floors and timbered ceilings,” he said. “A built-in would have dominated the architecture and reduced the size of the room.” The white wardrobe, which he designed, “is an elegant solution. It looks like plaster-relief work,” said Pinch. Next to the wardrobe a full-length mirror with drawers at the bottom offers additional storage and helps complete a dressing area.
4. Get a Side Hustle
In a London townhouse, local interior designer Andrea Benedettini fit a full-size bed into a relatively narrow room, and rather than flank it with nightstands used the tight space on either side to build matching full-height closets. Unwilling to forgo the benefits of traditional bedside tables, he hung sconces on the sides of the closets facing the bed and carved out niches (complete with concealed lighting) to create a ledge for a book, phone or water glass. “Simple design details like the niche elevate the design,” Benedettini said. “Applying a fabric to the closet door and bespoke bronze hardware helped create a calming and luxurious space.” A ceiling-height upholstered headboard bridges the closets, connecting them visually into a whole, so the bed appears to be tucked into its own soft alcove.
5. Let It Rock
According to organiser Garson, much of our wardrobes can live outside a closet quite nicely. She suggests openly displaying an amazing sneaker collection in a media unit, placing funky handbags on floating shelves or arranging hooks on a wall for an artful pattern of hats or scarves.
6. Let It Roll
For a bedroom with no closet, Hilary Matt lets it all hang out with a rolling rack for clothes. The trick to exhibiting your wardrobe (warning: this is not for slobs)? “Keep the [rest of the] décor clean and monochromatic so the room doesn’t feel cluttered,” said the Manhattan interior designer.

The pop of colour from the apparel, which needs to be well-organized, adds to the room’s scheme “like a piece of art,” she said. Organiser Garson favours racks that match the style of the room, whether made of a fun acrylic or the more-masculine matte black metal.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


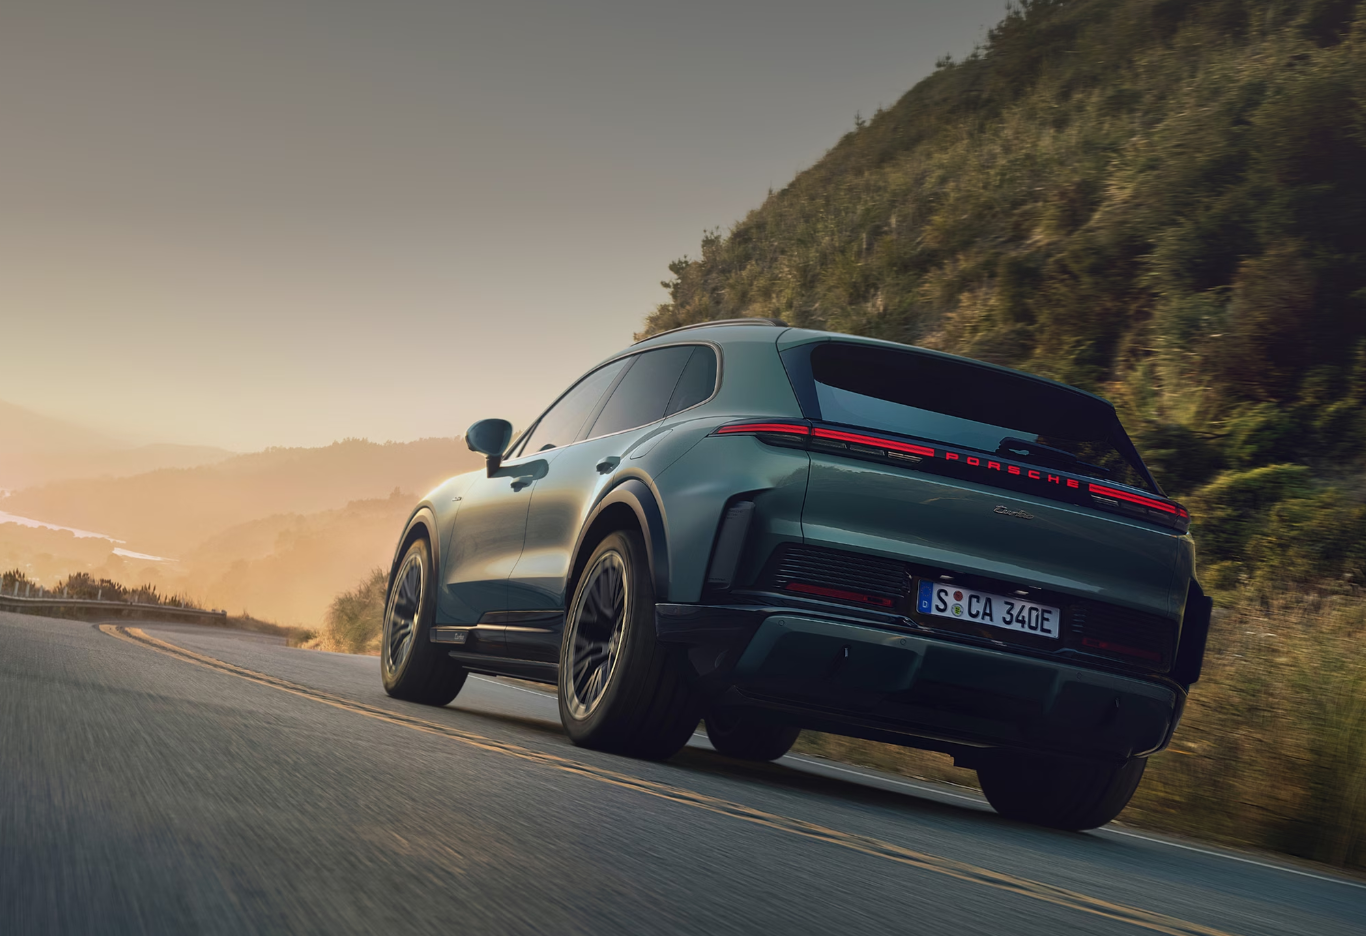
Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.
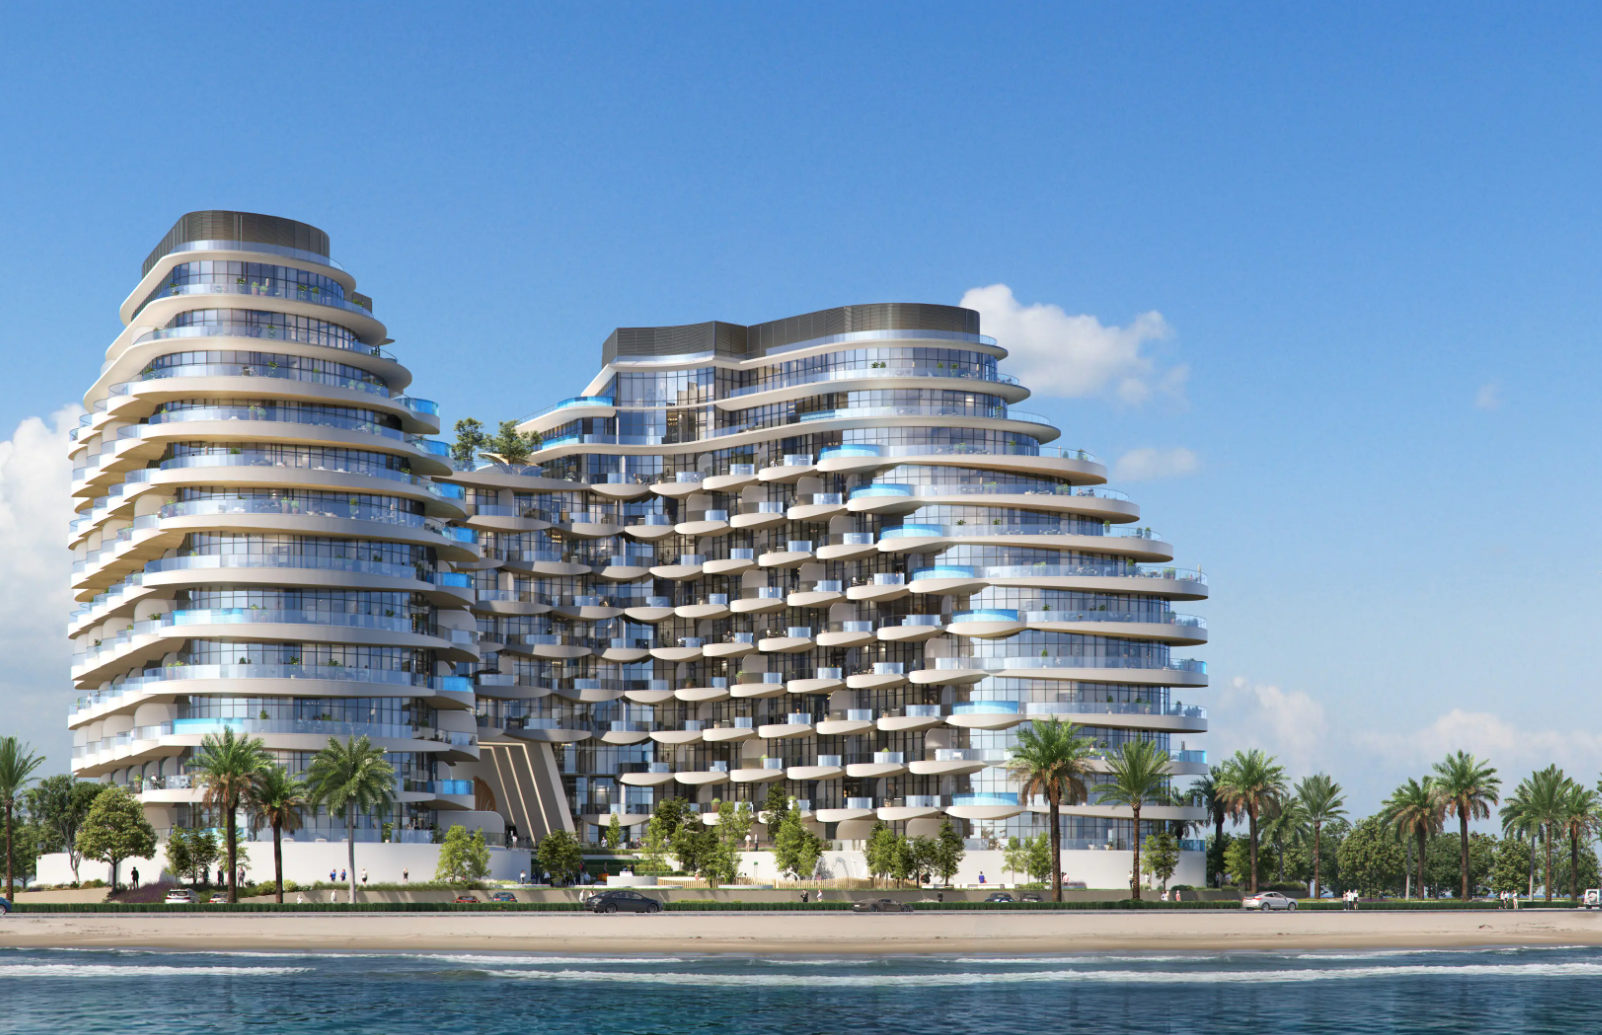
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
As interest rates, inflation and market sentiment fluctuate, investors are being urged to focus on data, not panic.
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.