Preeminent Expert Reveals 2024 Housing Market Predictions
Sydney and Melbourne likely to fall, Perth and Brisbane set to rise amid improved iron ore demand from China
 3 min
The Australian housing market will deliver a mixed performance in 2024, with Sydney and Melbourne home values likely to fall and Brisbane and Perth prices likely to rise. That’s according to Louis Christopher, the Head of Research at SQM Research and one of Australia’s preeminent experts on property prices, who has just released his annual Housing Boom and Bust Report 2024.
Mr Christopher has outlined his base case for property prices next year based on a cash rate of between 4.1% and 5% (the Reserve Bank raised the rate to 4.35% this month), slower but still elevated annual population growth of 460,000 people or less, and the unemployment rate rising to between 4.5% and 5.5%. He also outlines what may happen in other scenarios, including a global energy crisis brought about by current events in the Middle East, and higher population growth above 500,000 people per year.
At a national level, Mr Christopher’s base case forecasts a -1% to 3% price movement across the weighted combined capital cities. He explains: “… with expected slowing employment growth and the corresponding rise in unemployment, tipped to be towards 5% by the year end 2024, this negative will more than offset another year of strong migration. The interest rate rises of 2022, 2023 and possibly 2024 will finally start to bite homeowners and would-be homebuyers alike. Distressed selling activity is expected to jump, especially in NSW where we are already starting to see a new trend upwards in that data set.”
Looking at the cities individually, Mr Christopher forecasts a fall or very weak price growth in Sydney and Melbourne next year in his base case scenario. He tips a -4% to 0% price movement for Sydney and a -3% to +1% change in Melbourne. This would follow surprisingly strong price growth in Sydney this year despite interest rates still rising throughout 2023. Sydney dwelling values have lifted by an extraordinary 10.9% in the year to 31 October, while Melbourne home values have lifted 4%, according to the latest CoreLogic data.
Mr Christopher said continuing strong population growth (albeit lower than in 2023) and housing supply constraints will limit price falls in Australia’s two biggest cities. Historically, Sydney and Melbourne attract the lion’s share of migrants, so the significant current surge in international arrivals is likely to offset the affordability challenges created by a slower economy and 13 interest rate rises since May 2022, which have curtailed borrowing power and loan serviceability.
Christopher says home values will fall the most in Canberra, down between -8% to -4%, and Hobart, down between -7% to -3%. The combination of a fall in Federal Government spending plus an expected strong increase in dwelling completions will create a softer market in Canberra. The city is one of very few in Australia recording a lift in housing supply as the city embraces apartment living for the first time in its history. Known as the Garden City, Canberra is dominated by houses on family-sized blocks, but in recent years the ACT Government has gradually allowed for higher density stock, including dual occupancies on larger blocks and apartment buildings in major residential centres such as Belconnen and Woden.
On the other side of the coin, Mr Christopher predicts 5% to 9% price growth in Perth and 4% to 8% growth in Brisbane. He says these two cities are likely to benefit from tailwinds created by a recovering Chinese economy and an anticipated lift in demand for iron ore and other commodities. “Perth and Brisbane are still very likely to record price rises based on super tight rental conditions, a better-than-expected global commodities market and minimal exposure to the financial services sector, where we believe there maybe be significant job losses,” Mr Christopher said.
The bulk of Australia’s mines are located in Western Australia and Queensland, and fly-in, fly-out workers commonly base themselves and their families in the capital cities. The iron ore price closed at US$137.50 per tonne in overnight trading – its highest level since May 2022 – and is up almost 20% over the past month, according to Trading Economics data.
This is largely due to the Chinese Government announcing new stimulus targeting infrastructure and manufacturing to counter deflationary pressures in the economy. China imports 70% of the world’s annual iron ore supply, making it the biggest consumer globally, according to Federal Government data. Top broker Citi is forecasting the iron ore price to average US$140 per tonne over the next three months due to the anticipated higher Chinese demand.
Mr Christopher said property prices in Adelaide and Darwin are anticipated to remain steady or record a minor price rise or correction. The base case forecast is a 0% to 3% price movement in Adelaide and a -3% to +1% change in Darwin next year.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.
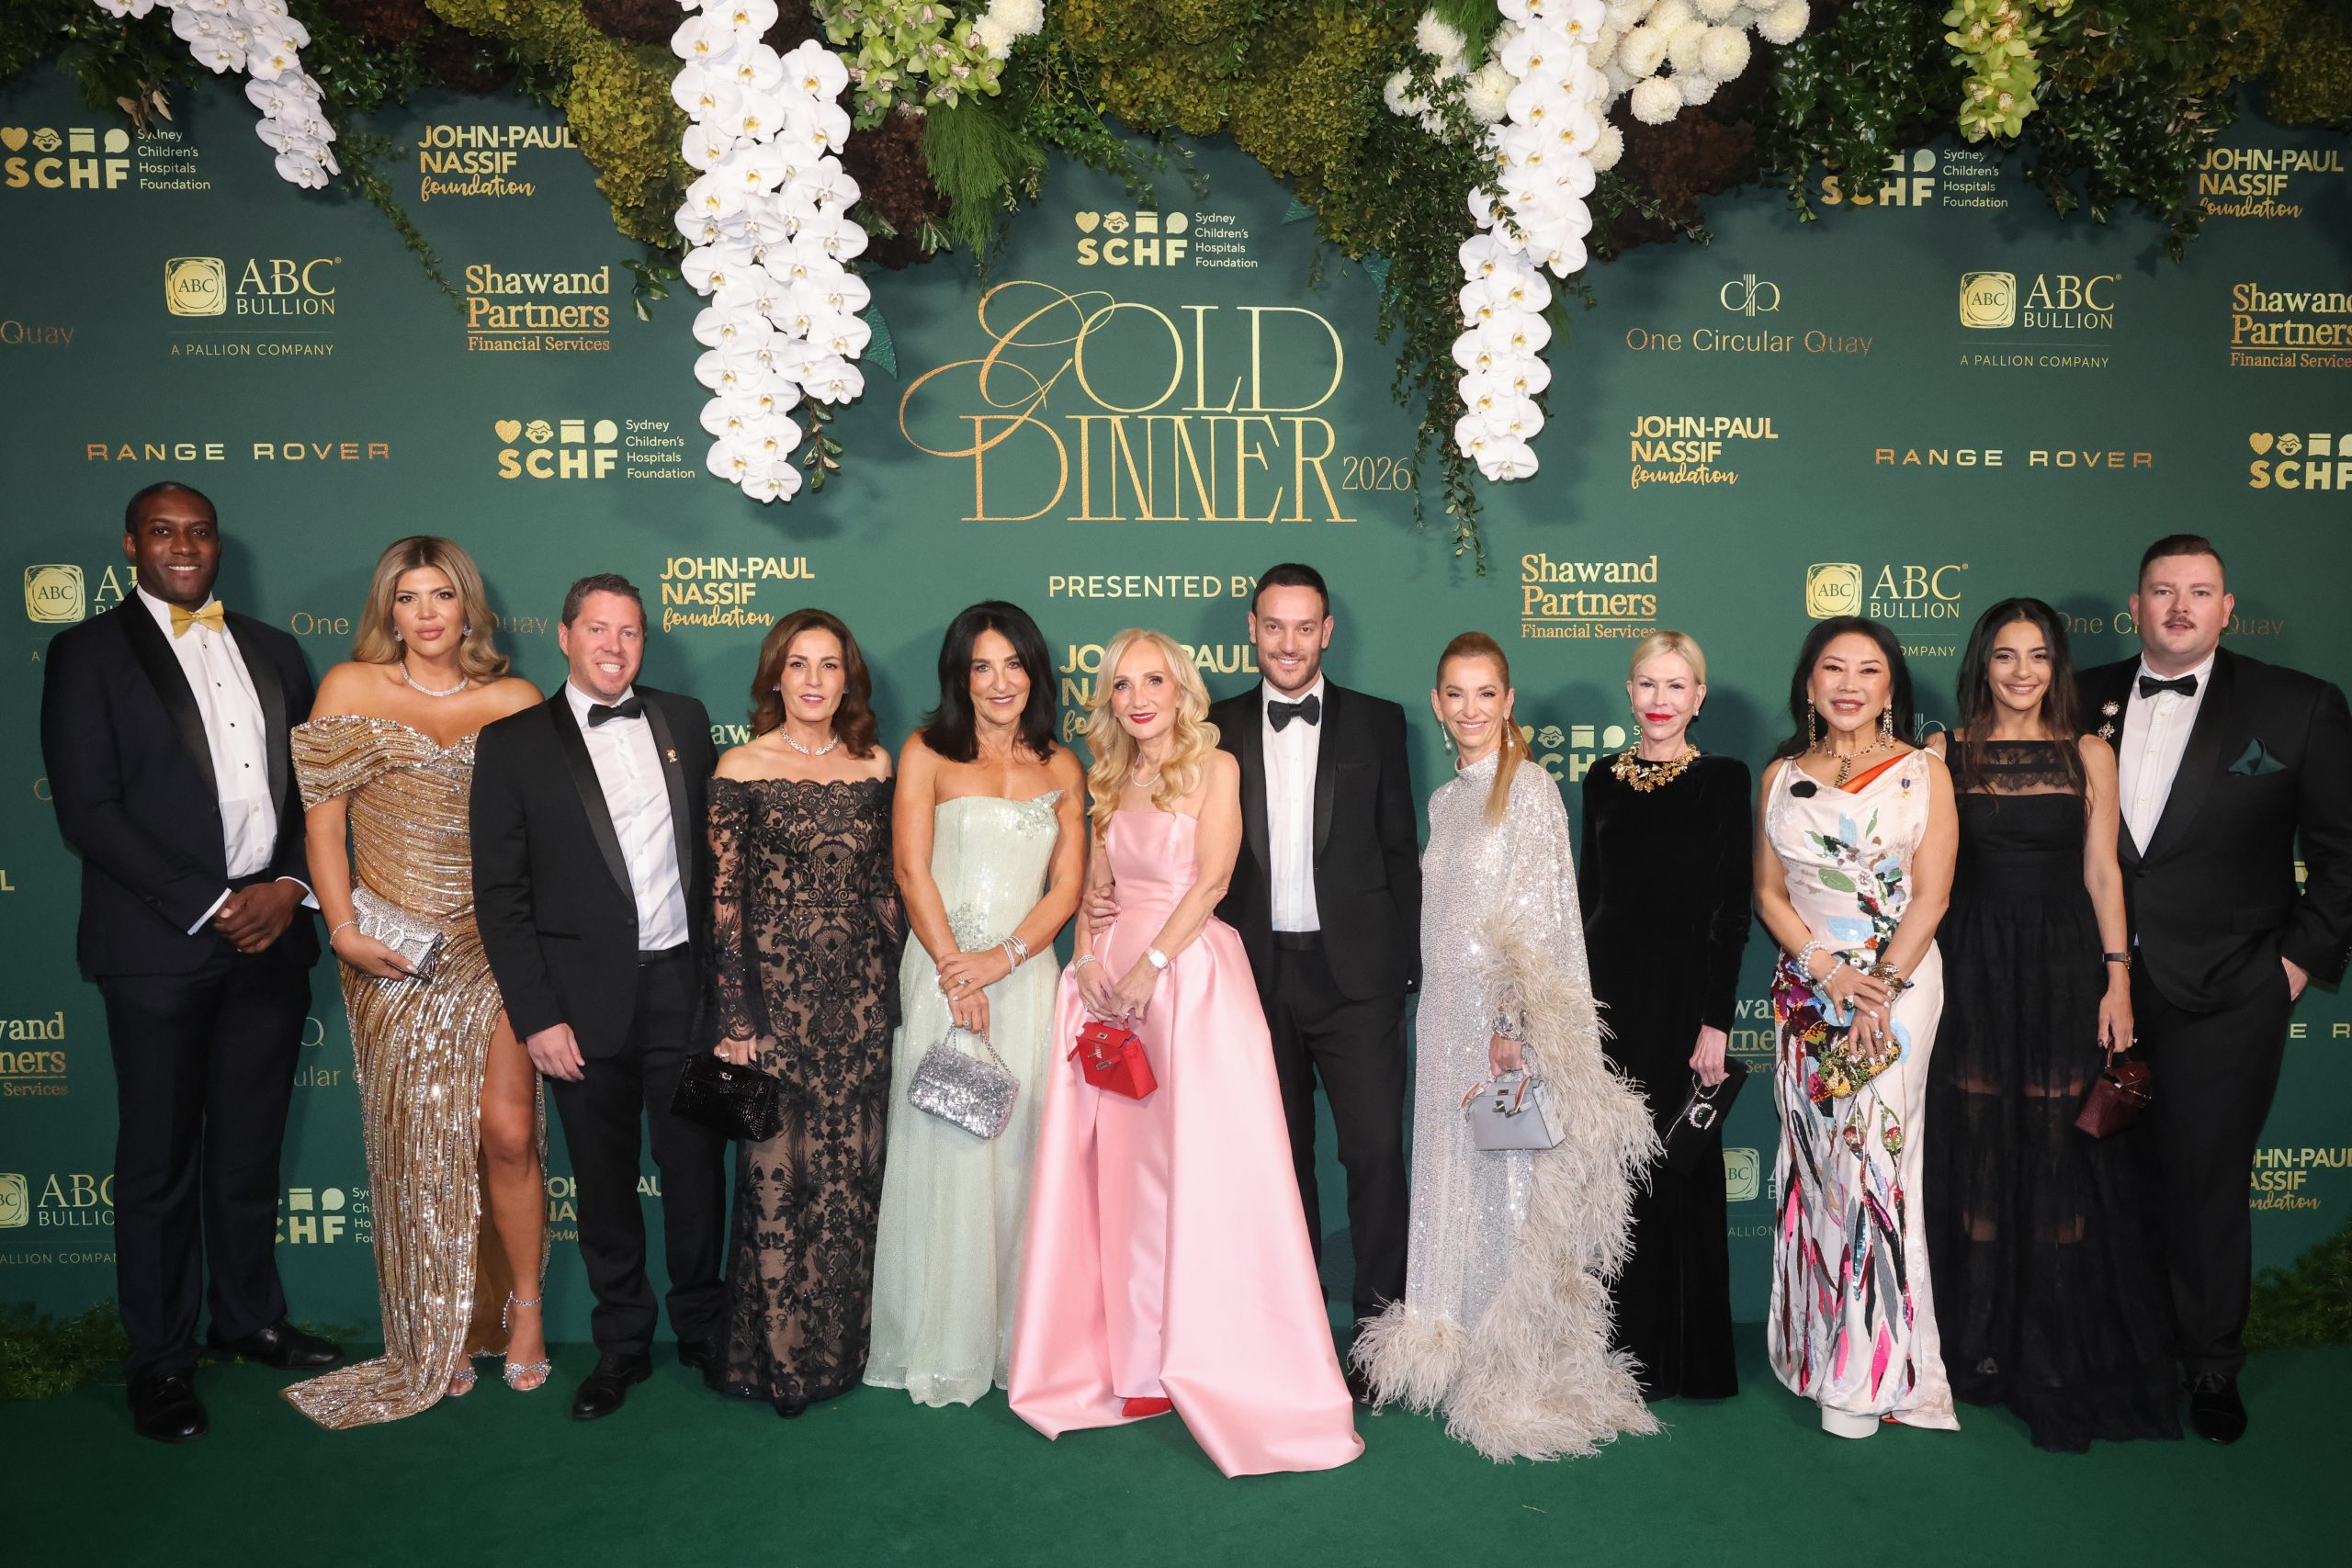
Sydney Children’s Hospitals Foundation CEO Kristina Keneally says Australia’s culture of large-scale philanthropy is becoming more sophisticated as Gold Dinner raises $75.5 million for children’s health, research and innovation.

Paine Schwartz joins BERO as a new investor as the year-old company seeks to triple sales.