Is China’s Economic Predicament as Bad as Japan’s? It Could Be Worse
From demographics to decoupling, China faces challenges Japan didn’t after its 1980s bubble

 4 min
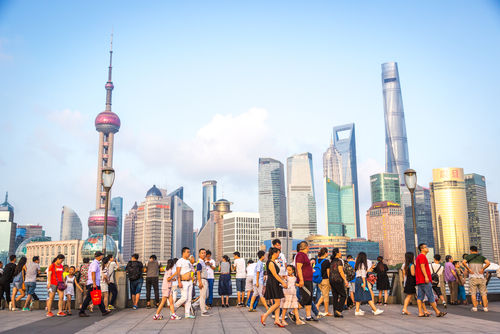
HONG KONG—Starting in the 1990s Japan became synonymous with economic stagnation, as a boom gave way to lethargic growth, declining population and deflation.
Many economists say China today looks similar. The reality: In many ways its problems are more intractable than Japan’s. China’s public debt levels are higher by some measures than Japan’s were and its demographics are worse. The geopolitical tensions that China is dealing with go beyond the trade frictions Japan once faced with the U.S.
Another headwind: China’s government, which has been cracking down on the private sector in recent years, seems ideologically less inclined than Tokyo was then to support growth.
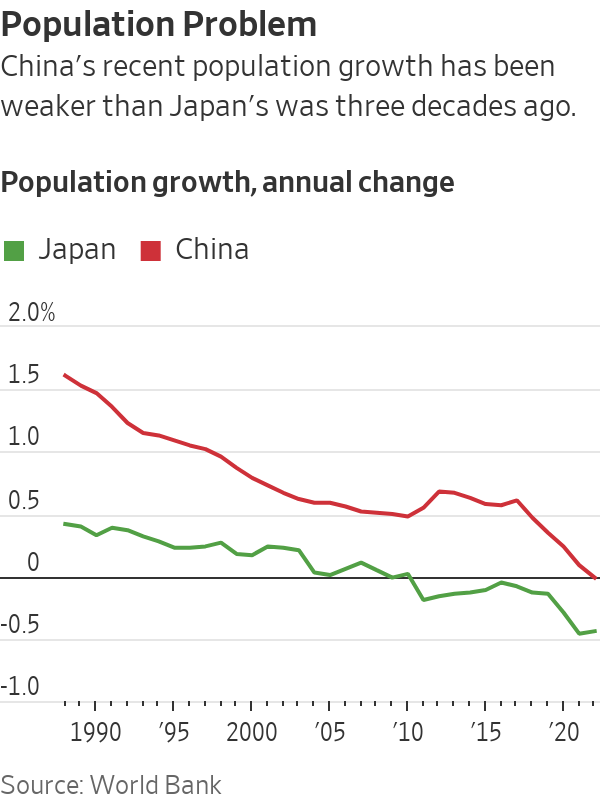
None of this means China is sure to repeat the years of economic stagnation that Japan is only now showing signs of exiting. It has some advantages that Japan didn’t. Its economic growth in coming years is likely to be well above Japan’s in the 1990s.
Even so, economists say the parallels are a warning for Communist Party leaders in Beijing: If they don’t act more forcefully, the country could get stuck in a protracted period of economic sluggishness similar to Japan’s. Despite piecemeal steps in recent weeks, including modest interest-rate cuts, Beijing has held back on major stimulus to revive growth.
“China’s policy responses so far could put it on track for ‘Japanification,’” said Johanna Chua, chief Asia economist at Citigroup. She believes China’s overall growth prospects could be slowing more sharply than Japan’s.
China today and Japan 30 years ago share many similarities, including high debt levels, an aging population and signs of deflation.
During a long postwar economic expansion, Japan became an export powerhouse that American politicians and corporate executives worried would be unstoppable. Then in the early 1990s, real estate and stock market bubbles burst and the economy hit the skids.
Policy makers cut interest rates to virtually zero, but growth failed to rebound as consumers and companies focused on repaying debt to repair their balance sheets instead of borrowing to finance new spending and investment.
Richard Koo, an economist at the research arm of Japanese investment bank Nomura Securities, famously coined the term “balance sheet recession” to describe the phenomenon.
China, too, has seen a property bubble pop after years of extraordinary economic growth. Chinese consumers are now paying off mortgages early, despite government efforts to get them to borrow and spend more.
Private firms are also reluctant to invest despite lower interest rates, stirring anxiety among economists that monetary easing might be losing its potency in China.
By some measures, China’s asset bubbles aren’t as big. Morgan Stanley estimates that China’s ratio of property value to gross domestic product peaked at 260% in 2020, up from 170% of GDP in 2014; home prices have only fallen slightly since the peak, according to official data. China’s equity markets hit a recent peak of 80% of GDP in 2021 and now sit at 67% of GDP.
In Japan, land values as a percentage of GDP reached 560% of GDP in 1990 before falling back to 394% by 1994, Morgan Stanley estimates. The Tokyo Stock Exchange’s market capitalisation rose to 142% of GDP in 1989 from 34% in 1982.
Also in China’s favour, its urbanisation rate is lower, standing at 65% in 2022, versus Japan’s, which was at 77% in 1988. That could give China more potential to raise productivity and growth as people move to cities and take on nonagricultural jobs.
China’s tighter control over its capital markets means the risk of a sharp appreciation of its currency, which would harm exports, is low. Japan had to deal with a sharp increase in its currency several times in recent decades, which at times added to its economic struggles.
“We believe worries on China being trapped in a balance sheet recession are overdone,” economists from Bank of America recently wrote.
Yet in other ways, China’s problems will be harder to tackle than Japan’s.
Its population is ageing faster; it began to decline in 2022. In Japan, that didn’t happen until 2008, nearly two decades after its bubble burst.
Worse, China appears to be entering a period of weaker long-term growth rates before reaching rich-world status, i.e. it is getting old before it gets rich: China’s per capita income was $12,850 in 2022, much lower than Japan in 1991 at $29,080, World Bank data shows.
Then there is the problem of debt. Once off-balance-sheet borrowing by local governments is factored in, total public debt in China reached 95% of GDP in 2022, compared with 62% of GDP in Japan in 1991, according to J.P. Morgan. That limits authorities’ ability to pursue fiscal stimulus.
External pressures also appear to be tougher for China. Japan faced a lot of heat from its trading partners, but as a military ally of the U.S., it never risked a “new Cold War”—as some analysts now describe the U.S.-China relationship. Efforts by the U.S. and its allies to block China’s access to advanced technologies and reduce reliance on Chinese supply chains have sparked a plunge in foreign direct investment into China this year, which could significantly slow growth in the long run.
Many analysts worry Beijing is underestimating the risk of long-term stagnation—and doing too little to avoid it. Moderate cuts to key interest rates, lowering down payment ratios for apartments and recent vocal support for the private sector have done little to revive sentiment so far. Economists including Xiaoqin Pi from Bank of America argue that more coordinated easing in fiscal, monetary and property policies will be needed to put China’s growth back on track.
But President Xi Jinping is ideologically opposed to increasing government support for households and consumers, which he derides as “welfarism.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
AI doesn’t rebel—people design, deploy and profit from it. The real danger lies in allowing tech companies to escape accountability while shaping regulations that protect their dominance.
4 min
A wave of corporate warnings and technical disclosures has flooded the media, with headlines worrying over “swarms” of rogue artificial-intelligence agents launching “unprecedented” cyberattacks, outsmarting their makers, and inching toward a terrifying autonomy. The most revealing part of this narrative isn’t what the software did. It’s who is telling the story—and why. When corporate leaders publicly insist that the systems they financed, engineered and deployed are suddenly beyond their power to contain, skepticism isn’t only healthy; it is essential.
For years, Silicon Valley has drawn scrutiny from civil society and global regulators over tangible harms such as youth mental health deterioration and systematic privacy violations. Today, industry figures seem to be trying to change that public image. Loudly blowing the whistle on their own systems—just as two of the leading companies were preparing for massive initial public offerings—lets AI executives position themselves as a new generation of leaders who have come to terms with their societal responsibilities. They seem to want us to believe that they no longer want to “move fast and break things” but will instead stand as vigilant guardians between humanity and a technological apocalypse.
There is one glaring problem: Software doesn’t rebel. A mathematical model possesses neither intent, malice nor the will to defy its creators, let alone extinguish our species. AI is a human artifact, engineered for profit.
When an agentic model in an evaluation sandbox connects to an unauthorized server or executes an exploit, it hasn’t staged a coup. It has tried to meet the human-defined objectives set out before it through a path its designers failed to constrain. It’s the digital equivalent of the King Midas myth, in which the king’s ill-defined wish turns even his food and drink into gold.
That powerful experimental models were able to discover novel vulnerabilities and breach external systems isn’t a sign of a dangerous superintelligence but of human error or negligence. There is no sentient actor lurking in the weights to be reasoned with, feared or pacified. There are only human software engineers, product managers and corporate boards deciding which guardrails are worth the latency cost and which permissions can be skipped in the race to market.
Policymakers and voters need to resist AI exceptionalism. In any other discipline—from civil engineering to pharmaceuticals—courts and regulators treat a system failure as evidence of bad product design and inadequate safety testing. If an aircraft crashes, we focus on finding the engineering defect, correcting it, and enforcing established liability standards for the damage created.
By leaning on an anthropomorphic narrative, Silicon Valley attempts to repackage its specific human choices that led to experimental, powerful models behaving unexpectedly during tests as an existential peril. Elevating the issue to a cosmic scale leaves the public paralyzed and takes ordinary product accountability off the table.
In the cutthroat race for venture capital and market dominance, building guardrails slows down deployment. Grandstanding about uncontrollable power costs nothing and generates billions of dollars in free publicity, justifying stock prices, all while cultivating an aura of technological capability not only to build the frontier but also ultimately to rein it in.
Governments need to recognize regulatory capture when it stares them in the face. Tech leaders’ strategy looks transparent: Alarm Washington and Brussels into creating a regime in which only trillion-dollar incumbents with fully staffed compliance and safety departments can legally operate. By sitting at the policymakers’ tables before anyone else, these companies can help draft rules digging an impassable moat protecting them from open-source developers and upstart competitors, domestic or international. The real danger is in further concentrating the tech industry into the hands of only a few companies with deep pockets.
Beijing and Washington have brushed off those tech leaders’ calls, albeit for very different reasons. Chinese state media dismissed them as part of the “Cold War playbook” and intended to preserve U.S. dominance. Xi Jinping argued for exactly the opposite at the Brics Summit on Sept. 12, calling on Brics countries to “strengthen cooperation in the field of AI, encourage open source, openness, collaboration and sharing, and break new grounds and scale new heights.” President Trump, steeped in a doctrine of unfettered capitalism and technological supremacy, called fears that AI could destroy humanity a “hoax.” Vice President JD Vance warned that AI companies “begging the government to regulate them” looked like a “Trojan Horse.”
Striving to pursue its “European way” on AI and assert regulatory leadership, Europe, by contrast, welcomed the call. European Union President Ursula von der Leyen made this clear at the State of the EU speech last Wednesday and announced that the EU will invite “the main frontier labs for a discussion on how we can support ongoing industry efforts to pace the frontier.”
Europe has been here before. In an effort to lead global regulation and react to fears borne from ChatGPT, Europe rushed its landmark AI Act into law in 2024. Already the world’s most restrictive rulebook, the framework quickly proved too broad and complex to enforce. Stalled by implementation delays and concerns about European competitiveness, the EU postponed the law’s full rollout, leaving regulations uncertain.
AI should be regulated—risks exist and should be taken seriously. But governments need to act based on available evidence and verified facts, not corporate PR panic, the views of industry insiders, or the desire for quick political wins. The greatest danger facing society isn’t that software will awaken and overthrow its human masters. It is that we will allow the creators of the software to abdicate human responsibility for the systems they choose to build and help them pull up the ladder to market access behind them.

Wealthy Aussies are swapping large family homes for high-end apartments, with sales of prestige units tripling over the past decade.
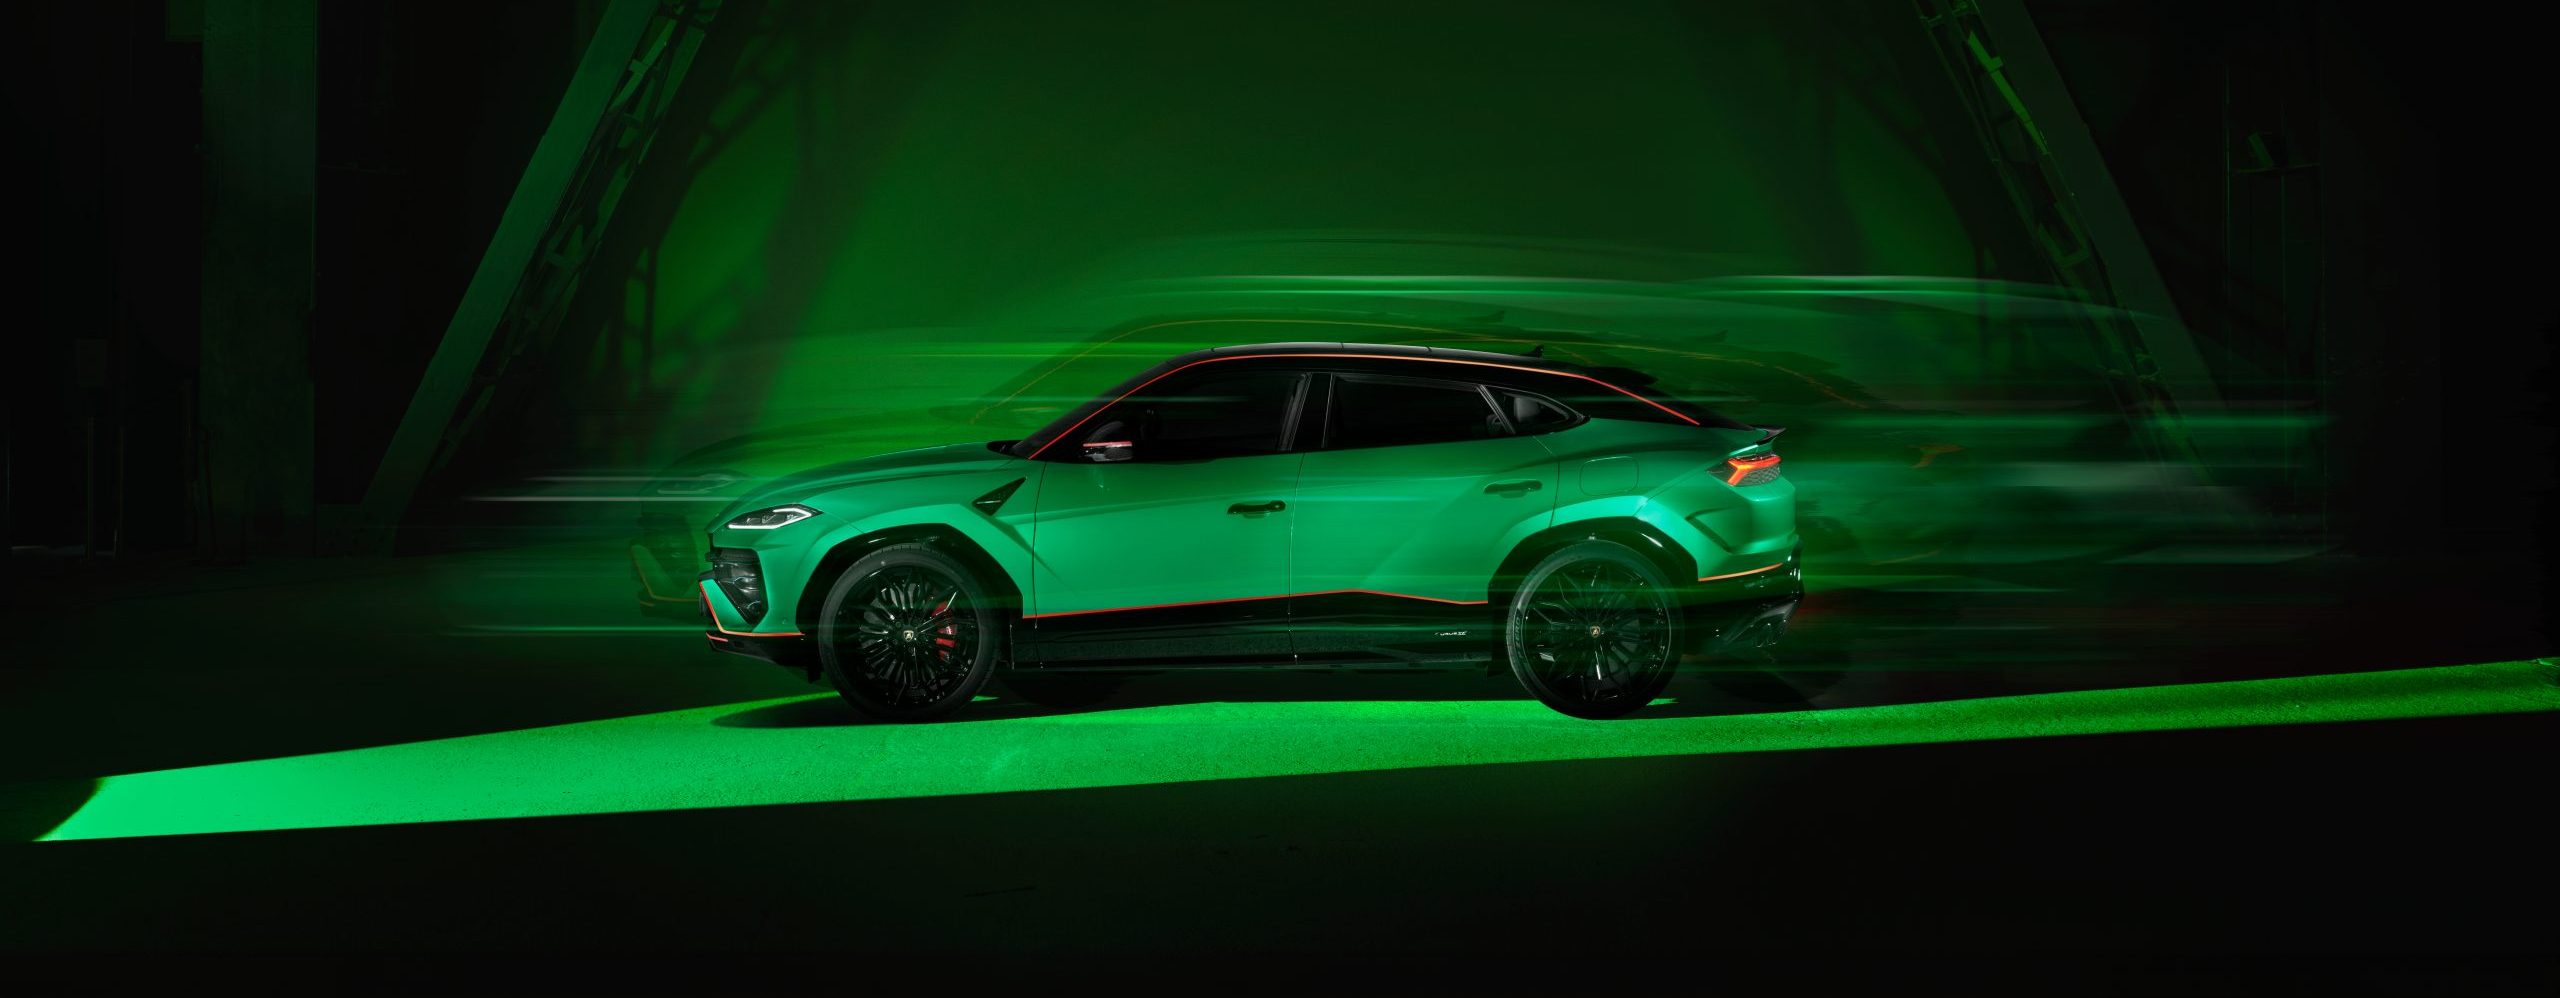
Limited to 630 units, Lamborghini’s latest Urus Capsule pushes personalisation further than ever, blending hybrid performance with over 70 bespoke design combinations.