Dave Ramsey Tells Millions What to Do With Their Money. People Under 40 Say He’s Wrong.
Young adults are rejecting the finance guru’s advice to live frugally while getting out of debt

 4 min
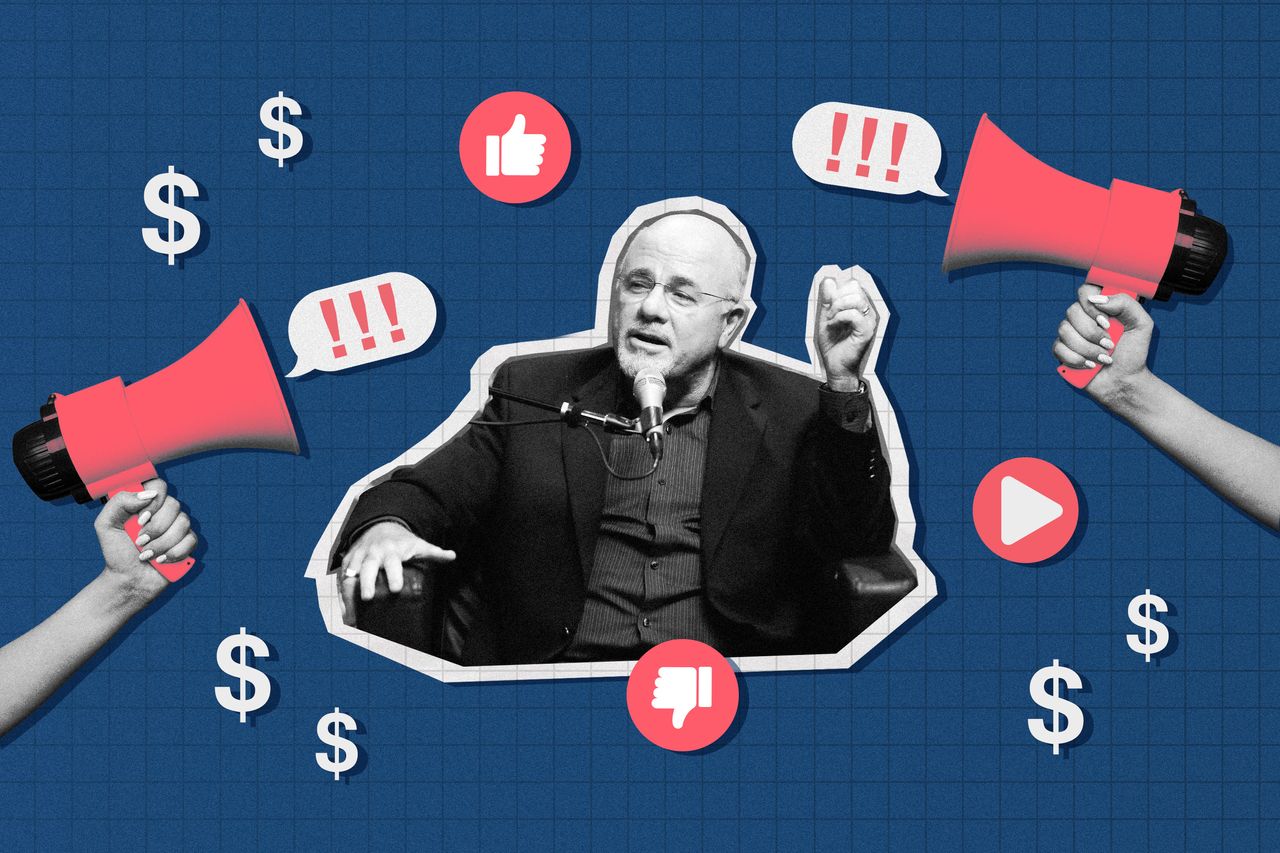
On their own for the first time, young professionals are craving sound financial advice. They just don’t want to hear it from Dave Ramsey.
Ramsey, the well-known and intensely followed 63-year-old conservative Christian radio host, has 4.4 million Instagram followers, 1.9 million TikTok followers and legions more who listen to his radio shows and podcasts. His message is brutal and direct: Avoid debt at all costs. Pay for everything in cash. Embrace frugality.
Plenty of 20- and 30-year-olds are pushing back, largely on TikTok. The hashtag #daveramseywouldntapprove, for instance, has 66.8 million views. Many say they don’t want to eat rice and beans every night—a popular Ramsey trope —or hold down multiple jobs to pay off loans. They also say Ramsey is out of touch with their reality.
Rising inflation has led to surging prices for groceries, cars and many essentials. The cost of a college education has skyrocketed in two decades, with the average student debt for federal loans at $37,000, according to the Education Department. Overall debts for Americans in their 30s jumped 27% from late 2019 to early 2023 —steeper than for any other age group. And home prices have risen considerably, while wages haven’t kept pace.
“What Dave Ramsey really misses is any kind of social context,” says Morgan Sanner, a 26-year-old who runs a résumé-advice company in Columbus, Ohio, and has shared her feelings about Ramsey on TikTok.
She began paying off $48,000 in student loans (a Ramsey do ) and also took out a loan to buy a 2016 Honda (a Ramsey don’t ). Her rationale was that it was safer to pay extra for a more reliable car than a junker she could buy with cash. She feels these sorts of real-life decisions don’t factor into his advice. Her video about this has 875,000 views.
Through a spokeswoman, Ramsey declined an interview request. Direct messages to Ramsey went unanswered.
For Ramsey—whose TikTok posts often contain incendiary tidbits from his radio show—the pushback might be part of the plan. After all, uncomfortable advice is a key component of his success.
‘Pretty much screwed already’
Naiomi Israel began watching Dave Ramsey’s videos on YouTube when she was in college at New York University, before TikTok became the go-to platform. (He has more than 500,000 subscribers on YouTube.)
“Not knowing about money feels scary, especially when you’re a young adult and have to pay your bills,” she says. “You wonder, ‘Should I go on a trip or invest in the S&P 500?’ I’m just looking for the right answers.”
Israel, who now at age 23 works for a company that develops finance curricula for schools, says she was initially drawn in by Ramsey’s no-nonsense advice. He recommends setting aside some money for emergencies. She did.
But eventually, some of his messages triggered a different response from her: “Wait, what?”
When she saw a comment from Ramsey online about how people receiving pandemic stimulus payments were “ pretty much screwed already ,” Israel felt it came across as shaming people. The pandemic shutdowns ended a decade-long economic expansion for Black Americans , a disproportionate number of whom lost their jobs and relied on those checks.
“Moralising financial decisions is very damaging to marginalised groups,” says Israel, who is Black.
From bankruptcy to broadcasting
Ramsey’s anti-debt evangelism arose from personal circumstances. He says on his website that he took on too much debt while accumulating real estate as a young man. He also bought a Jaguar, jewellery for his wife and a trip to Hawaii. In 1988, he filed for bankruptcy.
How did rich people stay rich? By not paying interest to banks, he concluded.
He started a radio show in 1992 to answer callers’ money questions. It became the top-rated show in Nashville, Tenn., and eventually became a nationally syndicated call-in program with about 20 million weekly listeners.
The radio program begot Ramsey Solutions, a 1,000-person company that encompasses a podcast, 23 money-management books, a budgeting app and personal-financial coaching. Dozens of Facebook groups are devoted to following his methods. Ramsey’s net worth is estimated at more than $200 million.
No credit scores?
Many young adults scratch their heads over his advice that people should let their credit scores dwindle and die .
People need a good credit score, says Mandy Phillips, a 39-year-old residential mortgage loan originator in Redding, Calif. She uses TikTok and other social media to educate millennials and Gen Z about home buying. Scores are vital when applying for mortgages and rentals.
She also takes issue with Ramsey’s advice to only obtain a home loan if you can take out a 15-year fixed-rate mortgage with a down payment of at least 10%. Few younger buyers can pay the large monthly bills of shorter-term mortgages.
“That may have worked years ago in the ’80s and ’90s, but that’s not something that is achievable for the average American,” Phillips says.
Ramsey acknowledges on his website that his views aren’t always in step with conventional economic thinking. “I have an unusual way of looking at the world,” he notes, nodding to his past debt troubles.
Housing is a particularly hot-button topic. He advises people to only buy a house with their lawfully wedded spouse. Yet many young adults are pooling their finances with partners, friends or roommates to buy their first homes.
The debt snowball
Ramsey is perhaps best known for advocating a “ debt snowball method ”: People with multiple loans pay off the smallest balances first, regardless of interest rate. As you knock out each loan, he says, the money you have to put toward larger debt snowballs. Seeing small wins motivates people to keep going, he says.
Conventional economic theory would be to pay off the highest-interest loans first, says James Choi, a finance professor at the Yale School of Management, who has studied the advice of popular finance gurus.
“What Dave Ramsey would say is, ‘I don’t care if paying down the highest-interest debt first is cheapest, because if you give up midway through, that’s more expensive.’ I think the jury is out on that,” Choi says.
Ramsey’s advice has helped a lot of people reduce their spending.
A University of Copenhagen researcher conducted a study that found that when Ramsey’s radio show entered new markets between 2004 and 2019, households in those cities decreased their monthly expenditures by at least 5.4%.
Embracing debt
Ramsey’s save-not-spend message sounds logical, young adults say. It’s his all-or-nothing approach that doesn’t work for them.
Kate Hindman, a 31-year-old administrative assistant in Pasadena, Calif., who has taken an anti-Ramsey stance on TikTok, ended up with $30,000 in credit-card debt after she and her husband faced income-reducing job changes. They’ve since turned it into a consolidation loan with an 8% interest rate and pay about $1,200 a month.
She wonders if the debt aversion is generational. Perhaps younger people are less willing to make huge sacrifices to be debt-free. Maybe carrying some amount of debt forever is a new normal. Hindman’s video about her credit-card debt journey—and how it doesn’t align with Ramsey’s perspective—has more than 745,000 views.
Hindman said in the TikTok video: “I’m sorry, I’m not willing to do anything to get out of debt. I’m not willing to eat rice and beans every day.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
AI doesn’t rebel—people design, deploy and profit from it. The real danger lies in allowing tech companies to escape accountability while shaping regulations that protect their dominance.
4 min
A wave of corporate warnings and technical disclosures has flooded the media, with headlines worrying over “swarms” of rogue artificial-intelligence agents launching “unprecedented” cyberattacks, outsmarting their makers, and inching toward a terrifying autonomy. The most revealing part of this narrative isn’t what the software did. It’s who is telling the story—and why. When corporate leaders publicly insist that the systems they financed, engineered and deployed are suddenly beyond their power to contain, skepticism isn’t only healthy; it is essential.
For years, Silicon Valley has drawn scrutiny from civil society and global regulators over tangible harms such as youth mental health deterioration and systematic privacy violations. Today, industry figures seem to be trying to change that public image. Loudly blowing the whistle on their own systems—just as two of the leading companies were preparing for massive initial public offerings—lets AI executives position themselves as a new generation of leaders who have come to terms with their societal responsibilities. They seem to want us to believe that they no longer want to “move fast and break things” but will instead stand as vigilant guardians between humanity and a technological apocalypse.
There is one glaring problem: Software doesn’t rebel. A mathematical model possesses neither intent, malice nor the will to defy its creators, let alone extinguish our species. AI is a human artifact, engineered for profit.
When an agentic model in an evaluation sandbox connects to an unauthorized server or executes an exploit, it hasn’t staged a coup. It has tried to meet the human-defined objectives set out before it through a path its designers failed to constrain. It’s the digital equivalent of the King Midas myth, in which the king’s ill-defined wish turns even his food and drink into gold.
That powerful experimental models were able to discover novel vulnerabilities and breach external systems isn’t a sign of a dangerous superintelligence but of human error or negligence. There is no sentient actor lurking in the weights to be reasoned with, feared or pacified. There are only human software engineers, product managers and corporate boards deciding which guardrails are worth the latency cost and which permissions can be skipped in the race to market.
Policymakers and voters need to resist AI exceptionalism. In any other discipline—from civil engineering to pharmaceuticals—courts and regulators treat a system failure as evidence of bad product design and inadequate safety testing. If an aircraft crashes, we focus on finding the engineering defect, correcting it, and enforcing established liability standards for the damage created.
By leaning on an anthropomorphic narrative, Silicon Valley attempts to repackage its specific human choices that led to experimental, powerful models behaving unexpectedly during tests as an existential peril. Elevating the issue to a cosmic scale leaves the public paralyzed and takes ordinary product accountability off the table.
In the cutthroat race for venture capital and market dominance, building guardrails slows down deployment. Grandstanding about uncontrollable power costs nothing and generates billions of dollars in free publicity, justifying stock prices, all while cultivating an aura of technological capability not only to build the frontier but also ultimately to rein it in.
Governments need to recognize regulatory capture when it stares them in the face. Tech leaders’ strategy looks transparent: Alarm Washington and Brussels into creating a regime in which only trillion-dollar incumbents with fully staffed compliance and safety departments can legally operate. By sitting at the policymakers’ tables before anyone else, these companies can help draft rules digging an impassable moat protecting them from open-source developers and upstart competitors, domestic or international. The real danger is in further concentrating the tech industry into the hands of only a few companies with deep pockets.
Beijing and Washington have brushed off those tech leaders’ calls, albeit for very different reasons. Chinese state media dismissed them as part of the “Cold War playbook” and intended to preserve U.S. dominance. Xi Jinping argued for exactly the opposite at the Brics Summit on Sept. 12, calling on Brics countries to “strengthen cooperation in the field of AI, encourage open source, openness, collaboration and sharing, and break new grounds and scale new heights.” President Trump, steeped in a doctrine of unfettered capitalism and technological supremacy, called fears that AI could destroy humanity a “hoax.” Vice President JD Vance warned that AI companies “begging the government to regulate them” looked like a “Trojan Horse.”
Striving to pursue its “European way” on AI and assert regulatory leadership, Europe, by contrast, welcomed the call. European Union President Ursula von der Leyen made this clear at the State of the EU speech last Wednesday and announced that the EU will invite “the main frontier labs for a discussion on how we can support ongoing industry efforts to pace the frontier.”
Europe has been here before. In an effort to lead global regulation and react to fears borne from ChatGPT, Europe rushed its landmark AI Act into law in 2024. Already the world’s most restrictive rulebook, the framework quickly proved too broad and complex to enforce. Stalled by implementation delays and concerns about European competitiveness, the EU postponed the law’s full rollout, leaving regulations uncertain.
AI should be regulated—risks exist and should be taken seriously. But governments need to act based on available evidence and verified facts, not corporate PR panic, the views of industry insiders, or the desire for quick political wins. The greatest danger facing society isn’t that software will awaken and overthrow its human masters. It is that we will allow the creators of the software to abdicate human responsibility for the systems they choose to build and help them pull up the ladder to market access behind them.
From the shacks of yesterday to the sculptural sanctuaries of today, Australia’s coastal architecture has matured into a global benchmark for design.

Warmer minimalism, tactile materials and wellness focused layouts are redefining luxury interiors as homeowners design for comfort, connection and lasting appeal.