DOUBLE-DIGIT HOUSE PRICE GROWTH ARRIVES AHEAD OF EXPECTATIONS
Australia’s housing market defies forecasts as prices surge past pandemic-era benchmarks.
 2 min
Australian house prices are surging again, delivering double-digit annual growth months ahead of schedule.
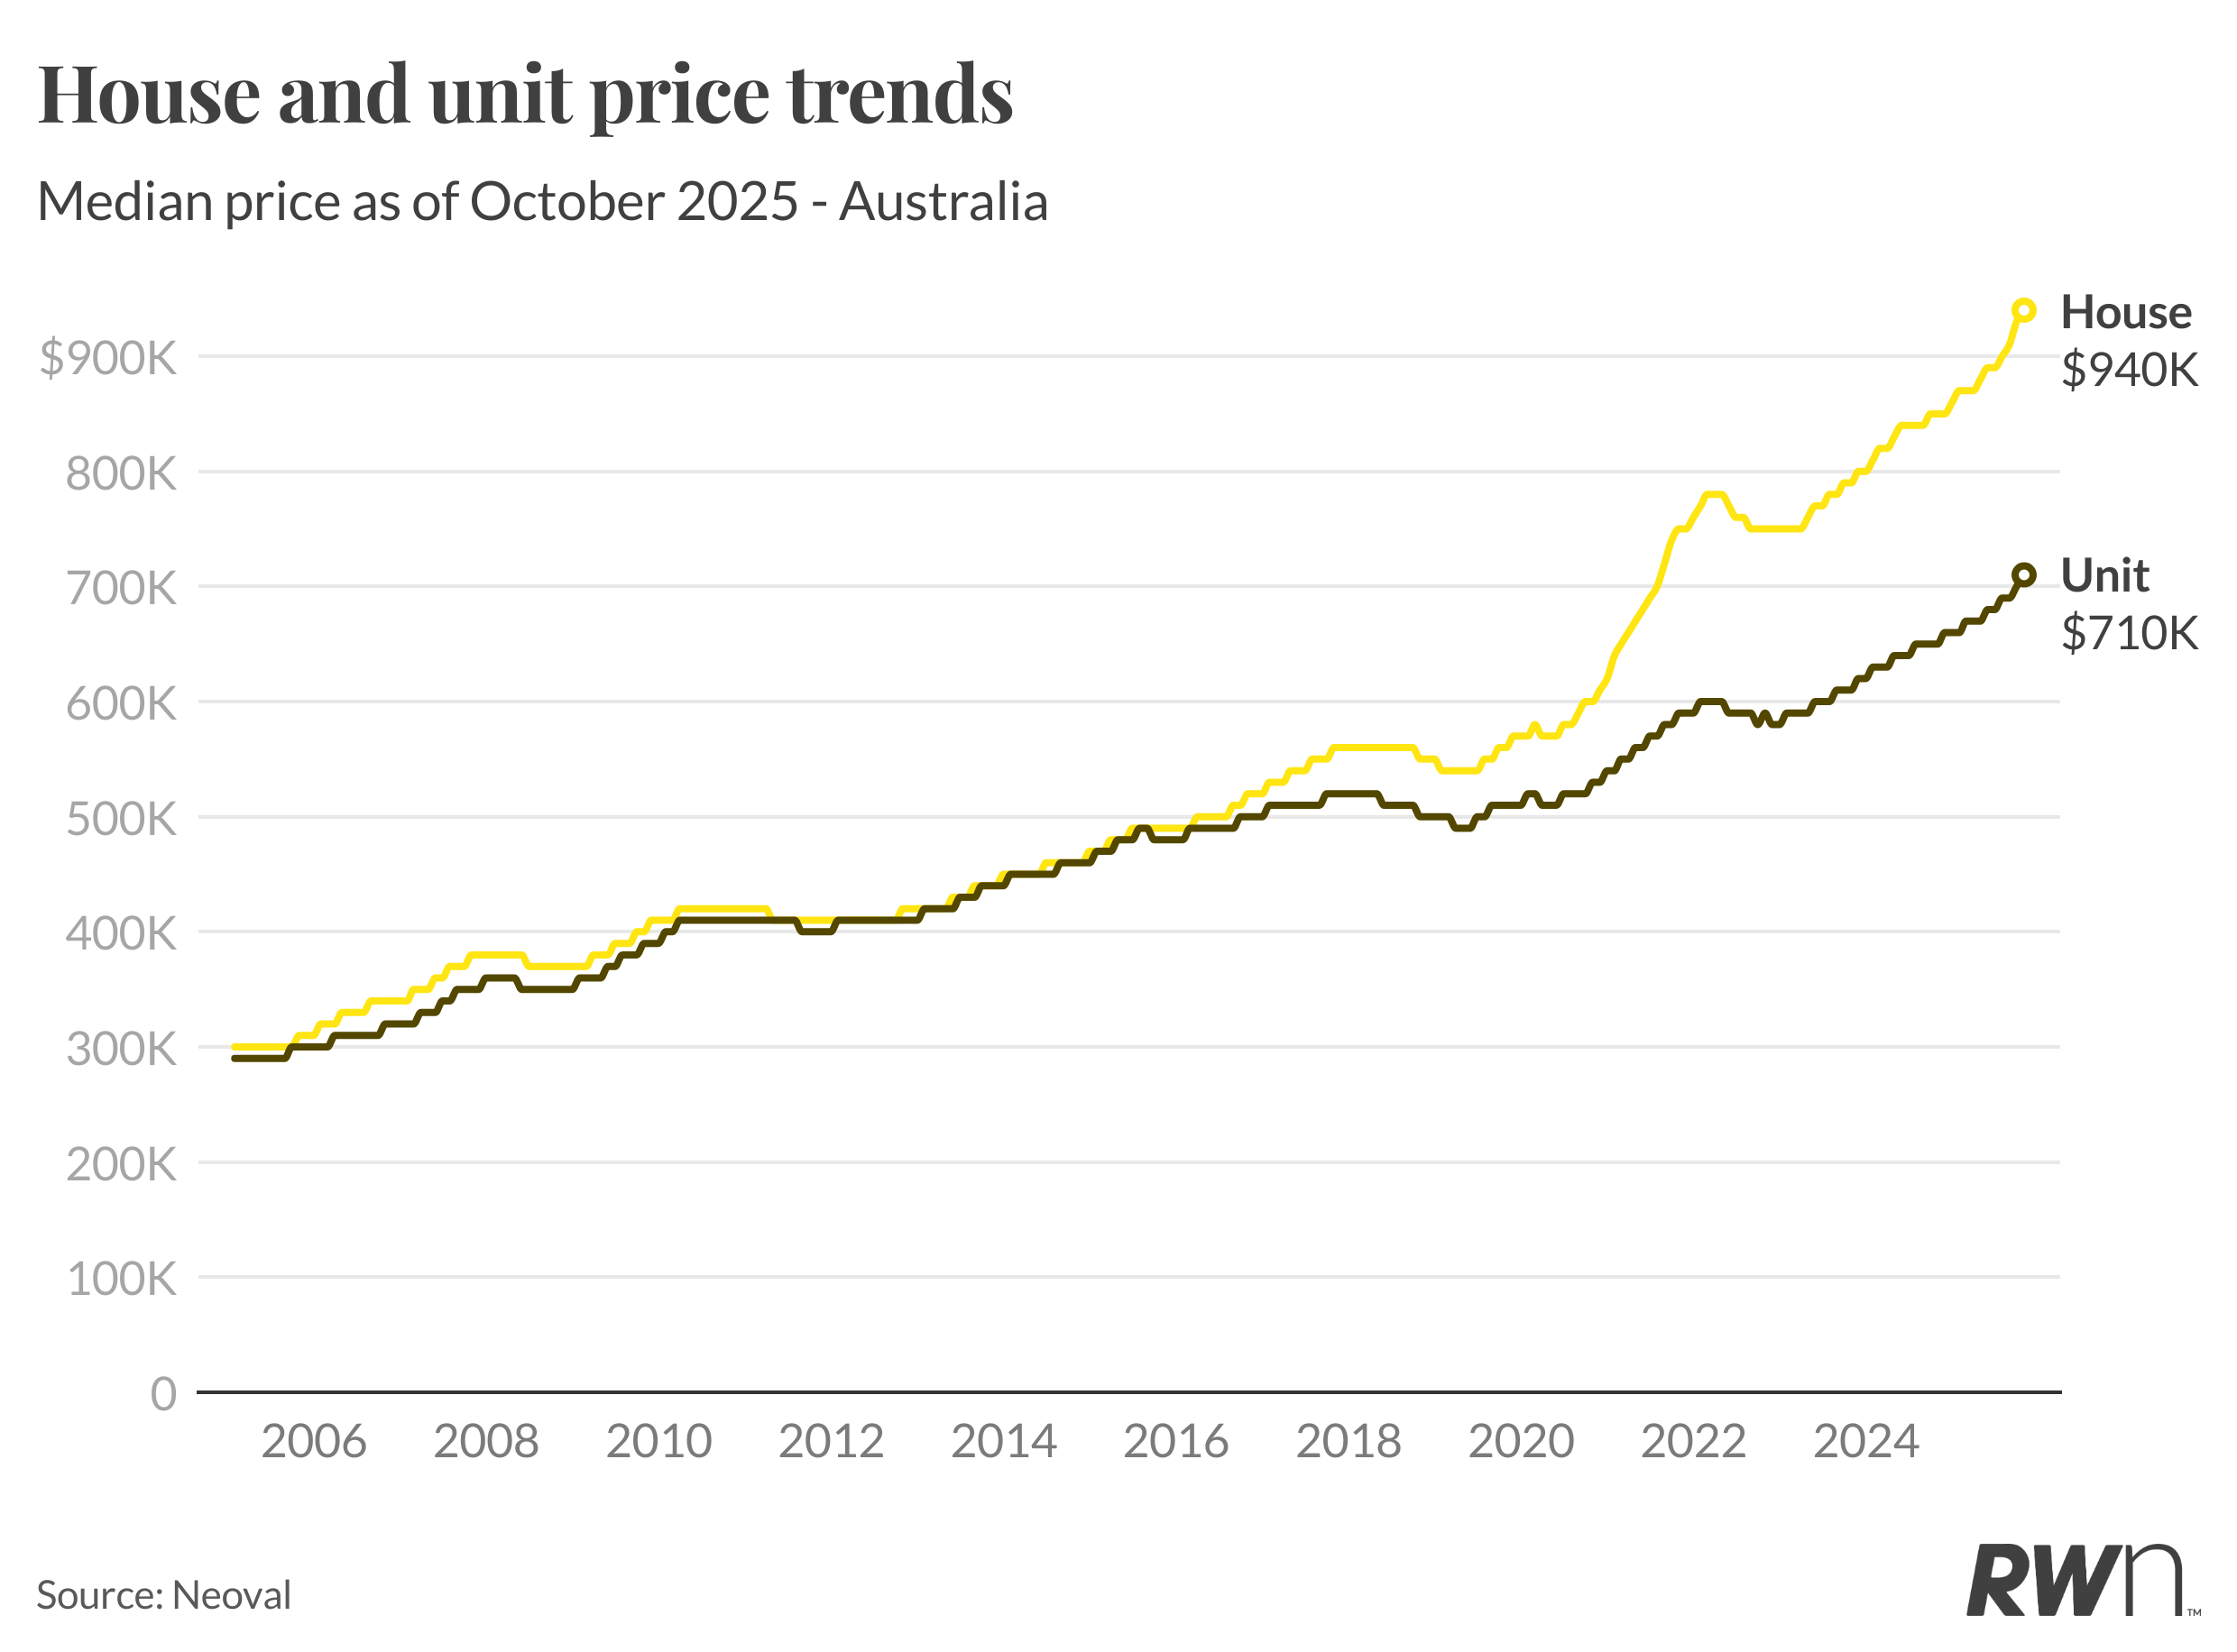
Nationally, the median house price climbed 1.1 per cent in October to $940,000, lifting annual growth to 10.6 per cent, the first double-digit increase since the 2021–22 property boom.
Market Resilience Surprises Analysts
The acceleration comes earlier than expected, according to Ray White Group Chief Economist Nerida Conisbee, who says the milestone was originally forecast for the end of the year.
“Stronger-than-expected October gains and continued tight supply across most markets have pushed growth ahead of schedule,” Conisbee said. “This shows how resilient demand has remained through spring.”
Perth (+14.8 per cent), Brisbane (+12.5 per cent) and Adelaide (+10.8 per cent) continue to lead the charge among capital cities, while Sydney (+8.6 per cent) and Melbourne (+6.5 per cent) show steady, consistent increases.
Regional Markets Extend Their Lead
Beyond the capitals, regional Australia is powering ahead, particularly in the resource states.
Regional Western Australia jumped 16.4 per cent year-on-year, and regional Queensland followed close behind at 14.5 per cent, as population growth and affordability continue to drive demand.
Units Outperform Houses
Unit prices rose even more sharply in October, up 1.4 per cent to $710,000, marking 9.2 per cent annual growth. Conisbee said affordability pressures, new first home buyer incentives, and a lack of available stock are pushing more buyers into the apartment market.
“Units are now seeing stronger monthly gains than houses, reflecting both affordability constraints and renewed first-home-buyer activity,” she said.
The biggest monthly jumps were in Perth (+1.6 per cent), Adelaide (+1.5 per cent), and Brisbane (+1.4 per cent). Melbourne’s unit market also firmed, up 1.6 per cent, as buyers returned to lower price brackets.
Spring Demand Defies Higher Listings
Despite an influx of spring listings, new stock has failed to match the intensity of buyer demand. Nationally, house prices have now risen every month since February, and unit prices every month since March.
“The pace of growth shows demand hasn’t been dampened by higher supply,” Conisbee said.
Outlook: Steady Growth Into 2026
The data comes as the Reserve Bank prepares for its Melbourne Cup Day meeting, where rates are expected to remain on hold at 3.6 per cent.
With inflation easing only gradually and unemployment sitting around 4.5 per cent, analysts expect monetary policy to stay steady for now.
Ray White’s forecast suggests 2025 will close with high single- to low double-digit annual growth nationally, with smaller capitals and regional areas tipped to outperform well into 2026.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
Inflation risks are materialising, prompting the RBA’s fourth rate increase of 2026. Here’s what changed and what Michele Bullock said
5 min
The Reserve Bank of Australia has delivered its fourth interest-rate increase of 2026, lifting the cash-rate target by 25 basis points to 4.60 per cent and warning that further tightening remains possible.
The unanimous decision on 29 September takes the cash rate to its highest level in almost 15 years. More importantly, it confirms that the RBA’s concern has shifted from inflation risks that might materialise to price pressures that are already spreading through the economy.
The increase was widely expected after a series of hawkish comments from senior RBA officials. Financial-market sentiment now remains tilted towards rates staying higher for longer, with some analysts expecting at least one further increase. Yet the decision is not straightforwardly hawkish: the economy is slowing, house prices are falling and household budgets are under mounting pressure. The RBA is tightening because inflation has proved stronger than anticipated, not because the economy is booming.
A significant change in the statement
The clearest change from the RBA’s August statement is the transition from warning about upside risks to declaring that those risks are “materialising”.
In August, the Board left the cash rate at 4.35 per cent to assess the effects of three earlier increases. It said inflation remained too high and acknowledged that the Middle East conflict, elevated energy costs, weak productivity and strong investment related to artificial intelligence could create further price pressure. However, those concerns were still framed principally as risks to the forecast.
The September statement is more definitive. Recent Australian inflation was stronger than the RBA expected, while output growth in the June quarter was also marginally stronger. Businesses consulted through the Bank’s liaison program reported that they were either raising prices or considering doing so. Short-term inflation expectations remained elevated.
The international picture has also deteriorated. The conflict in the Middle East has broadened, oil supplies have suffered further disruption and global energy prices are materially higher than the assumptions used in the RBA’s August forecasts. Higher fuel costs are now being passed through, at least partially, to the prices of other goods and services.
This distinction matters. Central banks generally try to look through a temporary increase in petrol prices because higher interest rates cannot produce more oil or end an overseas conflict. The RBA becomes more likely to act when the original price shock spreads into transport, manufacturing, retail prices, wages and inflation expectations. Its statement suggests that this second-round process has begun.
The RBA also introduced AI-related inflation more prominently into its reasoning. Rapid investment in artificial intelligence is supporting growth among Australia’s major trading partners but is also pushing up demand and prices for technology-related goods. The AI investment boom is therefore playing a double role: cushioning global growth from the Middle East shock while intensifying pressure on prices and scarce resources.
Domestic capacity remains the other half of the inflation story. Australia’s weak productivity growth continues to restrict how quickly the economy can expand without creating price pressure. Business investment and borrowing remain strong, while output has been slightly more resilient than expected. The RBA’s argument is that imported inflation has arrived while the domestic economy still has insufficient spare capacity to absorb it.
Nevertheless, the statement acknowledged considerably more weakness than was evident earlier in the year. Consumer spending is easing, labour-market conditions have softened, house prices have fallen in most capital cities and new housing lending has declined noticeably. The previous three increases appear to be slowing the economy.
That balance makes the decision unusually uncomfortable. The RBA is raising rates into a slowdown because it believes allowing inflation to persist would ultimately demand an even more severe response.
The statement’s final paragraphs also carry a stronger tightening bias than in August. Rather than merely saying rates could rise if required, the Board explicitly committed to doing what was necessary, “including increasing the cash rate target further if needed”. The fact that all nine members supported the increase reinforces the message that the Board saw a clear need to act. RBA monetary policy statement, 29 September 2026
What Bullock said after the decision
At her press conference, Governor Michele Bullock presented the increase as an insurance policy against inflation becoming entrenched rather than the beginning of a predetermined series of rises.
Bullock said the Board considered leaving the cash rate unchanged but ultimately concluded that inflation developments justified another increase. She stopped short of offering forward guidance about the next meeting, saying the RBA would need to observe how all four of this year’s rate increases flowed through the economy.
That caution is important. Monetary policy operates with a lag, so households and businesses have not yet felt the full effect of the earlier increases. Bullock pointed to mortgage payments consuming a growing share of disposable income and the housing downturn as evidence that policy was already restrictive. Whether it is restrictive enough, however, will be determined by subsequent inflation data.
Her core message was that the RBA cannot afford to let Australians become accustomed to inflation of 3 or 4 per cent. If businesses, workers and consumers begin treating that rate as normal, inflation expectations could become embedded in pricing and wage decisions. Reversing that psychology would require a much sharper economic contraction.
Bullock said a recession was not the RBA’s central forecast, but she conceded there were scenarios in which a dramatic slowdown could become necessary if inflation expectations escaped the Bank’s control. “I hope it’s not needed,” she said when asked whether the economy might have to enter recession. ABC News coverage of Bullock’s press conference
She also rejected the idea that the Middle East conflict was solely responsible for the rate increase. The energy shock has intensified the problem, but Australia already faced domestic capacity constraints and inflationary pressure. Interest rates cannot lower global oil prices, but they can weaken demand and make it harder for businesses to pass every cost increase through to customers.
Bullock acknowledged that this mechanism places a disproportionate burden on mortgage holders. She noted that some Australians were taking second jobs to manage higher living costs and debt repayments. Her defence of the decision was that failing to act would eventually produce higher inflation, higher rates and a worse economic outcome.
The mood is now “higher for longer”
Current sentiment is therefore distinctly cautious and hawkish. The September increase was expected, but the unanimous vote and explicit reference to further rises reduce the likelihood of near-term relief for borrowers. Bond-market pricing and some private-sector forecasts point to additional tightening, although the RBA itself has not committed to another move.
The central question is whether four increases—totalling one percentage point this year—will slow domestic demand quickly enough to offset persistent energy, technology and capacity pressures. Falling house prices, weaker lending and softer consumption suggest the policy is working. Stronger inflation and continuing price pass-through suggest it has not yet done enough.
For borrowers, the immediate conclusion is bleak: rate cuts are no longer part of the near-term conversation. The debate is now between holding at 4.60 per cent and raising the cash rate again.
The RBA hopes it can contain inflation without causing a recession. Its latest statement and Bullock’s comments show that it sees a greater danger in doing too little now—and being forced to inflict substantially more damage later.
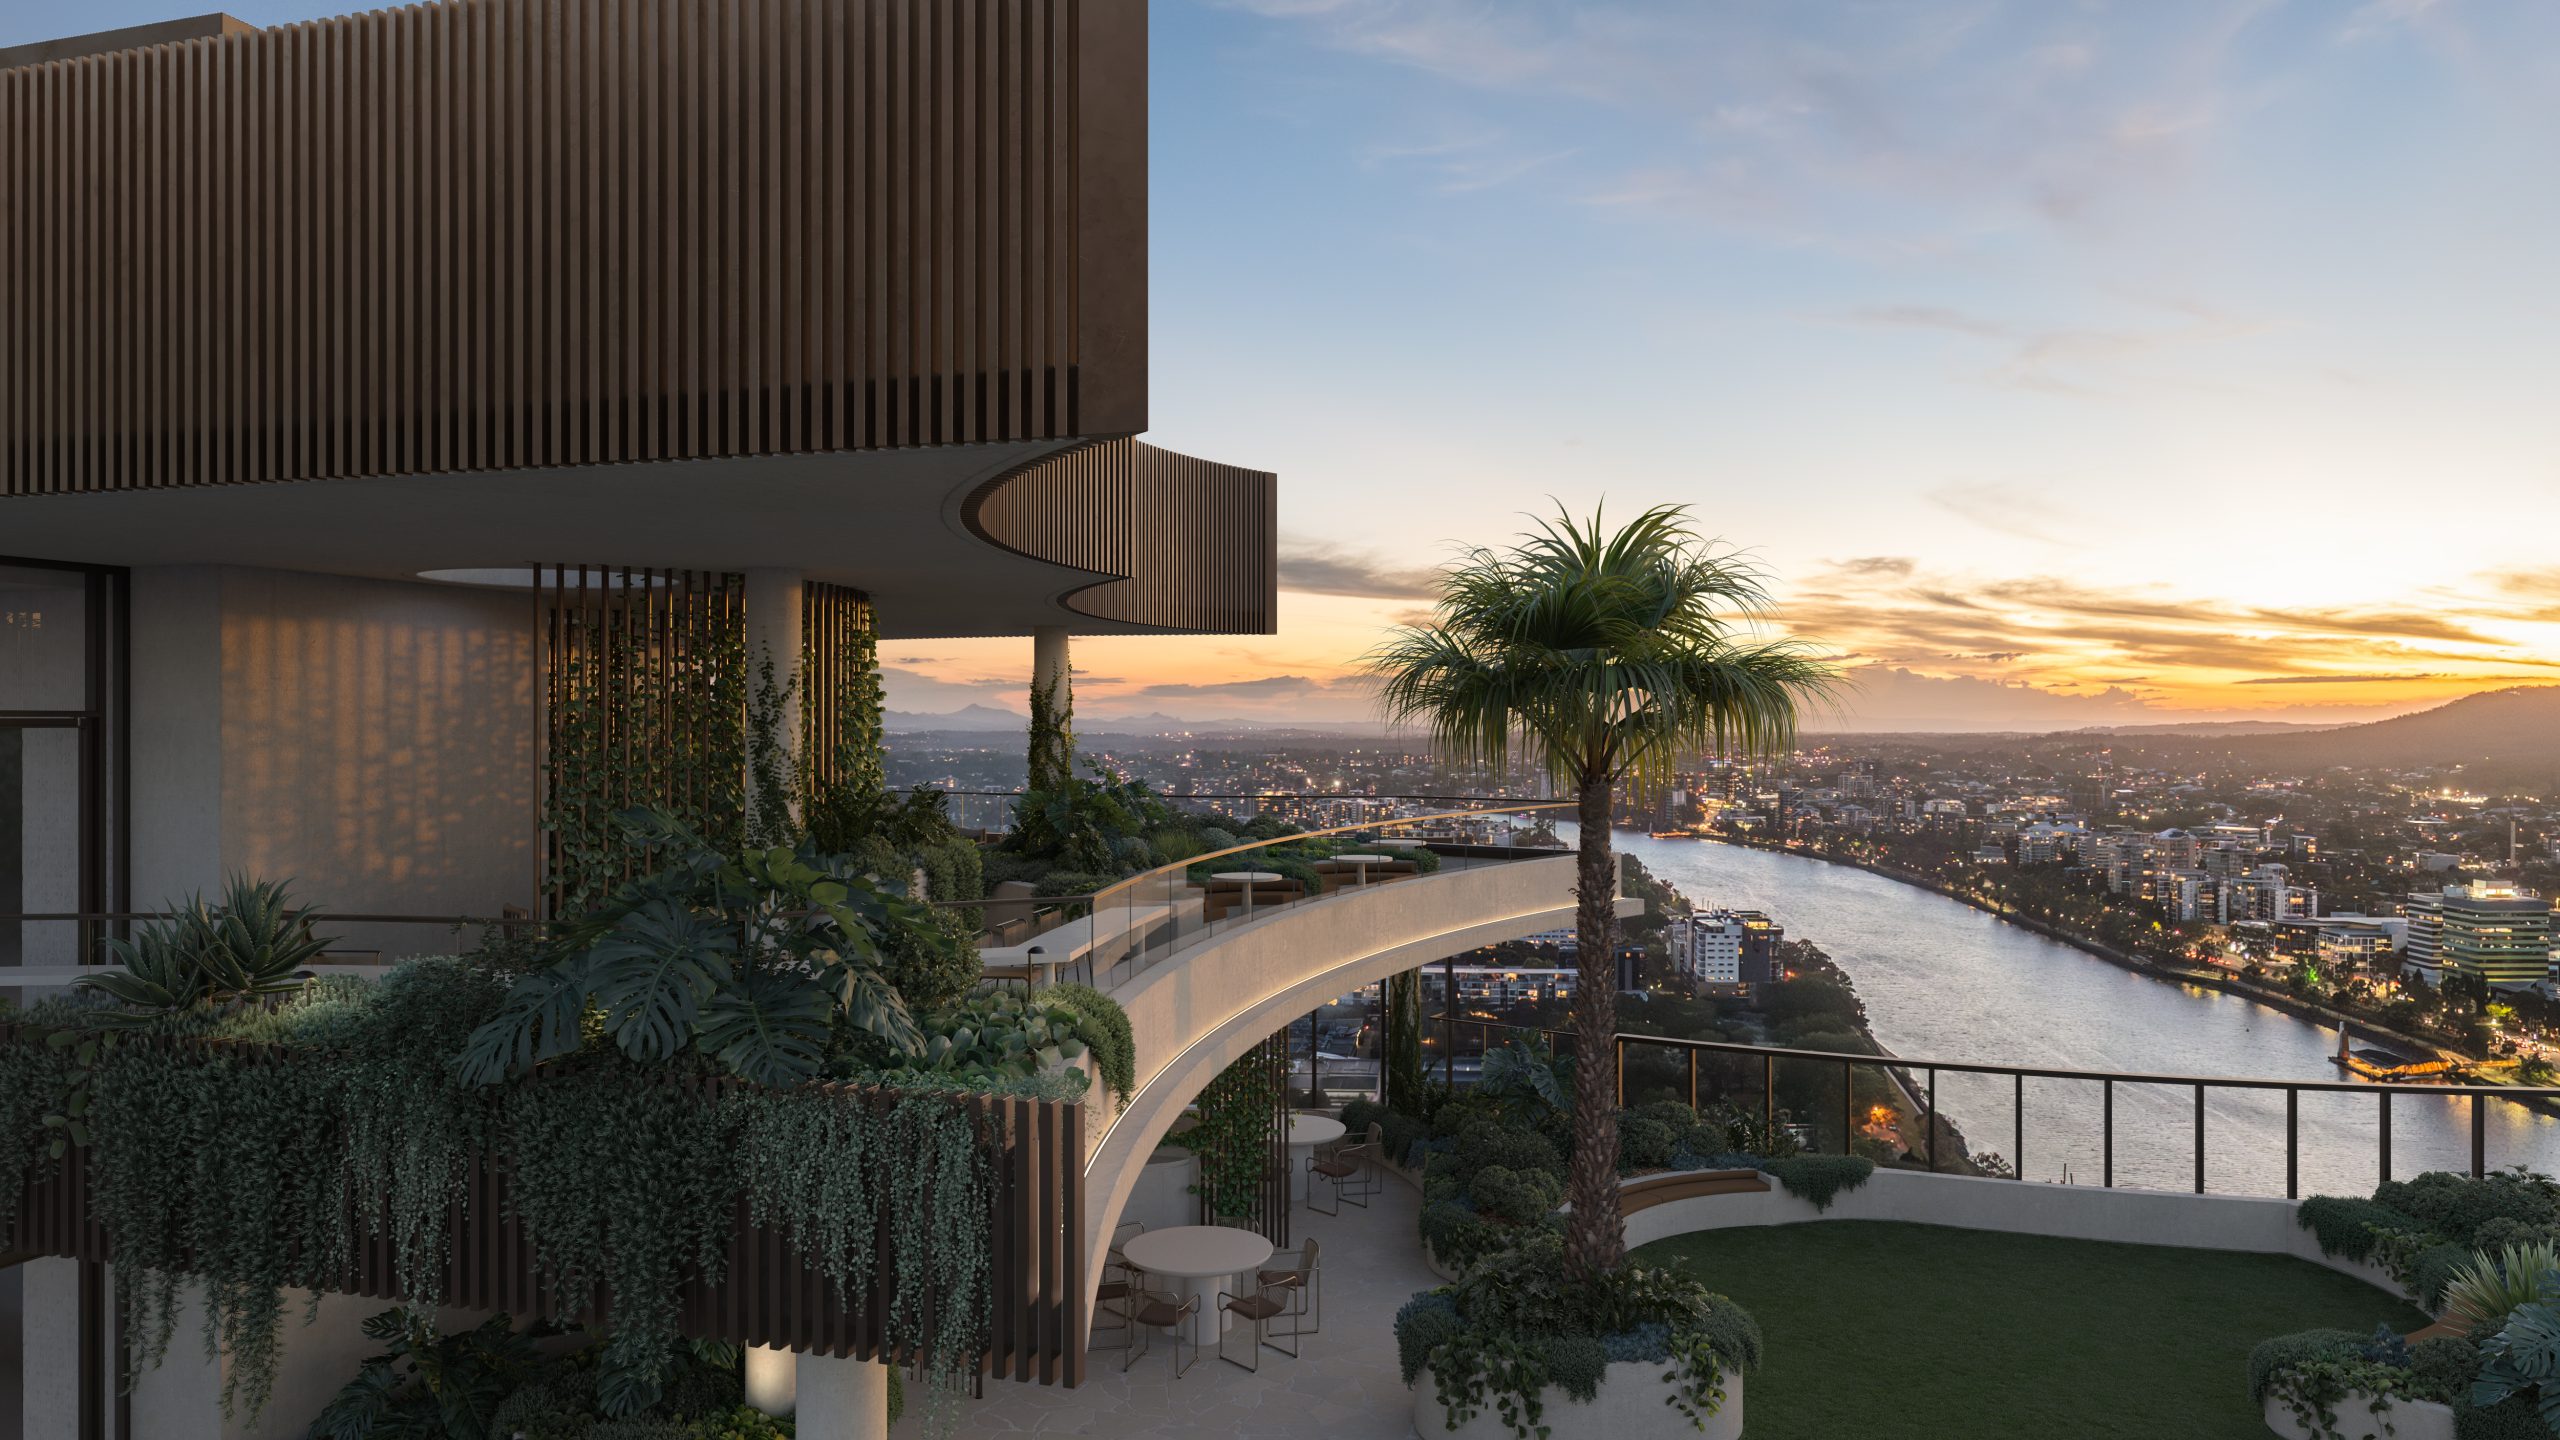
Set on one of the city’s last absolute riverfront sites, The Riversdale by Mosaic combines irreplaceable waterfront ownership with one of Brisbane’s most significant residential opportunities.

A cluster of century-old warehouses beneath the Harbour Bridge has been transformed into a modern workplace hub, now home to more than 100 businesses.