How to be a stylish off-duty gentleman
Some carefully chosen accessories can speak volumes in a gentleman’s casual attire.
 < 1 min

A gentleman’s wardrobe should be held up by certain pillars: perfectly cut—preferably bespoke—suiting in classic shades, pinstripes and checks; fine cotton shirting; silk ties and polished shoes; a wool coat for inclement days.
But increasingly, as casual attire creeps in even to work days, how does he showcase his sartorial status without appearing like an albacore out of water?
WATCH THIS SPACE
A classic timepiece is the ultimate investment piece for any gentleman. Whether you prefer the feel of a leather strap or the weight of articulated steel around your wrist, choose a design that speaks to timeless elegance and masculinity.
Houses such as Longines, Rolex, Jaeger-LeCoultre, Cartier and more will keep you on time and always in style. For a piece that is James Bond-approved—may we suggest an Omega Seamaster to add some depth to your style?
A SHADED VIEW
Take the edge off the day’s glare with some chic sunglasses. Look for styles that hark back to the gentlemen of the Golden Age of Hollywood, such as classic aviators, Wayfarers or those with a keyhole bridge/ Keep the frames in neutral hues such as tortoiseshell, black, tan or metal finishes. The future’s bright—and you’ll be cool.
POCKET THIS
The simplest way to add a fanciful flourish to any look is with a pocket square tucked into your blazer pocket. There are many ways to style them, from a peeking line of fabric to an origami-folded extravaganza.
But should you find yourself in need of a quick fix, even a small puff of silk or a wildly stuffed kerchief will offer a dash of flair.
This is an edited version of the story which appears in the Autumn issue of Kanebridge Quarterly which you can purchase at a newsagent or here.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.
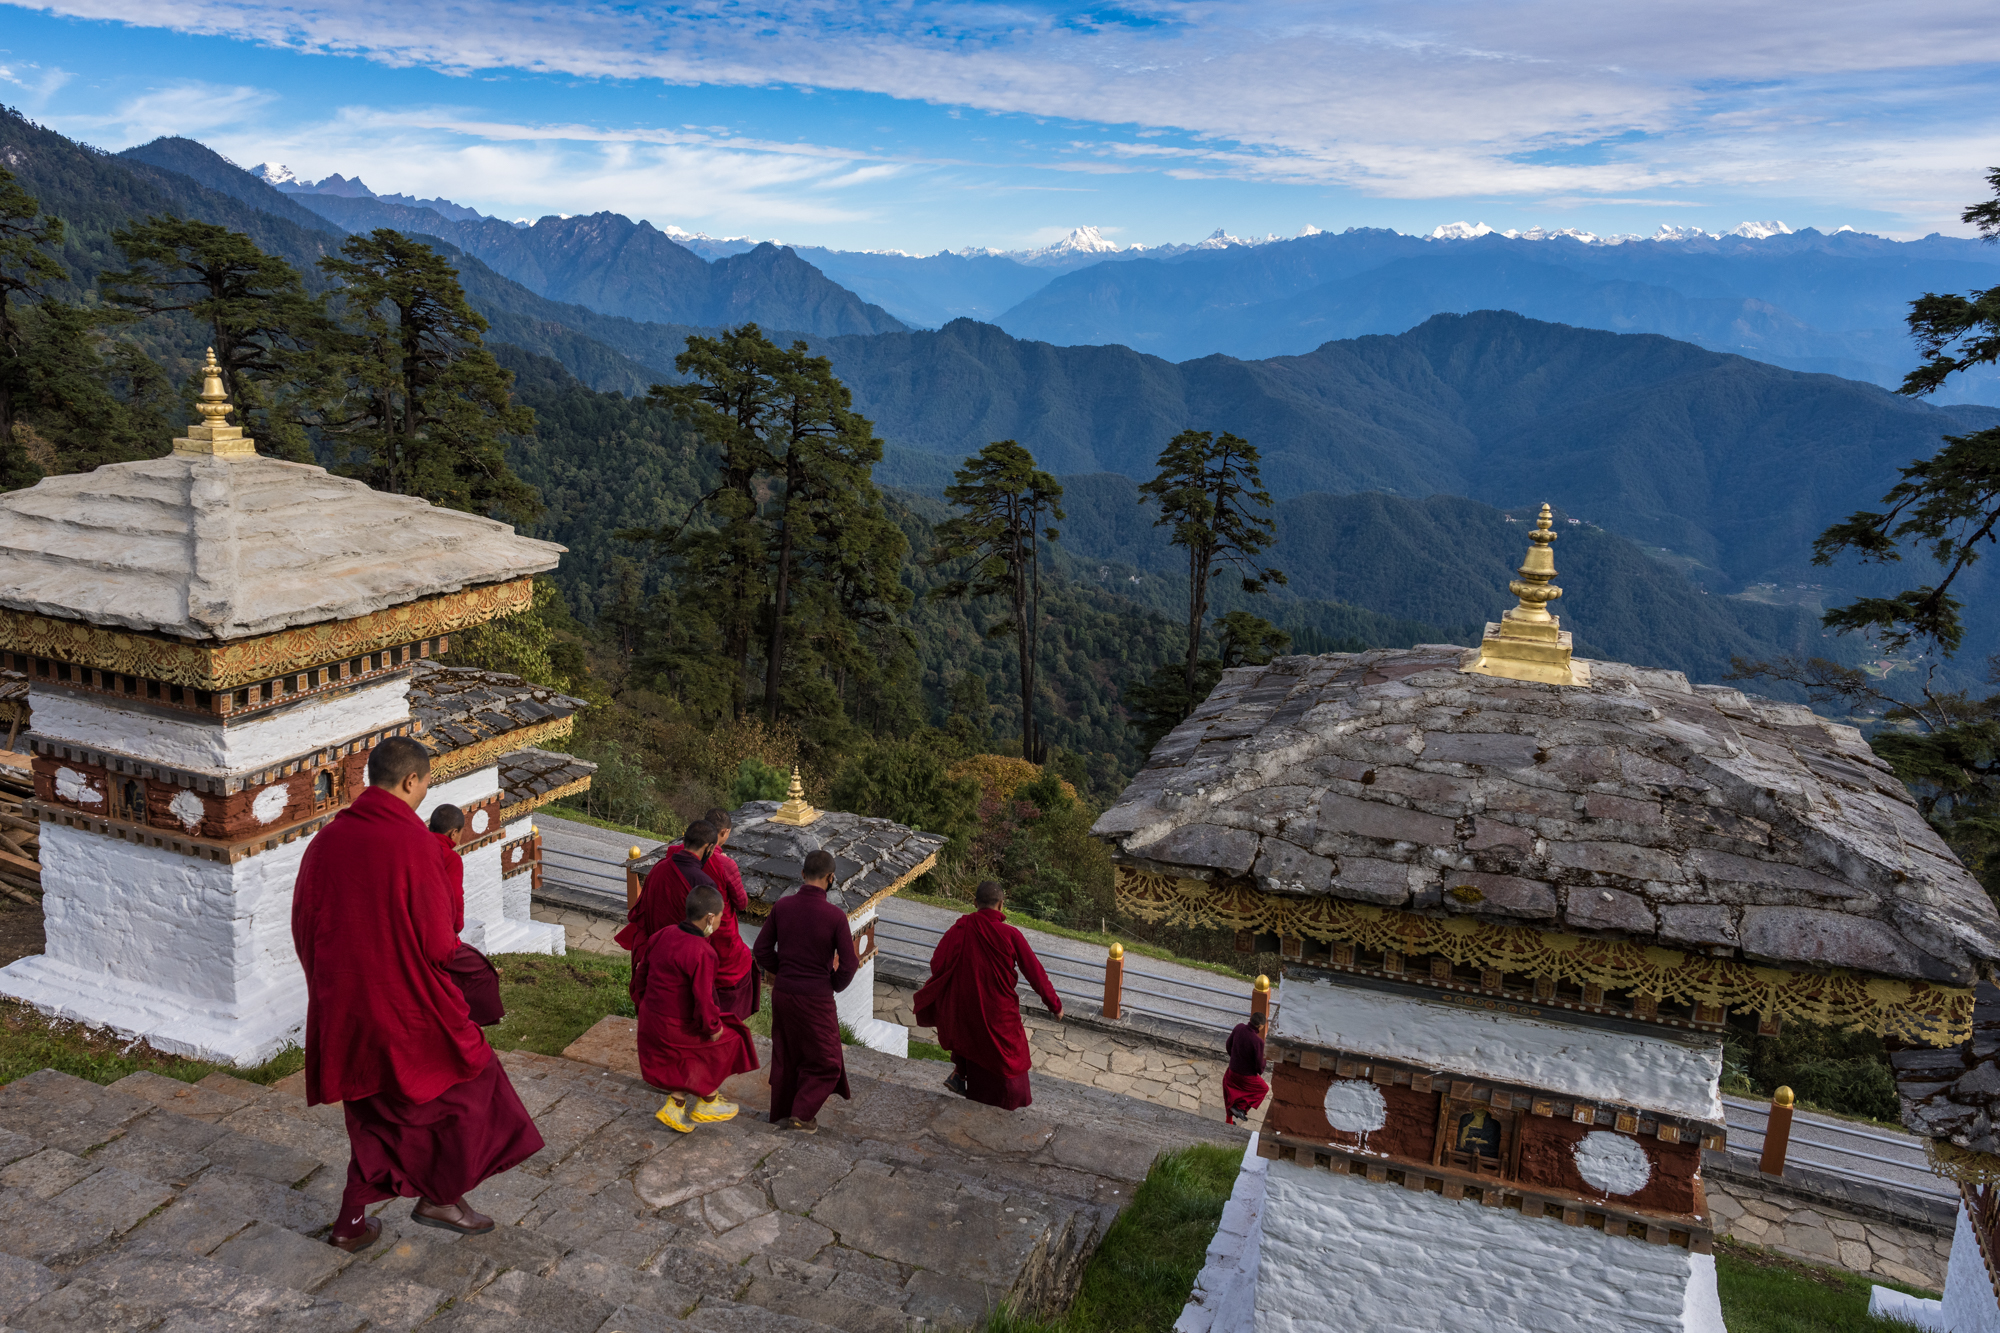
From snow-dusted valleys to festival-filled autumns, Bhutan reveals itself as a rare destination where culture, nature and spirituality unfold year-round.