Hunters Hill Heritage Transformed for Modern Day Living
A heritage-listed Federation estate with tennis court, pool and studio, Marika offers timeless elegance and modern family living in the heart of Hunters Hill.
 2 min


A grand old dame who has stood the test of time, Marika is a slice of Hunters Hill heritage transformed for modern-day living.
Meticulously renovated between 1981 and 1983, with several updates since, Marika made it onto the heritage register in 1999 just in time to signal a new millennium. Today, the modernised mansion is on the market with an auction price guide of $7.5 million, marketed through BresicWhitney’s Nicholas McEvoy.
“The home is a fantastic opportunity for a discerning buyer to get a grand family estate-style property, with a pool, tennis court and grounds, for a price that’s much more affordable than expected,” McEvoy says.
Sitting pretty on the corner of Augustine St and Ryde Rd, the stately Federation residence occupies a sprawling 2472sq m block, which was once part of a 30-acre land grant handed to Frederick Augustus Hayne in 1835. In 1902, he sold it to Dr Leopold Augustus Carter, a local dentist. Two years later, Marika, then known as “Ryde”, appeared in the famed Sands Directory – the social media of its era – a symbol of its architectural significance.
Surrounded by manicured gardens with sculpted hedges, a pool and full tennis court, Marika is a prime example of Federation style with contemporary elements.
Inside, the single-level five-bedroom home showcases intricate craftsmanship, from its decorative gables, period archways and bay windows to the coloured glass panels on multiple doors and windows. Elegant formal rooms have high ornate ceilings that are a preserved nod to Marika’s past, while the more modern spaces are relaxed family-friendly zones.
Thanks to a pavilion-style addition, the L-shaped layout measures 450sq m internally and wraps around a central courtyard that plays host to the alfresco dining terrace and pool, while a wide veranda frames the original front rooms of the house.
Primary living spaces, including the dining area with integrated bar, open to the great outdoors via stacker doors and the 21st century kitchen has a large island bench and a butler’s pantry with hidden access to the triple lock up garage. There is also a dedicated media room, a library or home office, plus a separate family room with a beautiful bay window.
All bedrooms feature built-ins while the main retreat, and a second bedroom, have shower ensuites. The shared bathroom houses convenient twin vanities and a freestanding bathtub.
Beyond the interiors, Marika delivers resort amenities with a full-sized, floodlit tennis court, the pool, barbecue terrace and a self-contained studio apartment with the added bonus of Harbour Bridge glimpses.
Added extras include a converted loft storage space, a large laundry with side yard access, ducted air conditioning, multiple fireplaces, solar panels with a battery backup and modern insulation.
Accessed via Augustine St, Marika is close to St Joseph’s College, Boronia Park shops, local ovals and city transport.
Marika at 59 Augustine St, Hunters Hill is set to go under the hammer on April 26, on site at 9am with a price guide of $7.5 million. The listing is with Nicholas McEvoy and Narelle Scott of BresicWhitney Hunters Hill.

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
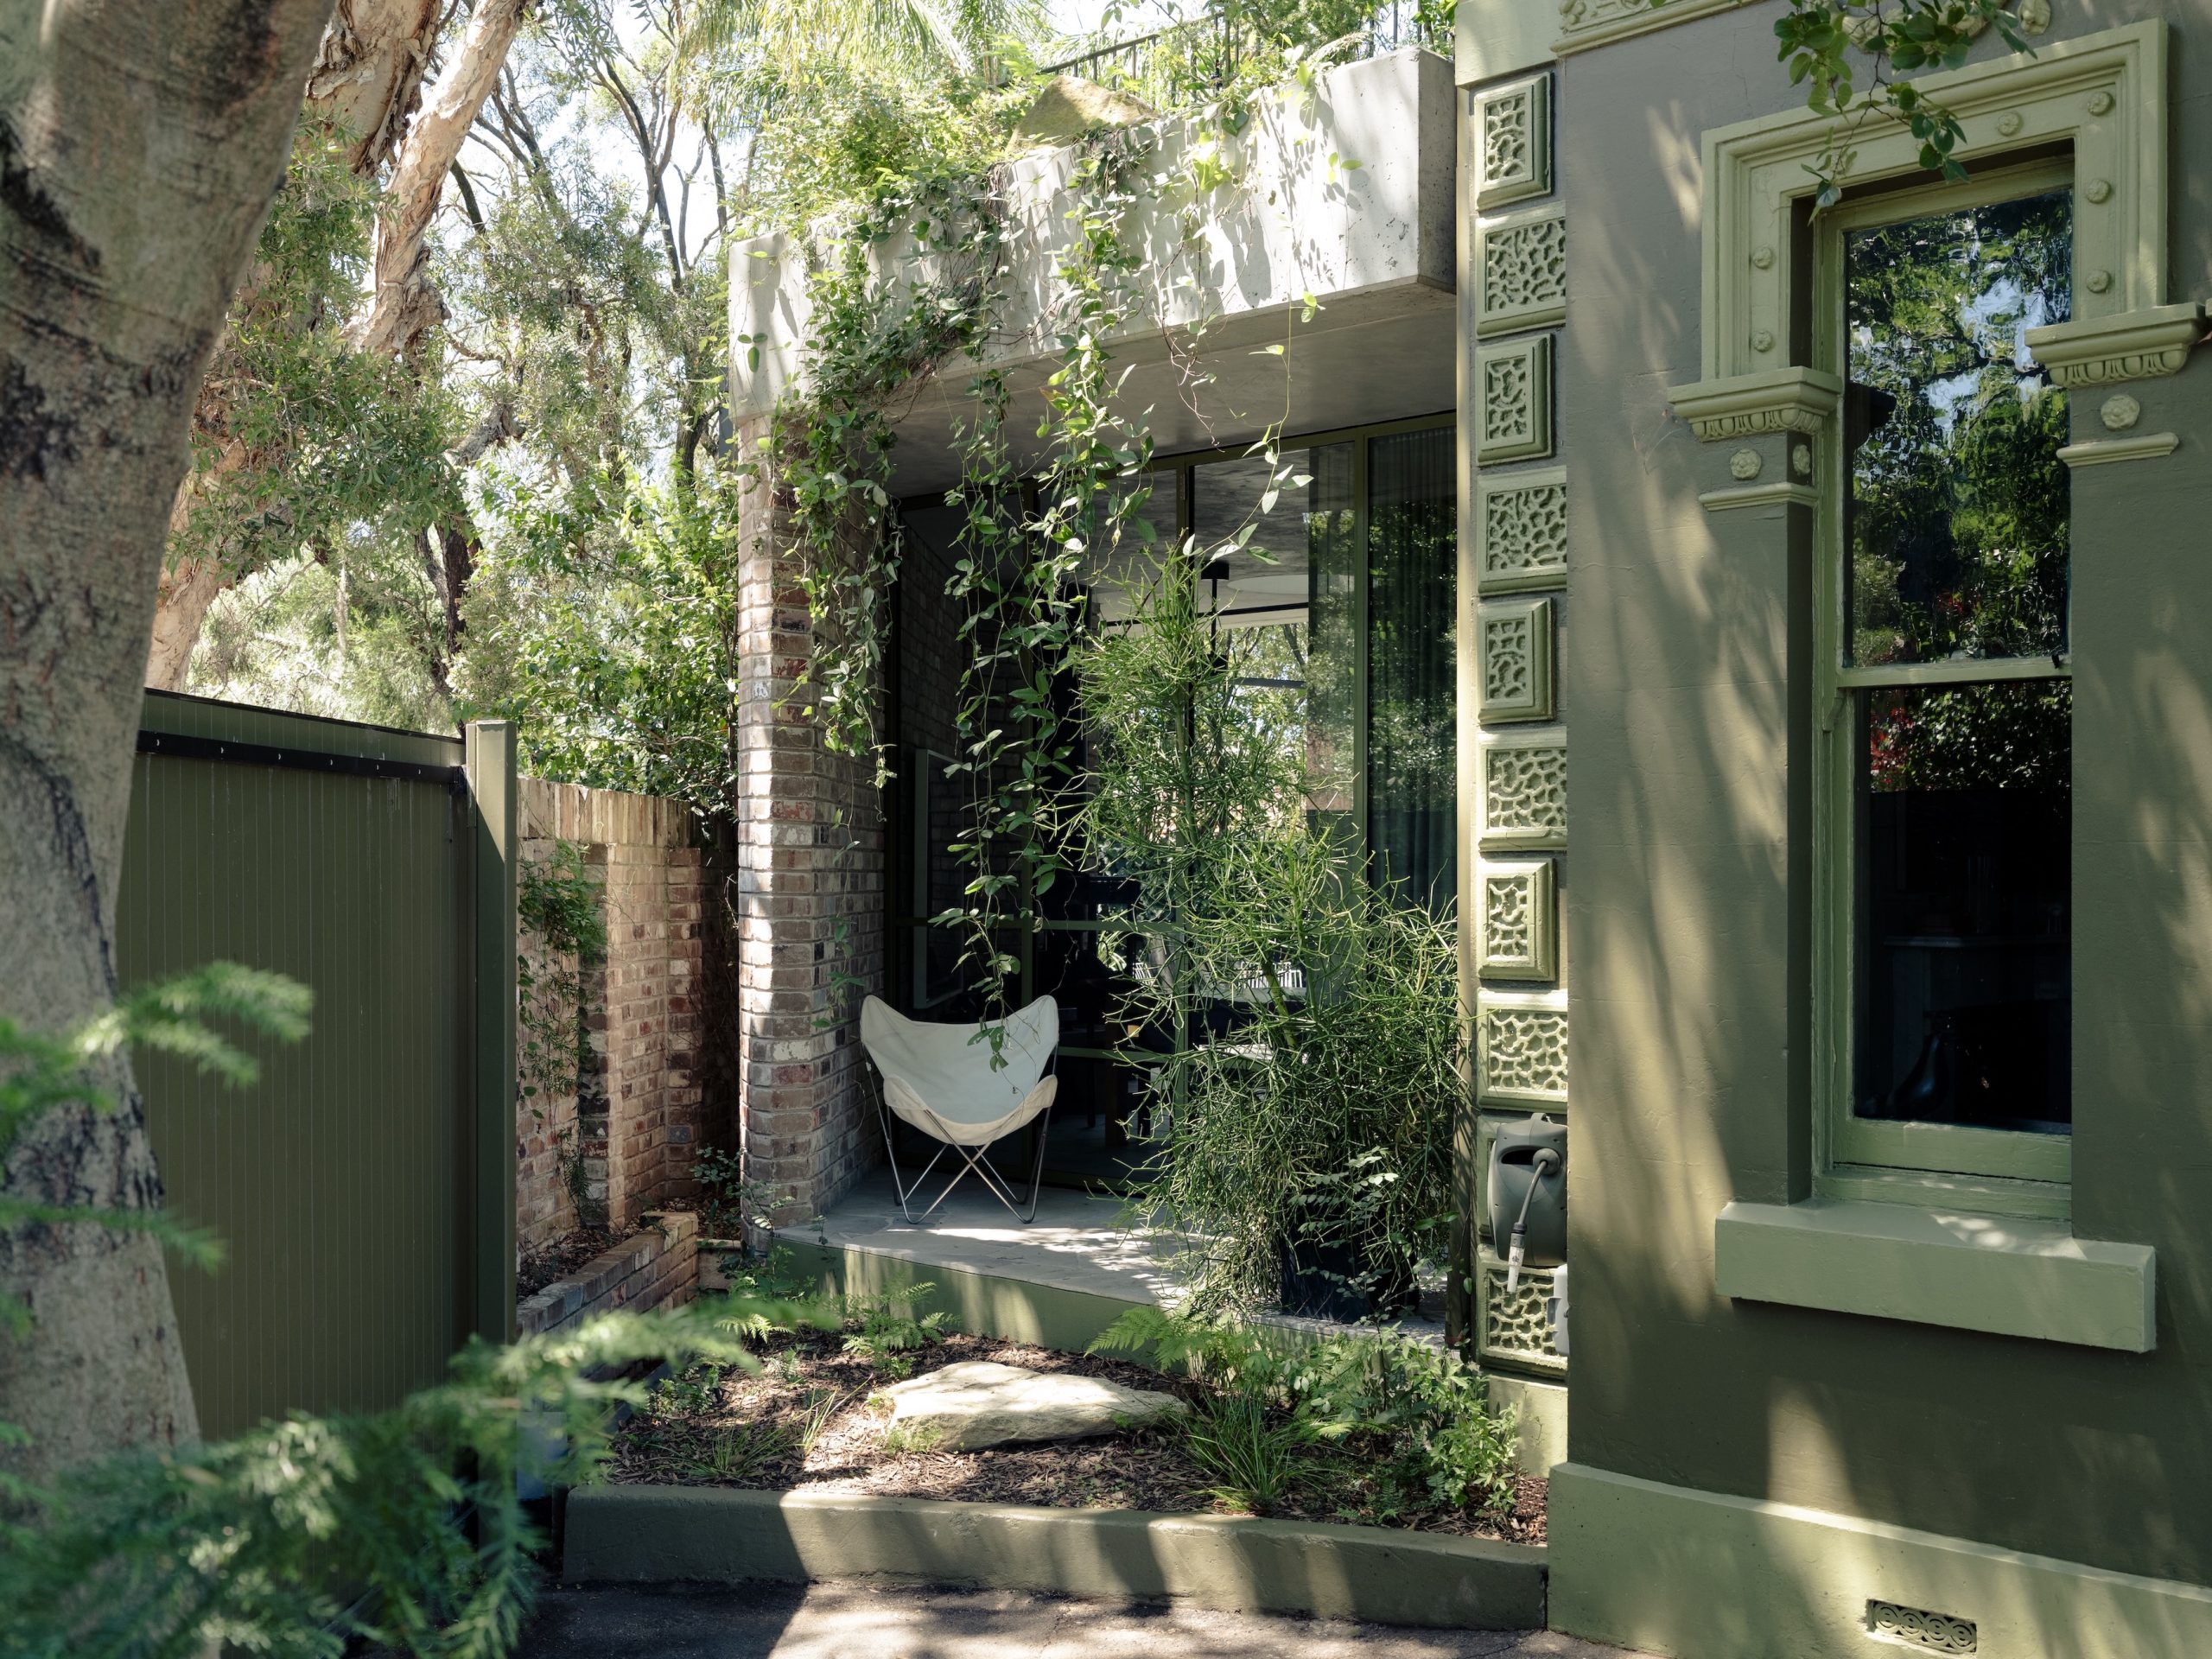
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.
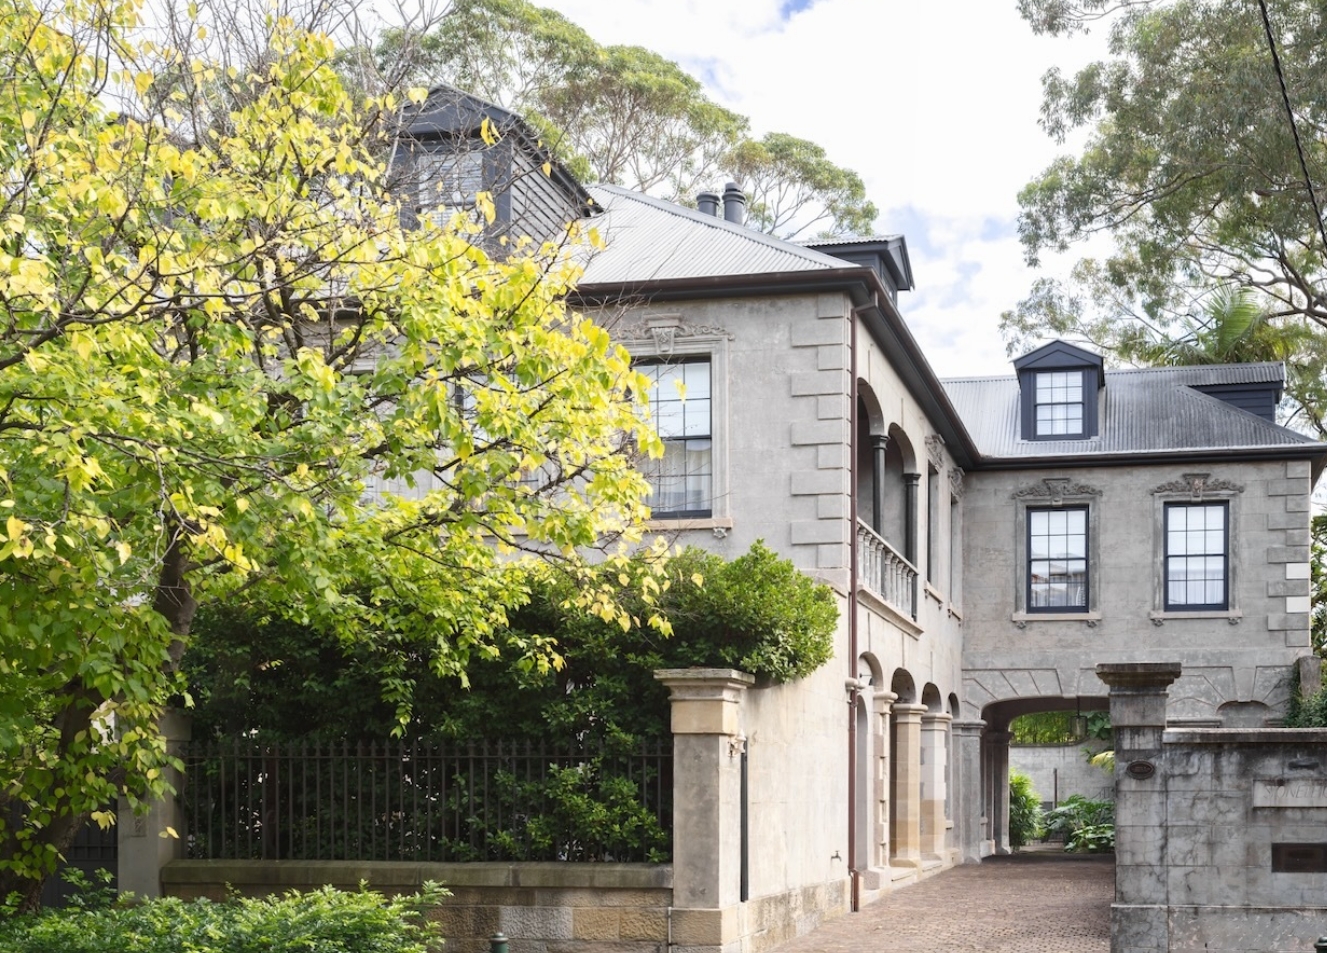
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …