





Real-Estate Scions Are Breaking a Cardinal Rule: Never Sell
The office-market downturn is forcing some of the city’s multigenerational families to make emotionally fraught decisions

 5 min

William Rudin, scion of one of New York City’s premier real-estate dynasties, says his grandfather built a property empire by following a cardinal rule: Never sell.
While the city’s office market wobbled during economic downturns, values and cash flows would always recover because workers came back during good times.
But last year, Rudin sold control of a 30-storey office tower in downtown Manhattan his family developed in the 1960s. This fall, the family agreed to part with 80 Pine Street, another financial district tower, after anchor tenant American International Group left.
“The world has changed,” said Rudin, the 69-year-old co-executive chairman of his family’s firm. “We have to take a cold hard look at our business in order to make sure there’s a foundation for the next generation.”
The office market’s severe downturn is forcing some of the city’s multi-generational family owners to do something they managed to avoid during world wars, financial meltdowns and a global pandemic: sell their core properties.
Families like the Rudins and the Kaufmans built their New York empires by passing these buildings from one generation to the next. The office properties steadily rose in value and provided a comfortable living for an expanding number of children, grandchildren, nieces and nephews.
“We and the other families did not sell,” said Jonathan Iger, chief executive of Sage Realty, the management firm running the 100-year-old Kaufman real-estate business founded by his great grandfather. “You see yourself through the dips and you come out—not just fine, but more than fine.”

Today, U.S. office vacancies are near record levels and demand looks permanently impaired by remote work and by companies doing more with less space. Properties that had been reliable cash cows now require substantial upgrades or other capital infusions to replace departing or shrinking tenants.
For many families in their third and fourth generation of ownership, it makes more sense to sell for whatever they can get. The Kaufman family agreed to sell a downtown office tower this year and are marketing another one in Midtown. Like others, the Kaufmans are selling the family jewels at values significantly below what they were five years ago.
Tracking the precise number of sales by these families is tricky. But real-estate investment banking firm Eastdil Secured says that New York real-estate families have sold about 10 office buildings over the past 24 months. In the previous decade there were fewer than five such deals.
“Instead of 50 different aunts and uncles getting distributions, they’re getting capital calls,” said Gary Phillips , an Eastdil managing director.
Individuals and small private owners have stakes in about one third of the 350,000 office properties tracked by data firm CoStar Group. The decision by a number of families to sell is part of a natural evolution under way in New York and other big cities.

Often the buyers are large developers or investment firms with the deep pockets to convert these buildings into other types of properties more in demand, especially rental apartments.
“Many landlords are going through this process,” said Michael Cohen, the patriarch of one of three New York families that led a sale of a Madison Avenue office building this year. The new owner plans to demolish it and convert the property to a different use.
These can be emotionally fraught decisions. Over the decades, more family members have gained a stake in the properties. They often have widely varying financial needs or incentives.
Tensions between family members who want to hold and those who want to sell have always simmered in the background. Today’s tough times have intensified these battles.

When values and profits are rising, “it’s harder to make a case to sell. Now there’s a sense of: ‘Wait a second. We’re not seeing improvement,’” said Peter Boumgarden, director of the Koch Center for Family Enterprise at Washington University in St. Louis.
New York City dynasties have played a major role in real-estate growth since the late 1800s. Many of the early family members were European immigrants who started real-estate companies that their children and grandchildren grew into empires. The Dursts, Milsteins and Trumps are among the New York families to shape the cityscape.
Families were able to hold on to their buildings by following low-debt strategies, which insulated them from market downturns and positioned them to profit when markets recovered.
Lately, some office markets are showing a few positive signs, as bosses call workers back to the office. But the buildings that stand to benefit are new ones or those in top-tier locations, like Rockefeller Center, that have gone through extensive upgrades. Tenants are moving to those amenity-laden spaces to give their employees more of an incentive to put up with lengthy commutes.
Many of New York’s real-estate families own older buildings in less desirable locations, offering few of the special features that attract tenants. They also have large vacancies that are costly to fill these days. Landlords feel the need to offer free rent and spend heavily on new interiors to compete.
“There’s little incentive for landlords to make a significant contribution,” said Stephen Siegel, chairman of global brokerage for real-estate services firm CBRE Group . “It’s money in and really no money out.”
Even with recent sales, the Rudins are keeping most of their office portfolio, which includes 14 other New York buildings. So are the Kaufmans. Some families are even making big investments in their aging office buildings, betting that they will be among the winners.
The Gural family last year led a group that agreed to invest new equity into the DuMont Building, on Madison Avenue, which the family has controlled for over 60 years. Partners who were used to getting disbursements from the property had to reach into their pockets to pay their share for capital improvements and paying down debt.
“It’s called a capital call, which is the most dreaded term in our industry,” said Jeffrey Gural , chairman of GFP Real Estate, which manages the family’s properties.
But the decision paid off. By putting in fresh money, the partners were able to negotiate a loan extension with the building’s creditors and attract tenants.
“I have yet to sell a building where I didn’t regret selling,” Gural said.
Yet other families are choosing to walk away from properties—even if they reinvested in them. The Rudins recently spent $100 million on renovations at 80 Pine’s lobby and building systems, adding a terrace and dining room. Now, William Rudin considers forking over any additional money a waste.
“Even if we spent money to fix up the building, the ceilings are too low, there are a lot of columns, the floors are too big,” he said. “It became clear to us we needed to stop putting capital back into the building.”
It was a gut-wrenching decision, letting go of what amounted to a family heirloom.
“When I go by 80 Pine Street, I remember the good times and I remember the bad times,” Rudin said. “But you’ve got to move on.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

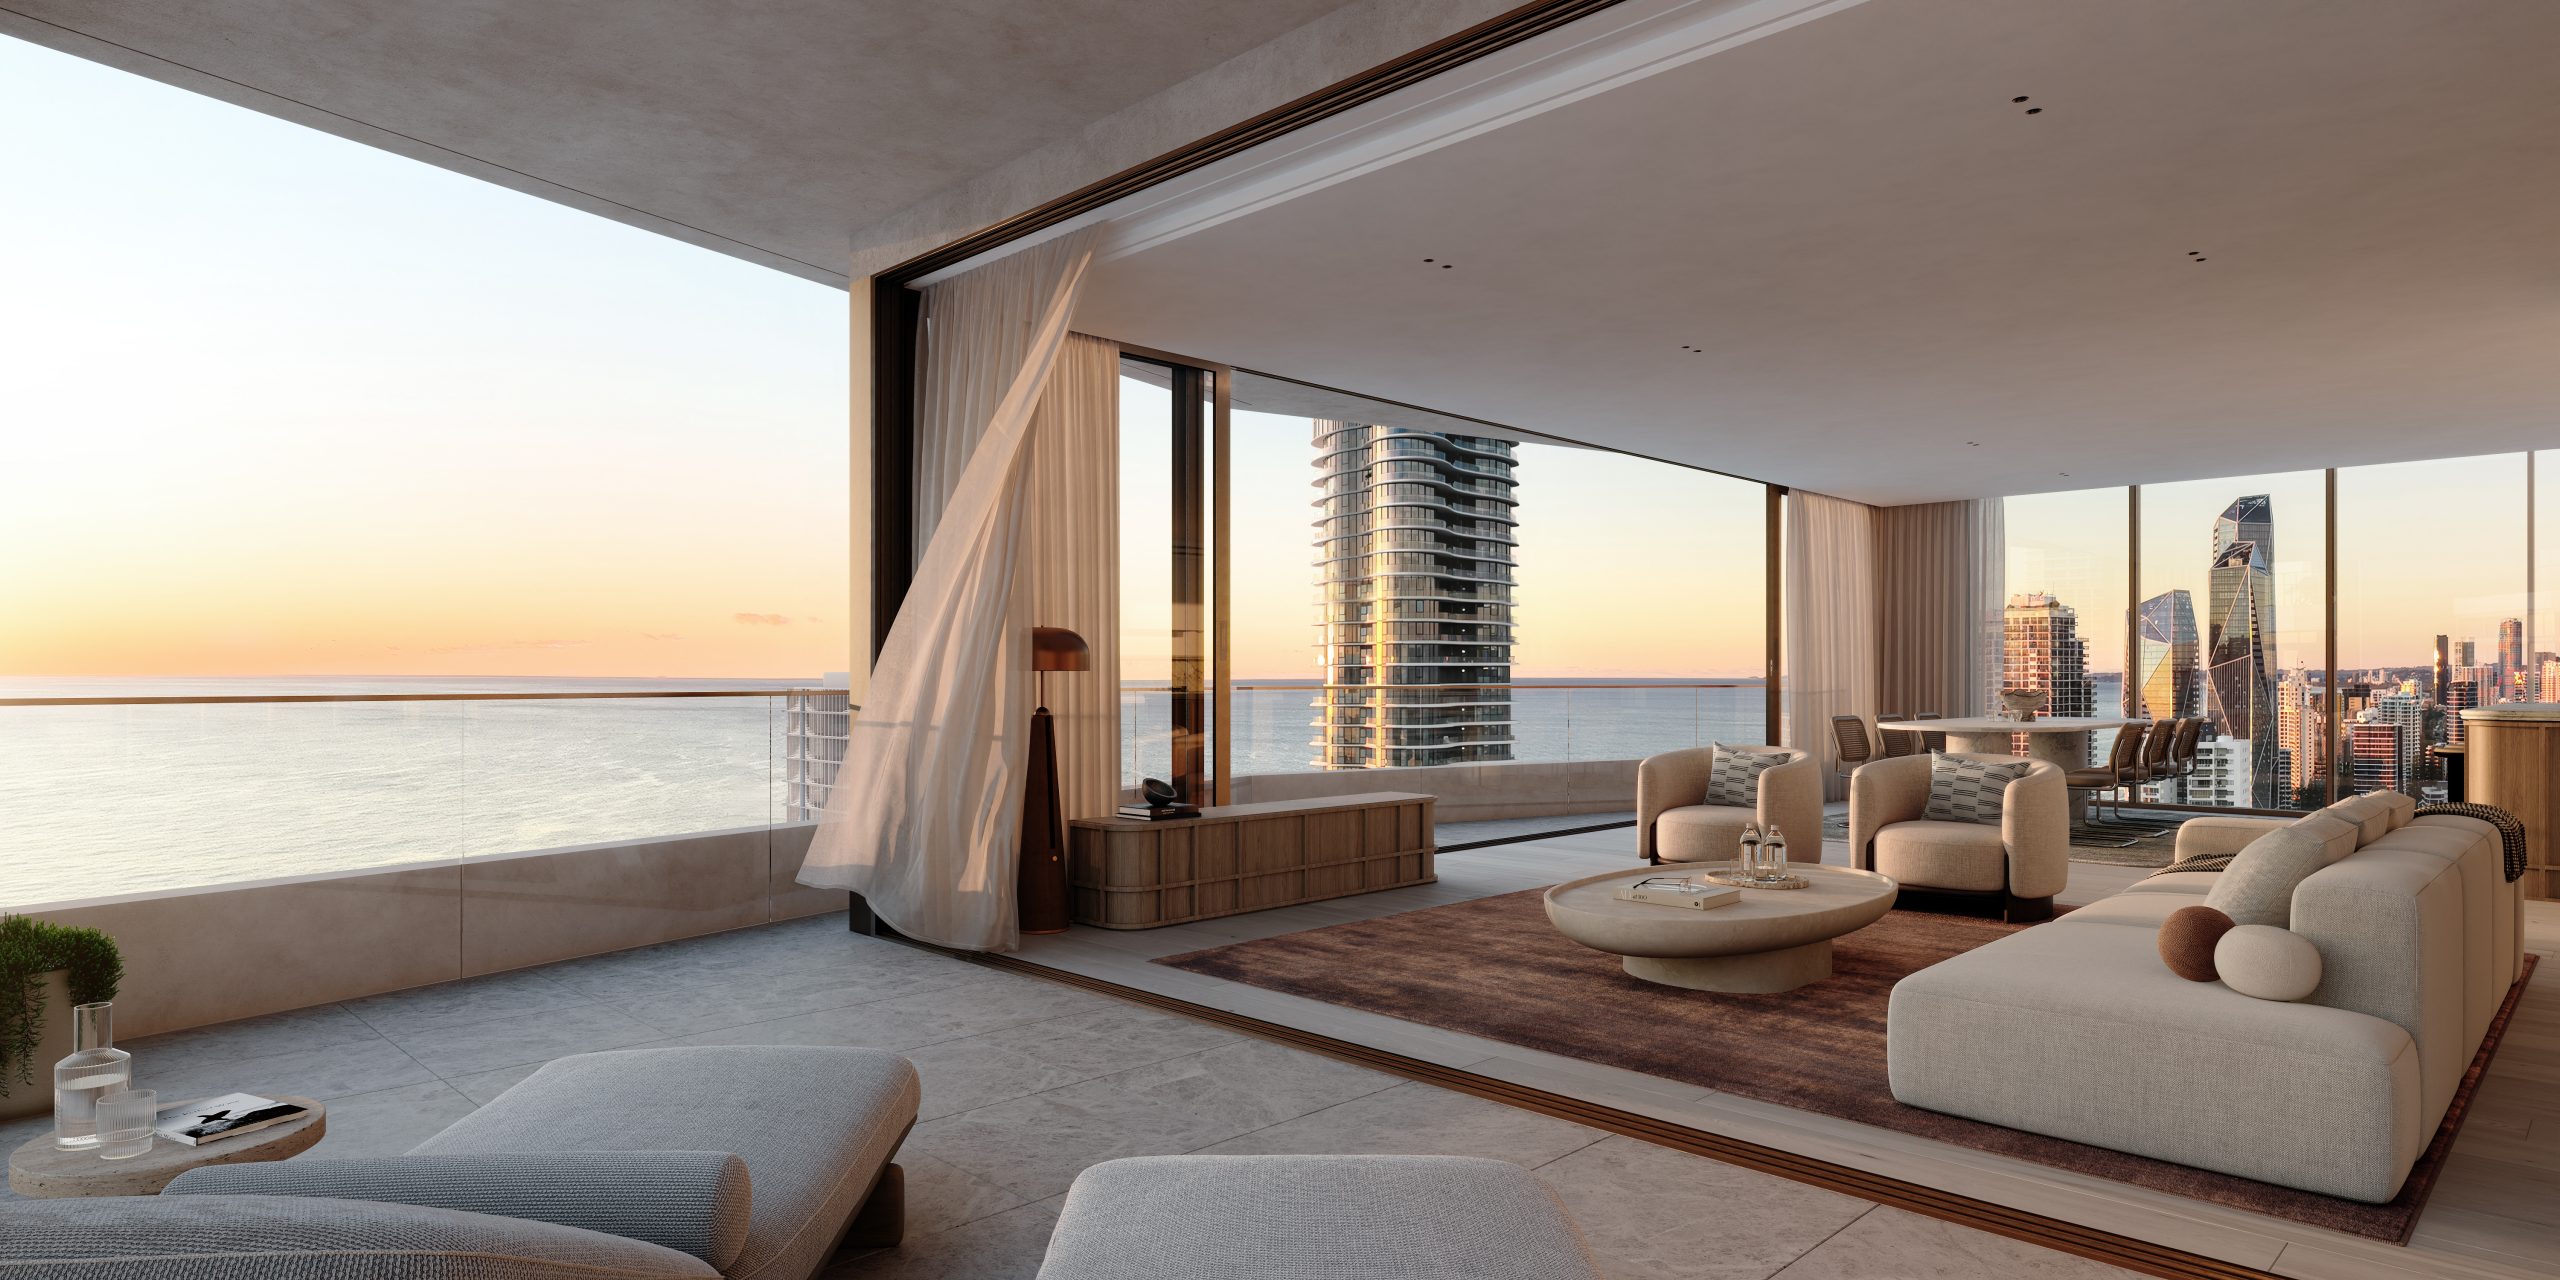
Mirvac’s 45-level Trielle has topped out at Yarra’s Edge, pairing riverfront apartments with wellness facilities, private dining and resident services.
3 min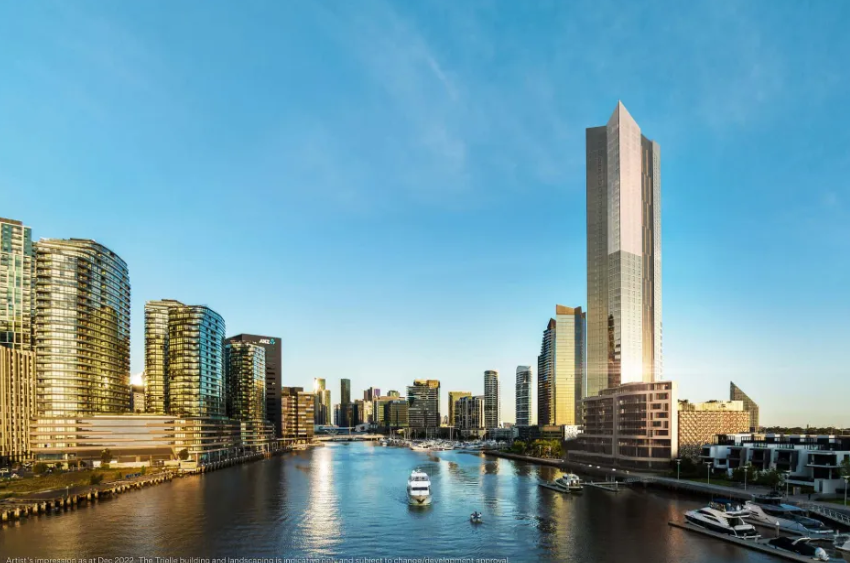
Mirvac has topped out Trielle at Melbourne’s Yarra’s Edge, with more than 70 per cent of the riverfront development sold and approximately 80 per cent of purchasers intending to make their apartment a home.
The figures, released on September 22, point to an owner-occupier audience for one of the precinct’s final residential towers. Mirvac began developing Yarra’s Edge in 2003, and its latest addition occupies one of the remaining absolute riverfront sites.
Mirvac CEO of Development Stuart Penklis said existing residents were among those moving up within the neighbourhood.
“Many purchasers already have a connection to Yarra’s Edge,” Mr Penklis said, describing buyers whose changing needs were encouraging an upgrade within the precinct.
“As one of the final residential towers within Yarra’s Edge, Trielle represents the culmination of more than two decades of creating one of Melbourne’s most established and sought-after waterfront communities,” Penklis said.
“Positioned on the Collins Street axis with absolute river frontage, Trielle offers residents a rare opportunity to enjoy sweeping views across the Yarra River, Melbourne skyline and Port Phillip Bay, while remaining seamlessly connected to the CBD. With Trielle now more than 70 per cent sold, we’re continuing to see strong demand from buyers seeking quality homes in established locations.”
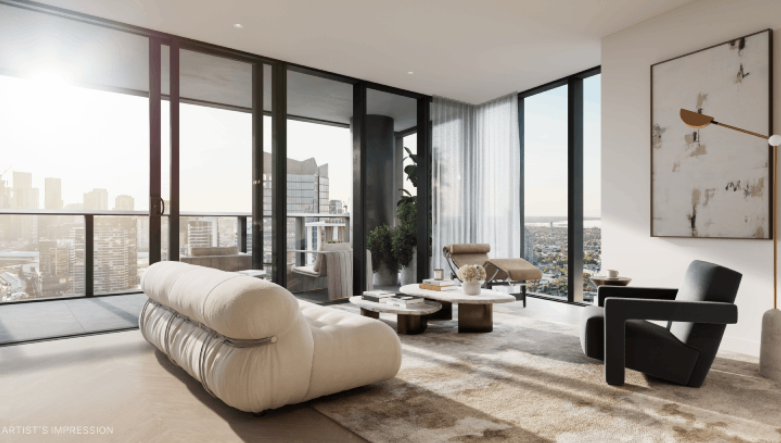
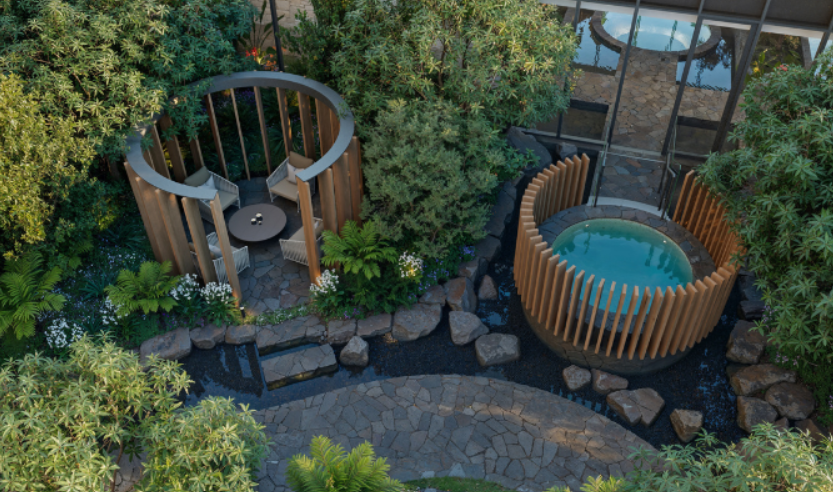
The developer also flagged a penthouse and sub-penthouse collection with larger layouts, premium finishes and broad outlooks. The planned wellness centrepiece, The Oasis, encompasses a 900-square-metre elevated urban rainforest.
Mirvac General Manager Residential Development Victoria Elysa Anderson said Trielle had resonated strongly with buyers seeking a rare lifestyle offering in Melbourne.
“Opportunities to secure a new luxury residence on a riverfront site of this calibre are incredibly rare, particularly within a community like Yarra’s Edge,” Anderson said.
“What makes Trielle unique is the combination of exceptional views, world-class residential facilities and the lifestyle that already exists around it. Residents are buying into a mature waterfront community with parks, promenades, dining, wellness and strong community connections already in place.”
The 45-level tower brings a substantial new presence to that waterfront. Its residential offering spans one-, two-, three- and four-bedroom apartments, with Signature, Prestige and Sub-Penthouse collections accommodating different household sizes. The north-facing position connects the apartments visually to the river and city beyond.
Seven storeys above the promenade, the planned Oasis combines planting and a running stream with a Scandinavian-inspired wellness club developed with spa specialist Naomi Gregory. Facilities include a 25-metre lap pool, hot magnesium pool, sauna, hydrotherapy, a gym, yoga and Pilates room, and treatment spaces.
The amenity extends beyond exercise. Residents will have access to The Biblioteca library and workspaces, ground-floor work pods, and The Salone piano lounge. A private Chef’s Table dining room offers a setting for larger gatherings, while a cinema, games room and sports lounge broaden the entertaining options. Concierge services and a dog-wash area support everyday routines.
Trielle comprises a collection of one, two, three and four-bedroom residences. Reflecting strong demand from owner occupiers, approximately 80 per cent of purchasers to date intend to live in their homes, highlighting the project’s appeal to those seeking a long-term waterfront lifestyle.
Mirvac has recently delivered The Albertine, a premium apartment development on the edge of Melbourne’s CBD, and is nearing completion of Prince & Parade in Brunswick, further strengthening its portfolio of thoughtfully designed apartment communities in some of Melbourne’s most sought-after urban locations.
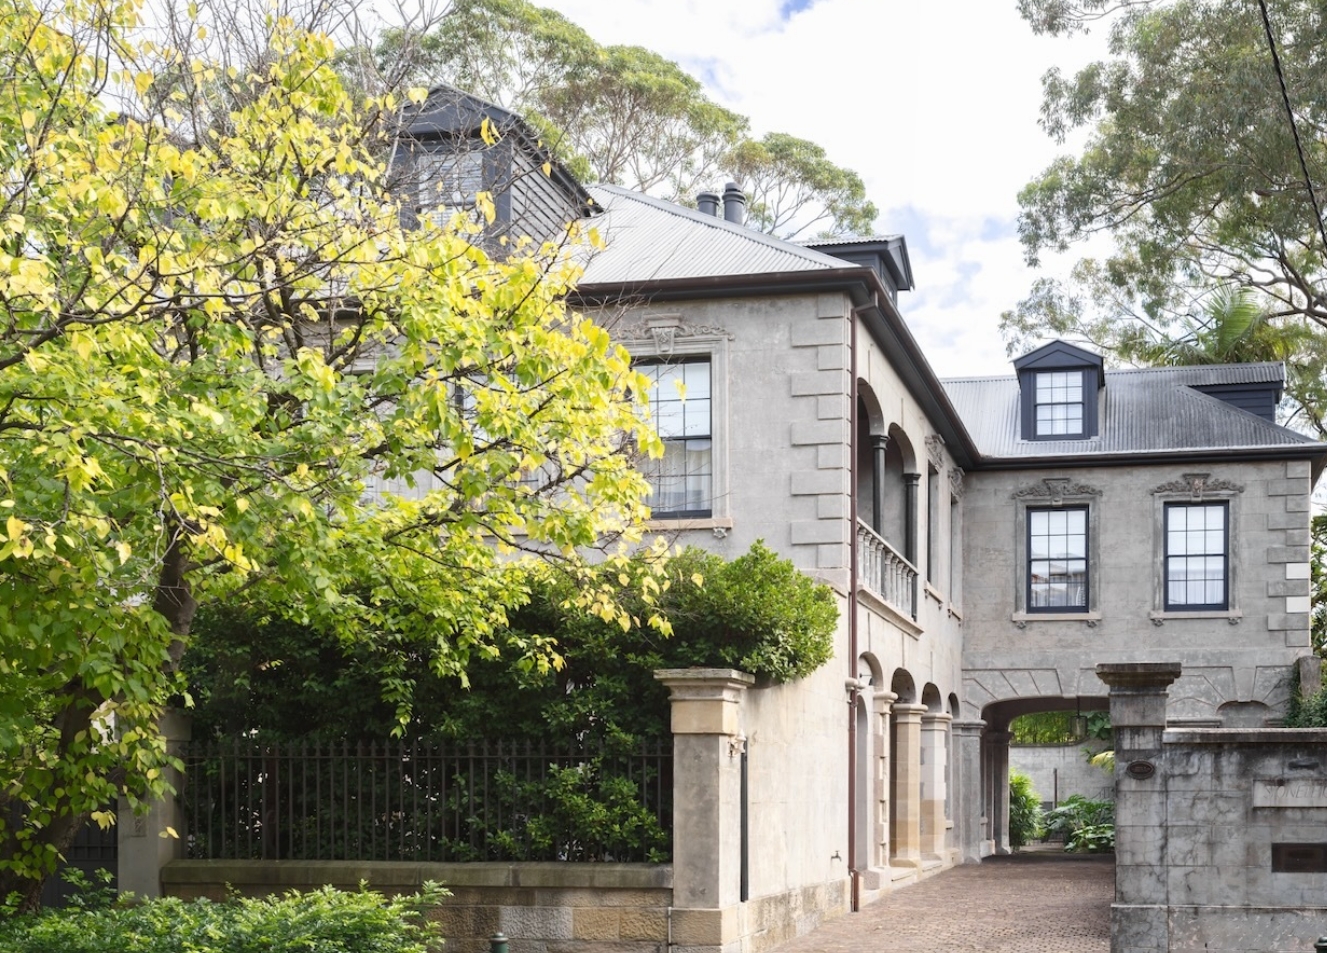
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …

ABC Bullion has launched a pioneering investment product that allows Australians to draw regular cashflow from their precious metal holdings.


