HOW TO DEFINE YOUR HOME DESIGN STYLE WITH CONFIDENCE
From colour to texture to what’s beneath the surface, here’s how to create a home that looks great and works for your lifestyle.
 2 min

Whether you’re building from scratch or renovating, locking in a cohesive design style can be one of the trickiest – and most rewarding – parts of the process. It’s not just about looks; it’s about making choices that suit your lifestyle, climate, and long-term comfort.
New resources from building experts, including a detailed style guide by CSR with inspiration from brands such as Bradford, Hebel, Monier, Cemintel, and PGH, are helping homeowners better understand the connection between materials, performance, and aesthetics.
Here are five key elements to consider when defining your home’s style and getting it right from the start.
1. Start with Style
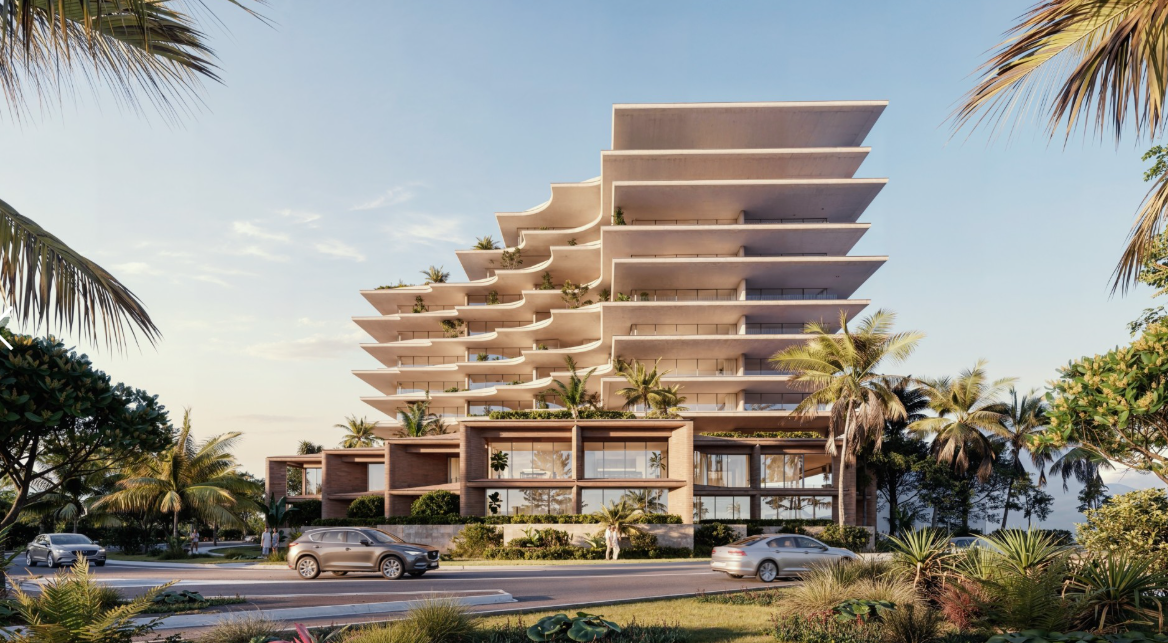
Understanding your overall aesthetic—whether it’s Classic, Coastal, barnhouse, Industrial, or something in between—makes every other decision easier. It affects everything from the roofline to your cladding choice. For example, a Contemporary home often features clean lines and subtle contrasts, while an Industrial style leans toward bold materials and darker colours.
2. Make Colour Count
The right colour palette doesn’t just change how a home looks – it transforms how it feels. Neutral tones like soft greys and crisp whites work well in breezy, coastal designs, while dark charcoals and blacks add drama to modern or industrial exteriors. Rich browns and terracotta tones are gaining traction too, particularly for homes that aim to blend into natural surroundings.
3. Layer in Texture
Texture is one of the most underrated tools in exterior design. Think rough brick next to smooth cladding, or timber detailing beside rendered walls. Using materials with different surfaces can highlight key architectural features and add interest to otherwise flat façades. It’s also an easy way to bring character to newer builds.
4. Don’t Overlook the Invisible
Good design doesn’t stop at what you can see. The hidden layers – insulation, wall wraps, roof sarking – are critical in how liveable and energy-efficient your home is. These are choices that are often hard to change later, so it pays to get them right from the outset.
5. Think Beyond the Walls
Landscaping is more than just a finishing touch. The right mix of plants, materials and pathways can enhance your home’s style and create a seamless indoor-outdoor connection. Match fencing and garden materials to your architectural choices for a polished, intentional feel – and make sure your outdoor areas are as functional as they are beautiful.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.
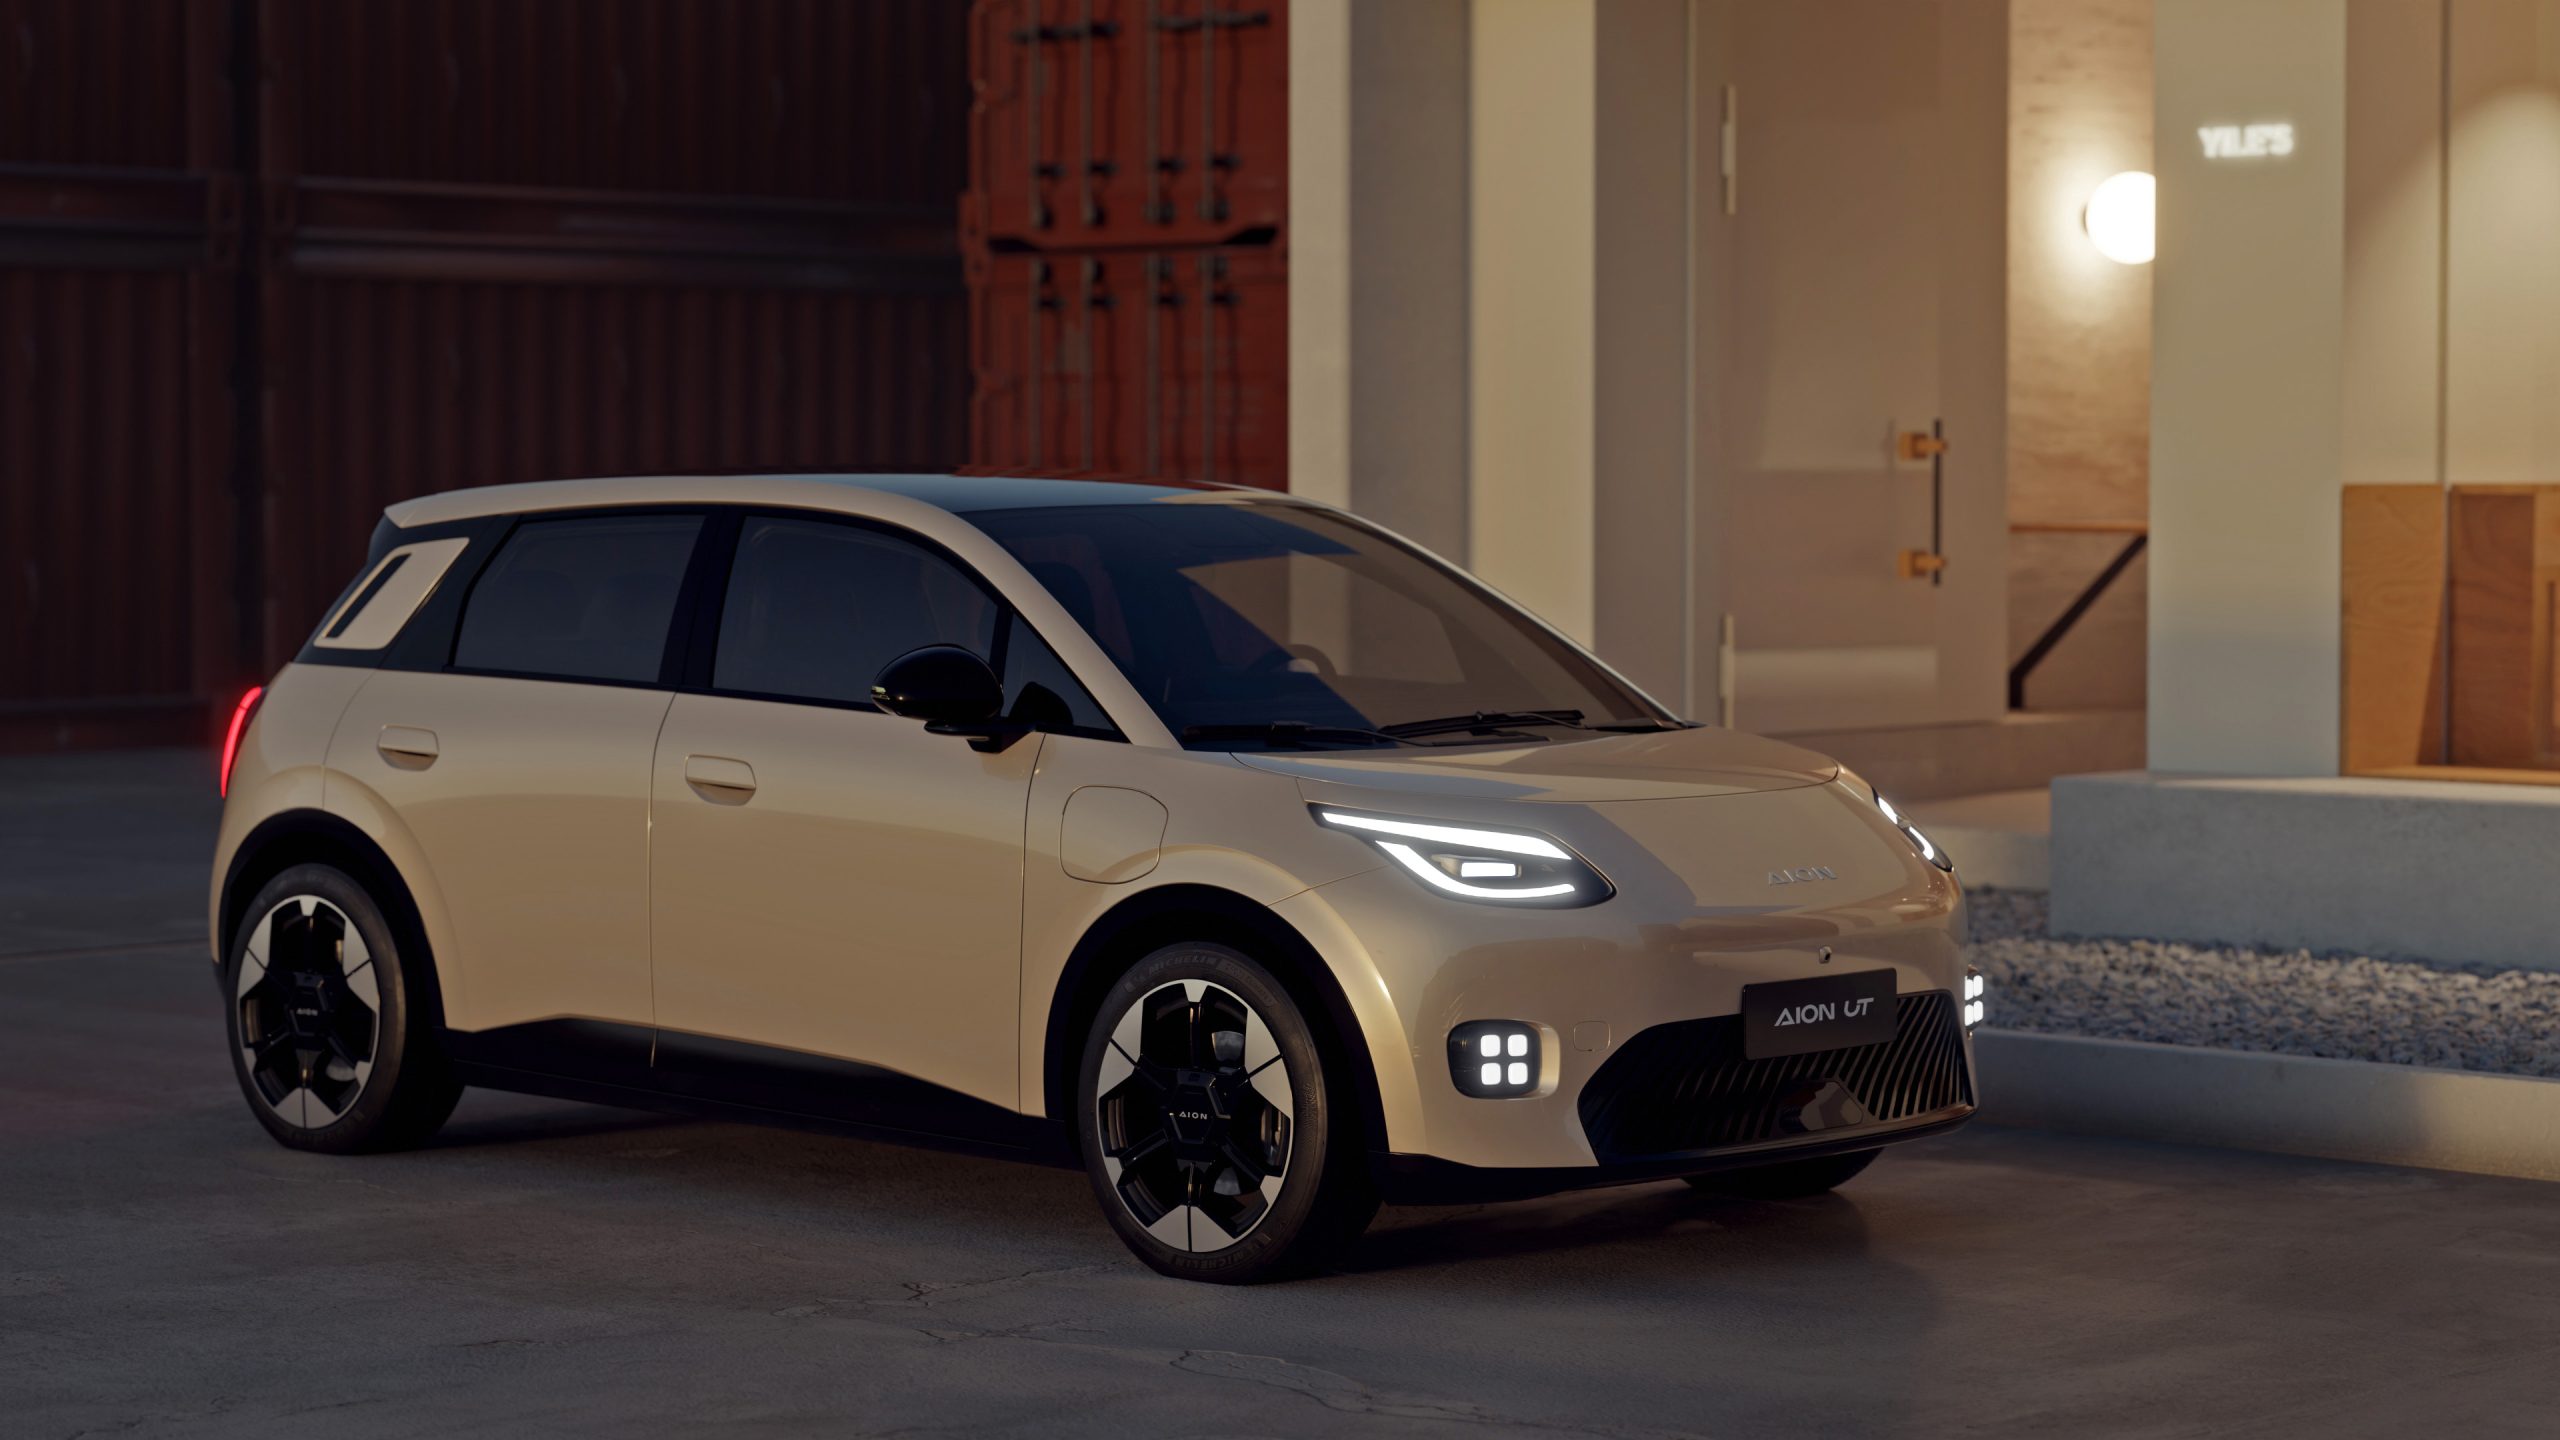
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.
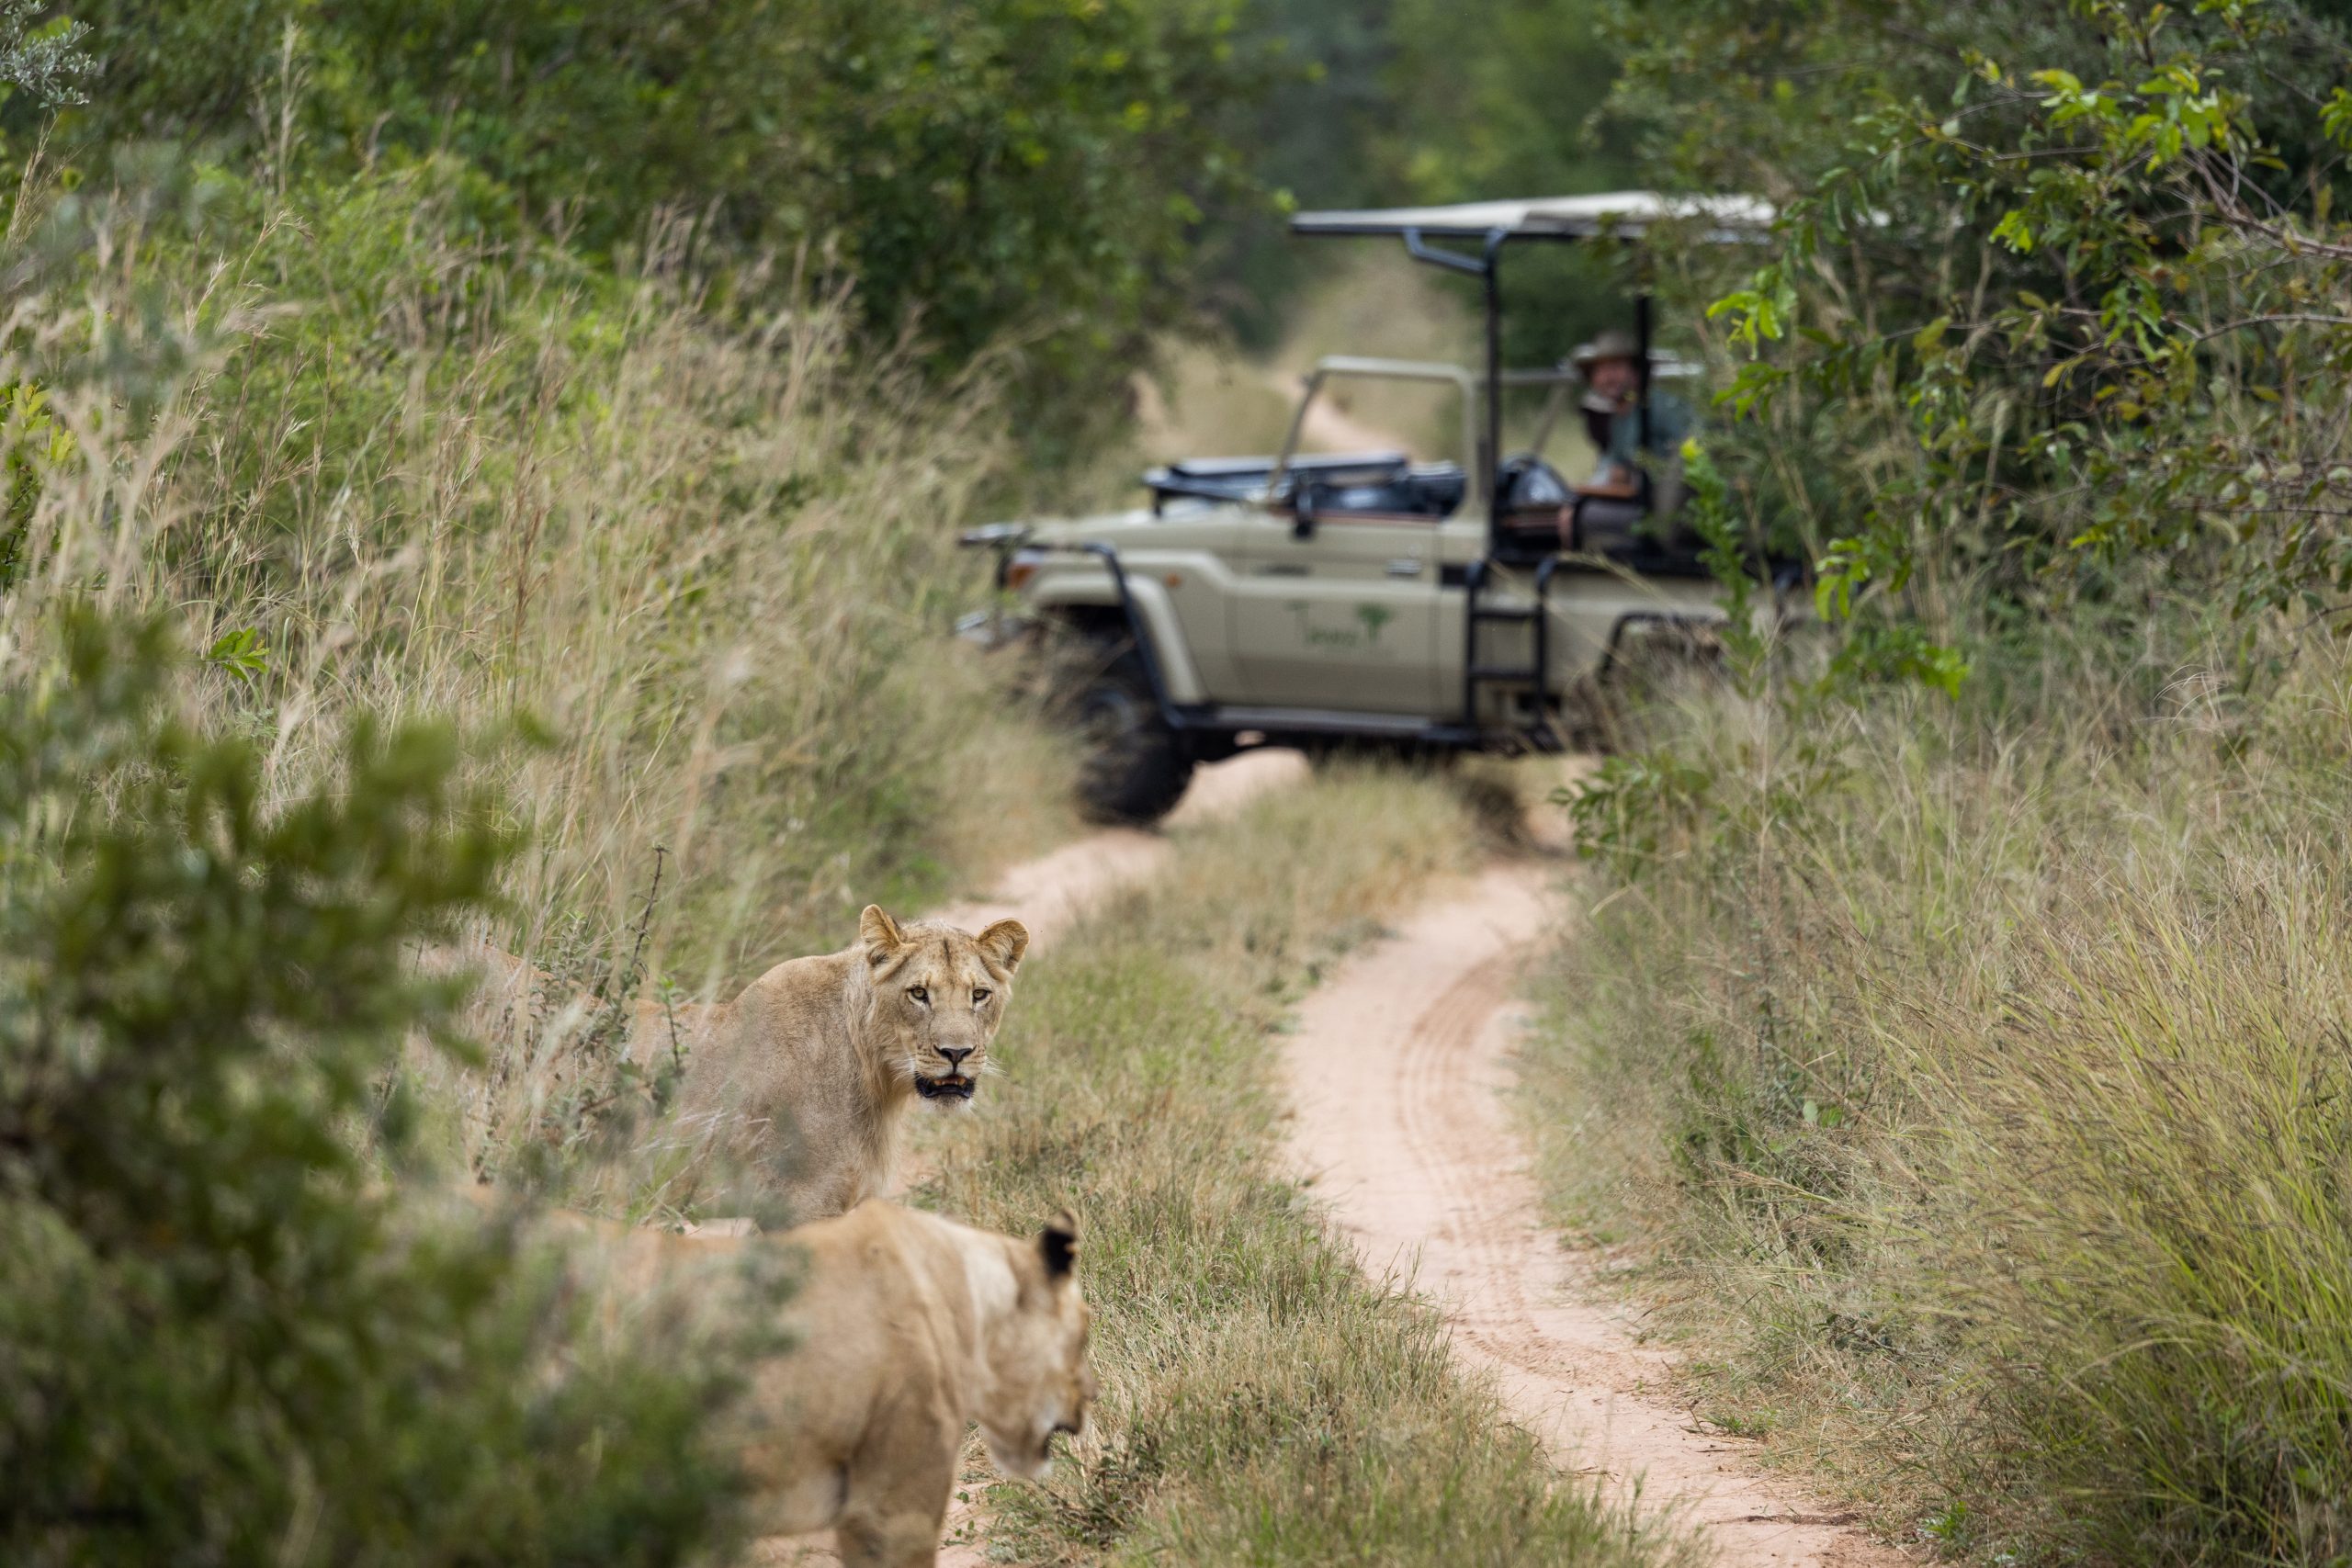
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.