‘Now It’s the Happiest Room in the House.’ Wallpaper Converts Share Their Stories.
Homeowners hesitate to install even undeniably gorgeous wallcoverings. Here, the stories of folks glad they conquered their wallpaper willies.

 3 min
The idea of wallpaper elicits so much apprehension in homeowners, New York designer Francis Toumbakaris purposely uses the term “wallcovering” when speaking to clients about it. Yet decorating websites and media accounts teem with instances of the stuff. “It transforms a room and gives it personality,” said Casey Keasler, founder of design studio Casework, in Portland, Ore.
So what keeps folks from hanging the gorgeous material, and how do homeowners get over these wallpaper willies? Here, some case studies of conversions.
Hangup: It’s too pricey.
Budget concerns can hamstring homeowners. Home-services company Angi estimates that wallpaper can cost as much as $12 a square foot for labor and materials, while painting tops out at $6. “If the wall surface needs work beforehand, prices go up,” said Bethany Adams, an interior designer in Louisville, Ky. And Keasler notes that paper can cost as much as $400 a roll.
Antidote: Baby steps
New York designer Tara McCauley says homeowners can get more hang for their buck by using paper strategically. In an apartment in Brooklyn whose homeowners sweated the bottom line, she coated only the hallway with a dark-blue pattern inspired by Portuguese tiles. “It added so much impact,” McCauley said of the modest use. The designer adds that another way to save money is by hanging what she calls the gateway drug to wallpaper: patternless grass cloth. With no need to align a motif, the material goes up quickly and costs less to install, she says, “but it adds visual depth in a way plain paint never could.”
Hangup: I’ll get sick of it
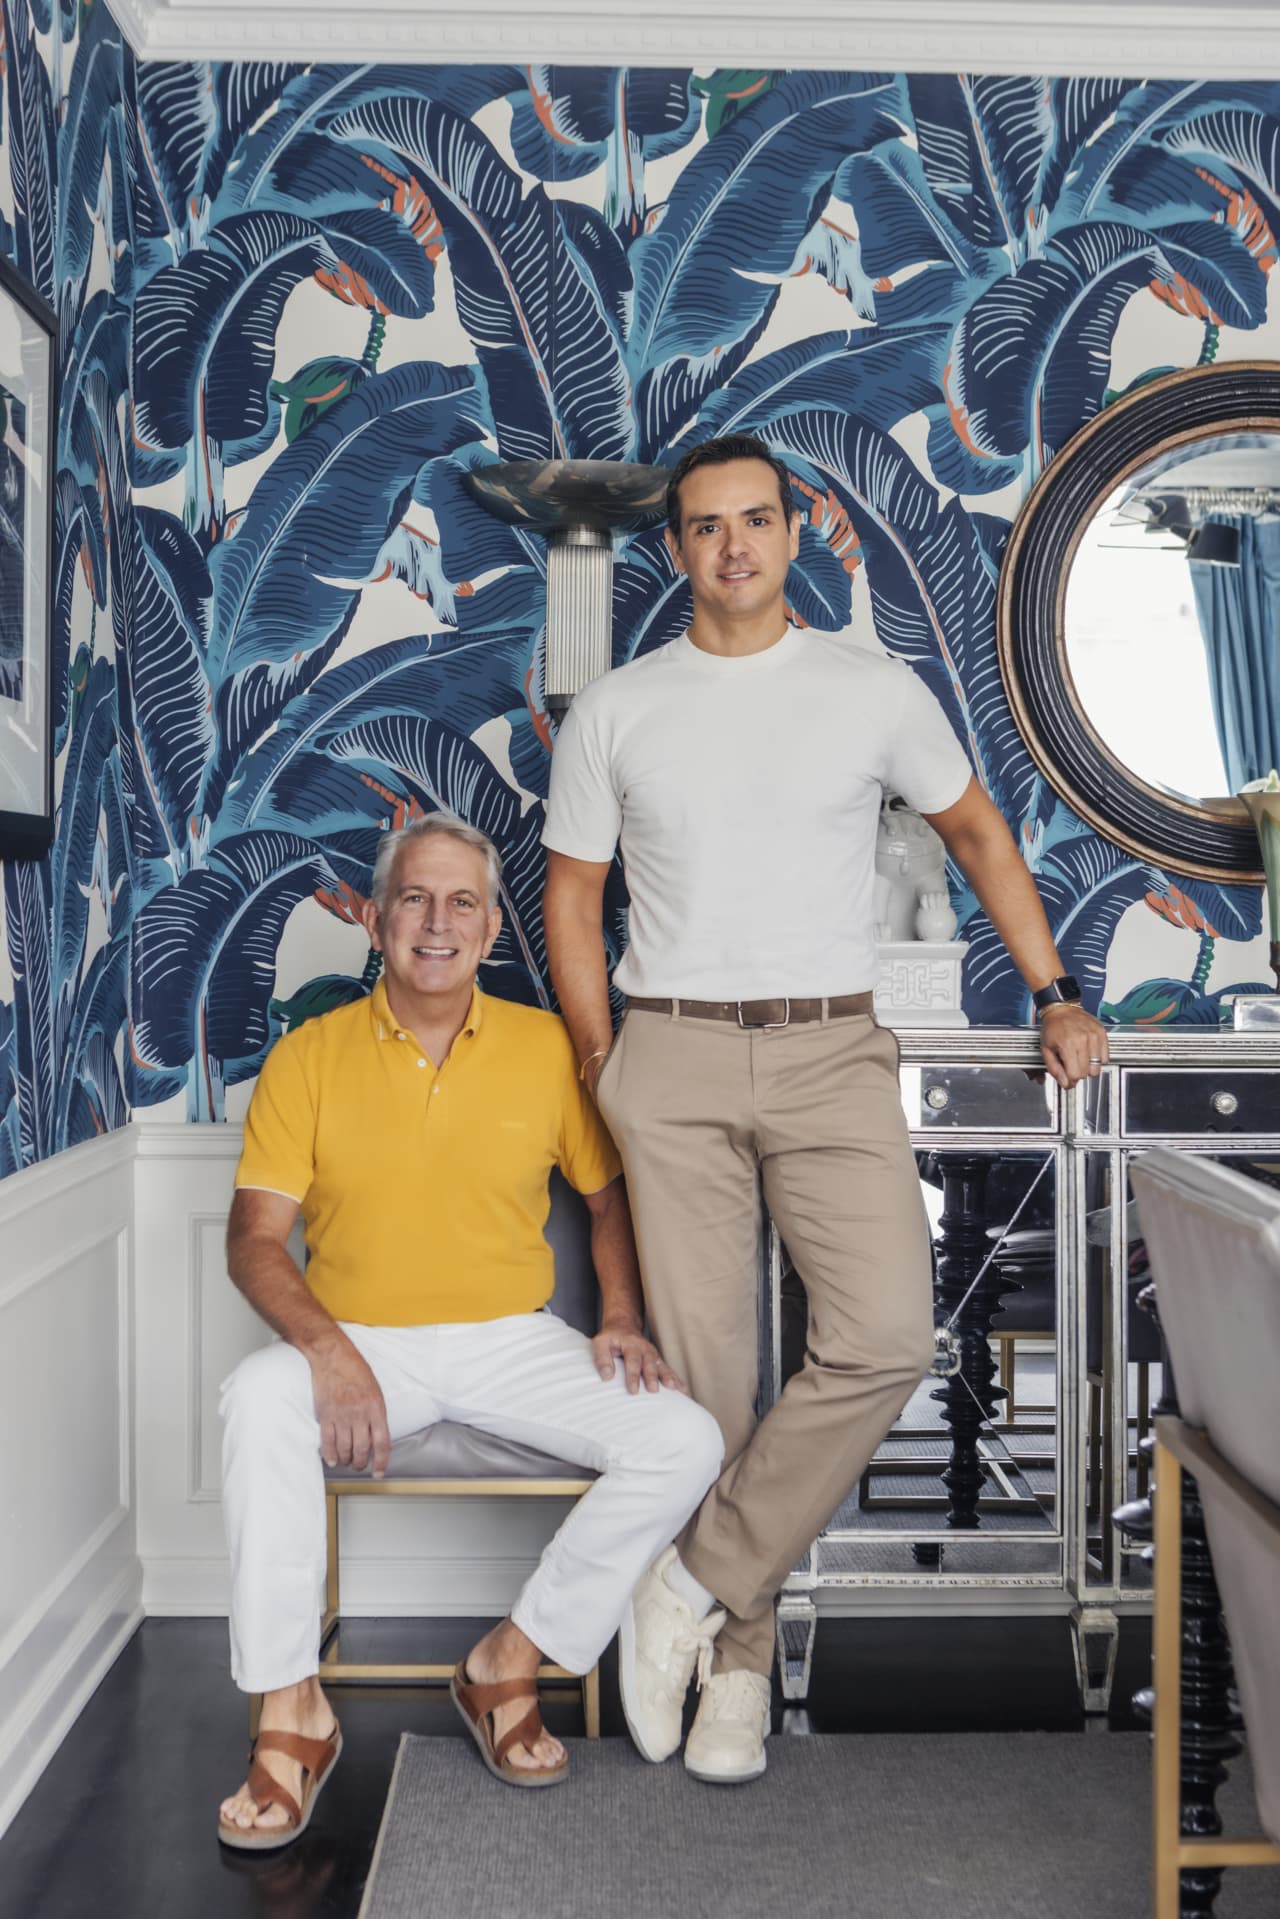
A fear of commitment stops many would-be wall paperers, who worry about having a change of heart later. Erik Perez, a design publicist with his own firm in Los Angeles, campaigned hard for what he thought was the perfect old-Hollywood look for his and his husband’s dining room—a maximalist, leafy green wallpaper made famous by the mid-20th-century decoration of the Beverly Hills Hotel. His husband, Paul Hardoin, a voice-over actor, resisted. “Is it going to go out of style? Will I tire of it? Will it affect resale value?” he worried.
Antidote: Low-use spaces
Infrequently used rooms can carry a bold choice long-term. Of the Brooklyn hallway she wrapped in blue, McCauley noted, “It’s a pass-through, so you don’t get overwhelmed by a bold pattern.” Ditto powder and dining rooms, like that of Perez, who said, “We only used that room when we were entertaining and it was too cold to be outside.”
It took three years, but Hardoin caved when the banana-leaf pattern became available in blue. “I thought it looked cool,” Hardoin said. He took the leap, knowing his sister Annette Moran (a wallpaper enthusiast) would be their DIY installer. “Now it’s the happiest room in the house,” he said.
Hangup: It’s dated
When Sarah and Nate Simon bought a historic home in Louisville, Ky., the walls sported oppressively dark patterns, including big, repeating medallions set in a grid. Sarah recalls thinking, “ ‘Not this! What’s the opposite of this?’ In my mind that would be paint.” Even for folks who haven’t pulled down awful examples, “the word ‘wallpaper’ can take them back to flowery patterns of the ’50s and ’60s that feel very dated,” said Toumbakaris.
Antidote: Modernity
“Wallpaper does not mean what it used to. It can be meandering, abstract, ombre or sisal,” said Simon’s interior designer, Bethany Adams. She suggested a sophisticated Chinoiserie that New York designer Miles Redd, in a collaboration with Schumacher, updated with an aqua colorway. Adams explains that like most Chinoiseries, this pattern doesn’t repeat for more than 8 feet. “You get a peripatetic design that keeps the eye engaged,” she said. “It’s looser.” Said Simon of her dining room today, “It’s a complete transformation, like art on my walls.”
Stereotypes of fusty florals and pitiless patterns fall away when designers present homeowners with contemporary picks. Still, sometimes the conversion takes time. One of Keasler’s clients, gun-shy after removing old paper, came back a year later, ready. “We chose a clean classic style that was graphic and minimal for a modern edge in the bathroom,” said the designer.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.

New research suggests that bonuses make employees feel more like a mere cog in a wheel.
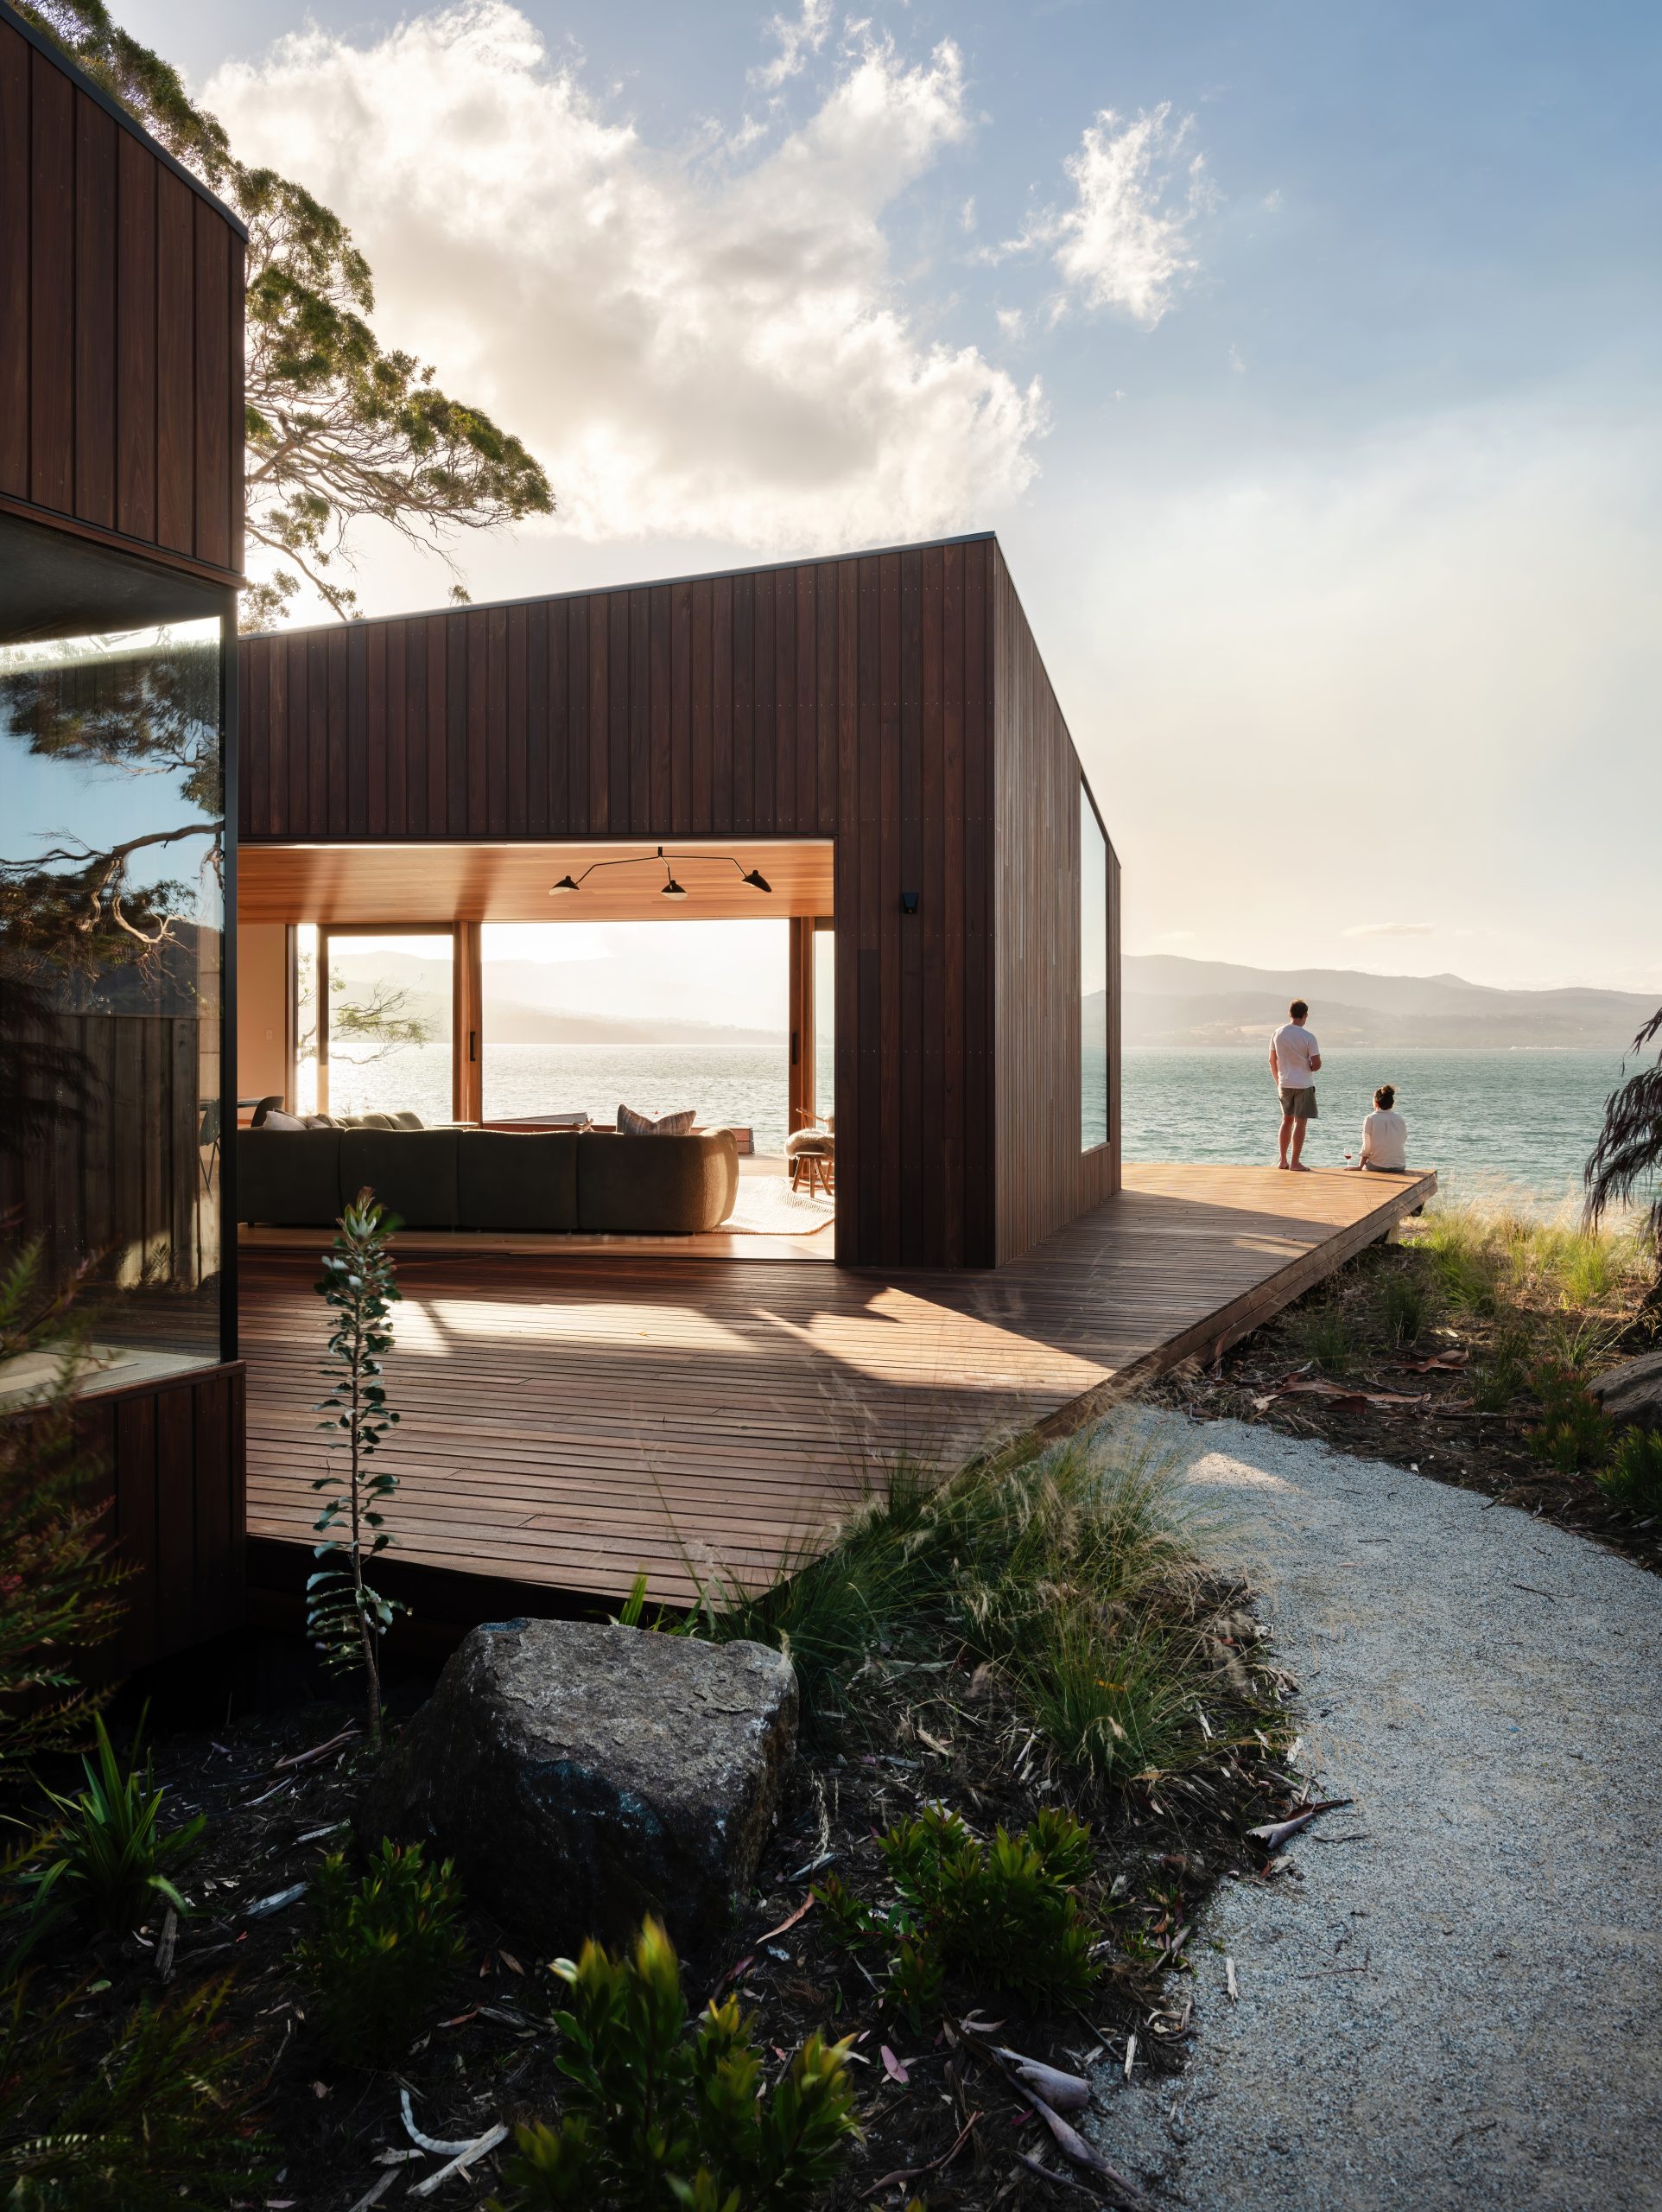
From the shacks of yesterday to the sculptural sanctuaries of today, Australia’s coastal architecture has matured into a global benchmark for design.