Investing in Nature Is Gaining Traction. Will It Be Enough?

Investing in nature to address climate change, support biodiversity, and protect ocean health—and more—is expected to reach record levels this year in response to more regulation and market demand, according to Cambridge Associates, a global investment firm.

Still, the amount of private capital invested to support natural systems will fall far short of what’s needed, according to the annual “State of Finance for Nature” report published in December from the United Nations Environment Programme.

A big reason is that nearly US$7 trillion in public and private finance was directed to companies and economic activities in 2022 that caused direct harm to nature, while only US$200 billion was directed to so-called nature-based solutions, or NbS—investments that protect, conserve, restore, or engage in the sustainable management of land and water ecosystems, as defined by the United National Environment Assembly 5, or UNEA5, the report said.

“Without a big turnaround on nature-negative finance flows, increased finance for NbS will have limited impact,” it said.

But the report also said that the misalignment “represents a massive opportunity to turn around private and public finance flows” to meet targets set by the United Nations Rio Conventions on climate change, desertification, and biodiversity loss.

The conventions aim to limit climate change to 1.5 degree Celsius above pre-industrial levels, protect 30% of the earth’s land and seas by 2030, and to reach “land degradation neutrality” by 2030. Reaching those goals will require more than double the amount of current levels of nature-based investing by 2025, to US$436 billion, and nearly triple today’s levels to US$542 billion by 2030, the report said.

Most of the US$200 billion invested in NbS today is by governments, but private investors contributed US$35 billion—including US$4.6 billion via impact investing funds and US$3.9 billion via philanthropy. The largest source of private finance was in the form of biodiversity offsets and credits. [An offset is designed to compensate for biodiversity loss, while a credit is the asset created to restore it].

Many wealthy individuals and families concerned about climate change and the environment so far have focused their investment dollars on climate solutions and innovations in technology and infrastructure, or in technologies supporting food and water efficiency, says Liqian Ma, head of sustainable investment at Cambridge Associates.

But “increasingly there is growing awareness that nature provides a lot of gifts and solutions if we prudently and responsibly manage nature-based assets,” Ma says.

Investments can be made, for instance, in sustainable forestry and sustainable agriculture—which can help sequester carbon—in addition to wetland mitigation, conservation, and ecosystem services.

“Those areas are not in the mainstream, but they are additional tools for investors,” Ma says.

Finance Earth, a London-based social enterprise, is among the organizations working to make these tools more mainstream by creating a wider array of nature-based solutions in addition to related investment vehicles.

Finance Earth groups nature-based solutions into six themes: agriculture, forestry, freshwater, marine/coastal, peatland, and species protection. Supporting many of these areas are an array of so-called ecosystem services, or benefits that nature provides such as absorbing carbon dioxide, boosting biodiversity, and providing nutrients, says Rich Fitton, director of Finance Earth.

Each of these ecosystem services are behind existing and emerging markets. Carbon-related disclosure requirements (at various stages of approval in the U.S. and elsewhere) have long spurred demand for carbon markets, the most mature of these markets.

Cambridge Associates, for instance, works with dedicated asset managers who have been approved by the California Air Resources Board to buy carbon credits, Ma says.

In its annual investment outlook, the firm said California’s carbon credits should outperform global stocks this year as the board is expected to reduce the supply of available credits to meet the state’s emission reduction targets. The value of these credits is expected to rise as the supply drops.

In September, the G20 Task Force on Nature-Related Financial Disclosures released recommendations (similar to those put forward several years ago by the Task Force for Carbon-related Financial Disclosure) that provide guidance for how companies can look across their supply chains to assess their impact on nature, water, and biodiversity “and then start to understand what the nature-related risks are for their business,” Fitton says.

The recommendations will continue to spur already thriving biodiversity markets, which exist in more than 100 countries including the U.S. In the U.K., a new rule called “Biodiversity Net Gain” went into effect this month requiring developers to produce a 10% net gain in biodiversity for every project they create.

Though developers can plant trees on land they’ve developed for housing, for example, they also will likely need to buy biodiversity credits from an environmental nonprofit or wildlife trust to replace and add to the biodiversity that was lost, Fitton says.

This new compliance market for biodiversity offsets could reach about £300 million (US$382 million) in size, he says.

Finance Earth and Federated Hermes are currently raising funds for a U.K. Nature Impact Fund that is likely to invest in those offsets in addition to other nature-based solutions, including voluntary offset markets for biodiverse woodlands and for peatlands restoration.

The fund was seeded with £30 million from the U.K. Department for Environment, Food and Rural Affairs—money that is designed to absorb first losses, should that be needed. The government investment gives mainstream investors more security to step into a relatively new sector, Fitton says.

“We need the public sector and philanthropy to take a bit more downside risk,” he says. That way Finance Earth can tell mainstream investors “look, I know you haven’t invested in nature directly before, but we are pretty confident we’ve got commercial-level returns we can generate, and we’ve got this public sector [entity] who’s endorsing the fund and taking more risk,” Fitton says.

Since December 2022, when 188 government representatives attending the UN Biodiversity Conference in Montreal agreed to address biodiversity loss, restore ecosystems, and protect indigenous rights, several asset managers began “creating new strategies or refining strategies to be more nature or biodiversity focused,” Ma says.

He cautioned, however, that some asset managers are more authentic about it than others.

“Some have taken it seriously to hire scientists to do this properly and make sure that it’s not just a greenwashing or impact-washing exercise,” Ma says. “We’re starting to see some of those strategies come to market and, in terms of actual decisions and deployments, that’s why we think this year we’ll see a boost.”

Fitton has noticed, too, that institutional investors are hiring experts in natural capital, recognising that it’s a separate asset class that requires expertise.

“When that starts happening across the board then meaningful amounts of money will move,” he says. “There’s lots of projects there, there’s lots of things to invest in and there’ll be more and more projects to invest in as more of these markets become more and more mature.”

Love and Deceit: Work-From-Home Era Spawns ‘Pillow Talk’ Insider Trading

Steven Teixeira’s use of his girlfriend’s laptop began innocently enough when she asked him to keep an eye on her work email while she went to fitness classes and ran errands.

As they weathered the pandemic from their apartment in Queens, N.Y., he gave in to temptation. His sweetheart worked as an executive assistant at Morgan Stanley, and her calendar invites included meetings about planned mergers and acquisitions that involved the investment bank.

Teixeira, a compliance executive at a payment-processing company whom she intended to marry, used the information to trade in advance of the deals. It netted him thousands in profits, promises of Rolex watches from friends he tipped off, and the scrutiny of federal officials probing insider trading. He pleaded guilty to a dozen fraud charges in June.

There is a rich history in securities fraud of “pillow talk” cases, in which insider traders glean confidential information from romantic partners. The Covid era offered a twist: Secrets weren’t spilled in the bedroom or over a bottle of wine, but during the humdrum routine of two adults working from home.

“During Covid, there was an uptick in brazen conduct,” said Edward Imperatore, a defence lawyer at law firm Morrison & Foerster. “In a work-from-home environment, people acted with more impunity.”

Another recent case snared a boyfriend who was training to work for the Federal Bureau of Investigation. Seth Markin pleaded guilty in December to trading on information he purloined from his lawyer girlfriend, an associate in the Washington office of law firm Covington & Burling.

In 2021, she was working on a pharmaceutical acquisition from her one-bedroom apartment, where Markin spent days at a time. According to prosecutors, she trusted him because he told her he had a security clearance, was going to be an FBI agent, and wanted to marry her.

Prosecutors said Markin passed on tips that led to at least 20 people trading based on confidential information. “I knew that my behaviour was wrong,” Markin told the judge during his plea hearing. He is scheduled to be sentenced in March.

Representatives for the FBI and Covington declined to comment.

In Teixeira’s case, he was aided by a mouse-jiggler he bought that ensured his girlfriend’s laptop wouldn’t lock when she wasn’t using it, according to court documents. He has been cooperating with prosecutors and is scheduled to testify this year at the trial of his former friend, Jordan Meadow, who at the time was a stockbroker with Spartan Capital Securities. Meadow made more than $700,000 trading on Teixeira’s information and used the tips to advise clients who made millions, prosecutors allege.

“Yo you see UFS,” Meadow texted Teixeira, referencing the stock symbol of a company involved in a $3 billion deal, according to the indictment. He then asked for more nonpublic information, texting, “Feed me.”

Meadow has pleaded not guilty to the eight charges he is facing. Lawyers for Meadow and Spartan declined to comment, as did a spokeswoman for Morgan Stanley, and a lawyer for Teixeira didn’t respond to requests for comment.

In 2022, the Securities and Exchange Commission settled with a New Jersey man who it accused of illegally trading on inside information he heard when his domestic partner, who worked in marketing for an IT company, participated in calls from home, including an 11:30 p.m. videoconference in a home-office adjacent to their bedroom. Although he typically discussed his trades with her, in this case he hid them, executing the transactions from his work office, the SEC said. The man, who didn’t admit wrongdoing, paid $180,000.

One thing hasn’t changed since the earliest days of pillow talk: It is usually the men who can’t resist the urge to take advantage of their confidential information.

“Insider trading is an equal opportunity crime,” said Dixie Johnson, a partner at law firm King & Spalding who advises companies on how to avoid such situations. “But the cases we see usually have involved men doing the trading.”

Not that female romantic partners have always been innocent bystanders. In 2002, adult-movie actress Kathryn Gannon, known on screen as Marylin Star, pleaded guilty to trading on tips from an investment bank CEO with whom she was having an affair. She was sentenced to three months in prison.

A decade later, former beauty queen turned hedge-fund consultant Danielle Chiesi pleaded guilty to securities fraud for her role in a sprawling insider-trading ring. In a sentencing submission, she blamed a toxic relationship with her boss—and lover of 20 years—who urged her to get inside information.

One challenge for prosecutors is determining whether the partner who is privy to the information was in on the crime, said former federal prosecutor Brendan Quigley.

“Do they say, ‘Oh, my God, I would never give information to my spouse or significant other?’ It depends not only on what actually happened, but also on the nature of their relationship,” said Quigley, who prosecuted insider-trading cases in Manhattan.

For defense lawyers, pillow-talk cases can be difficult to handle at trial, particularly if one partner testifies against another. “To a juror, this is the bad boyfriend,” said Imperatore, the defense attorney. “He’s acting badly in a relationship in a way that goes beyond the four corners of insider trading.”

Not surprisingly, many such relationships don’t survive. Teixeira and his girlfriend split up, as did Markin and his.

Former Playboy CEO Christie Hefner and her husband, William Marovitz, divorced about a year after the SEC accused him of illegally trading Playboy stock based on information gleaned from his wife—despite her explicit instructions not to. Marovitz didn’t admit wrongdoing in a 2011 settlement.

One woman whose husband recently settled insider-trading charges involving confidential information related to her employer said coping with the allegations strengthened their bond.

“It felt like an injustice,” said the woman, who wasn’t identified in court papers. “It brought us closer together.”

I’m a Supercommuter. Here’s What It’s Really Like.

Sometimes I sleep in a different New York City hotel room every night.

On a recent Monday, it was a Midtown Manhattan Hampton Inn. The next night, a budget hotel downtown. Then I moved to a Hyatt in Queens, near John F. Kennedy International Airport, where I waited to check in behind a group of pilots and flight attendants.

The reason for this madness: My job is in New York, but my apartment is in Columbus, Ohio. When hotel prices are high, I property-surf to find a lower rate.

For more than a year, to the bafflement of family, friends and colleagues, I have attempted to live and work as a supercommuter. What began as a postpandemic experiment of flying to and from New York each week has turned into what I am hesitant to call a lifestyle.

Like many, I moved out of the city early in the pandemic, relocating near family in the Midwest. When it came time to return in 2022, I was underwhelmed at the housing options in my price range. I toured one-room studios facing brick walls and climbed crumbling staircases to reach dank apartments with ancient fixtures. I also had grown accustomed to midweek evening walks with my sister in Ohio, and a short drive to see my parents. I didn’t want to fully give that up.

Using back-of-the-envelope math, I thought I could keep my expenses—rent in Ohio, plus travel costs—at or below the price of a nice New York studio, or roughly $3,200 a month. The Wall Street Journal requires office attendance at least three days a week and, since I commute by choice, I pay all my travel expenses.

Luxury suites and room service

The challenge felt oddly thrilling. If anybody could find a way to subvert high New York real-estate costs, while remaining close to family, I thought it might be me. For years, I’ve been an on-call travel guru to friends and co-workers, coaching people on how to navigate flight cancellations and play the credit-card bonus games. I memorise aircraft configurations and spend hours reading mileage blogs and industry sites like Airliners.net.

Before mileage runs became useless, I obsessed over reaching top-tier airline status by spending as little as possible. (Family members still roll their eyes at the six hours I spent in Anchorage one December afternoon to requalify for Delta’s Diamond tier.) When a flight is oversold, I am quick to volunteer my seat in exchange for a voucher. (My best-ever haul: $2,000 after giving up my seat on multiple oversold flights one Saturday in San Francisco.)

Nerding out about this stuff has allowed me to travel farther and in more rarefied air than I could otherwise afford.

Entering my supercommuter era, I had visions of flying to New York on a weekday morning (8,500 points one way on American Airlines), spending the day meeting sources and filing stories, and retiring to one of my favourite points hotels—the Beekman. Mornings would begin with a free breakfast thanks to my Hyatt status, before a short subway ride to the office. After two nights, I’d return to Columbus and my roomy apartment, half the price of a Manhattan studio.

Shocking no one, that fantasy soon came crashing down.

Burning points on fancy hotel rooms was the first problem. The life of a journalist is hard to predict. I repeatedly found myself on deadline and having to rebook flights or stay an extra night, costing me money or miles.

Once I was back in the city, it also got harder to say no. Stay an extra night to attend a friend’s birthday party or meet a CEO in town just for the day? Sign me up. I didn’t want my living situation to strain relationships or interfere with my job, which I love.

To conserve hotel points, I swapped the Beekman’s elegant rooms in lower Manhattan for a Hyatt attached to a casino in Jamaica, Queens. My rooms overlooked a sea of empty parking spaces, but required half as many points as Manhattan alternatives.

Flight delays and blown budgets

By summer, with my miles dwindling and New York hotel rates rising, I reluctantly began to rely on the kindness of those around me. Hearing I might need a place, one friend mailed me the keys to her family’s unoccupied apartment in New Jersey. Another let me stay in her smartly designed Brooklyn one-bedroom for weeks as she traveled. A cherished deskmate, known for her tell-it-like-it-is demeanour, repeatedly offered a bedroom in her Chelsea loft, handing over the keys with a sometimes expletive-tinged reminder to: “Get a f—ing apartment.”

I watered plants, walked friends’ dogs and fed their cats while they were away. Still, working in a city without a permanent home took a toll. I came to dread the go-to question asked at parties and work events in New York: “So where do you live?”

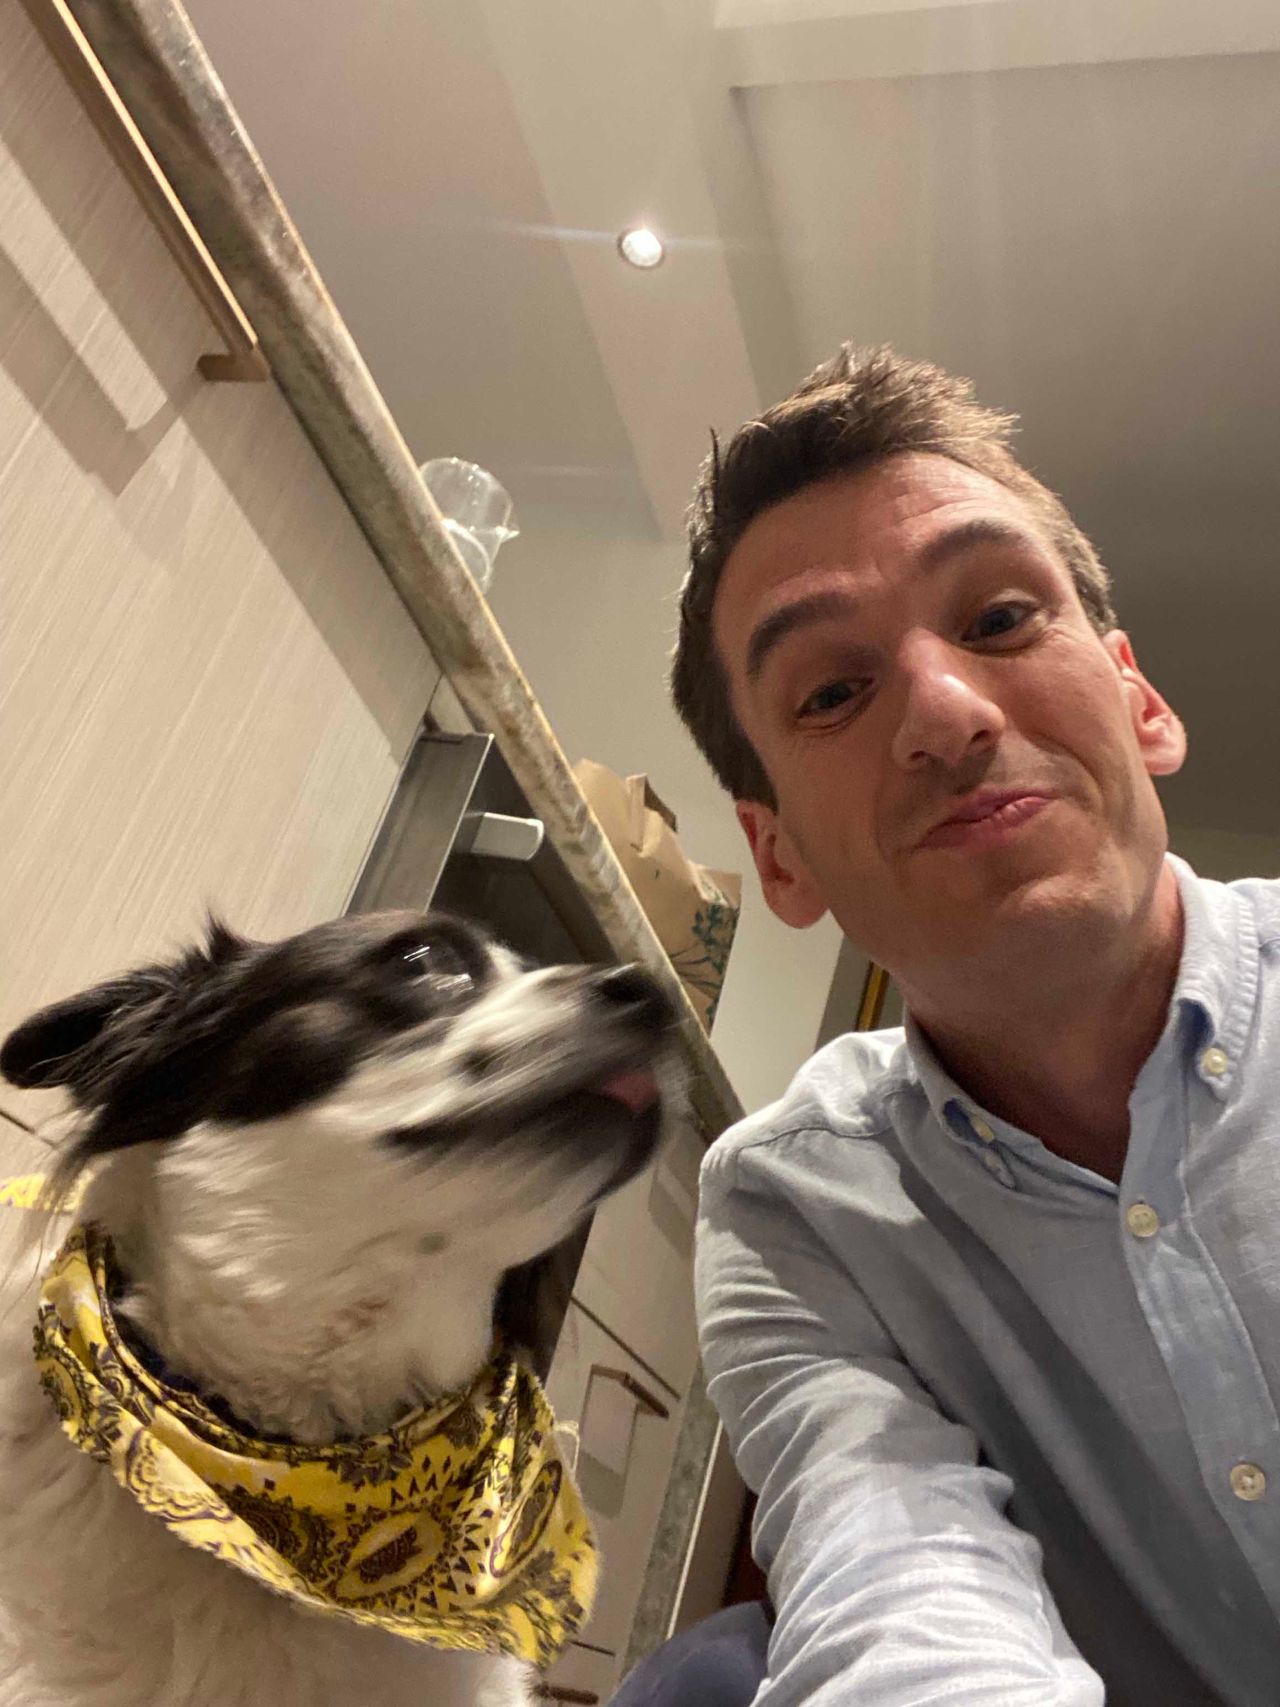
After house sitting for friends, I fell in love with some of their pets, including my friend Vanessa’s Border Collie mix, Ivy. But when in hotels without a refrigerator or stove, uninspiring meals abounded; a late-night dinner of yogurt and fruit.
CHIP CUTTER/THE WALL STREET JOURNAL

If I admitted, “it’s kind of complicated,” I got sucked into explaining my life as a supercommuter. Sometimes, I’d just tell people the location of that evening’s hotel. (Chelsea!)

Costs mounted in the fall, New York’s prime tourist and business-travel season. Friends teased me for embracing a life of chaos. They weren’t wrong. Without a refrigerator or stove, late-night dinners often consisted of yogurt and fruit purchased from a 24-hour CVS. Needing to pack light, I stored shoes under my desk and left spare outfits on an office coat rack.

To get to the office on time, I set my alarm in Columbus for 4:15 a.m. and hustled to the airport for 6 a.m. flights. When everything went according to plan, I made it door-to-door in three hours. If delays occurred, I scrambled to rebook on other flights.

My obsessive tracking of New York hotel prices taught me that dynamic pricing isn’t reserved for airlines. Hotel costs can fluctuate half a dozen times on the check-in date, so instead of booking in advance, I’d wait to pull the trigger until 10 p.m. some days after the rates fell.

In the end, the math didn’t work. I blew my budget by 15% and drained my miles balance. But I flew so much and stayed in so many hotels that I kept my elite status with Hyatt and American.

I still enjoy having one foot in the Midwest and one on the East Coast, though I’m not sure how long I can keep it up. I’m writing this from Columbus, where I overlook a beautiful park outside my picture window. My lease is up, but hotel rates in Manhattan this winter have plunged now that the holidays are over. Maybe that New York apartment search can be put off a little longer.

The Australian locations where homeowners are selling at a loss

Loss-making resales of homes and investment properties held for less than three years are on the rise, indicating more stress in the marketplace amid high interest rates and the cost-of-living crisis. CoreLogic data shows that of the 86,000 resales during the third quarter of 2023, 6.6 percent were sold at a loss after less than three years of ownership. This is up from 3.6 percent in the September quarter of 2022 and represents a 10-year high, according to CoreLogic’s head of research, Eliza Owen.

Properties held for three years or less represented one in five of all loss-making resales, according to the report. These types of sales were seen in many markets across the country. However, the areas recording the highest portion of these sales were Melbourne–Inner at 4.1 percent, Melbourne–West at 3.7 percent and Sydney’s Central Coast at 3.6 percent. The median loss for these resales was $30,000.

Most of the loss-making resales among properties held for less than three years were houses, at 64.8 percent. Ms Owen said this was quite a different trend to all loss-making resales across all tenure periods. On that broader basis, more of the overall loss-making resales were apartments at 70.9 percent.

It is a commonly held view among property experts that real estate must be held over the long term to achieve strong capital growth. This is partly because property prices typically move in cycles that can take several years to complete. Property is also an asset class that involves high entry and exit costs such as stamp duty, legal fees, marketing costs and agents’ commissions. This makes selling after only short periods of ownership undesirable, indicating that those who are choosing to do this are likely to be experiencing financial stress.

During the second half of 2023, thousands of mortgages rolled over from fixed periods of two or three years at interest rates below 2 percent or 3 percent to variable rates of above 5 percent or 6 percent. Some of these sales may reflect the ‘mortgage cliff’ effect of this change. Looking ahead, Ms Owen pointed out that the Reserve Bank of Australia is forecasting unemployment to rise to 4.2% by the end of 2024 and “this will test serviceability, and may lead to an increase in motivated selling for mortgagors with high debt levels and low savings buffers”.

Ms Owen also emphasises that short-term loss-making resales make up only a small portion of the Australian housing market and this was not expected to change. “This is ultimately a small share of mortgagors, so the portion of short–term resales is not expected to grow substantially from where it is now. Ongoing increases in home values nationally should contain the rate of loss-making short–term resales, though capital growth conditions were looking weaker across Sydney and Melbourne to the end of [2023],” she said.

The magic formula drawing residents back to the heart of Melbourne

People fled Melbourne’s inner suburbs as the pandemic lockdowns dragged on, but two years on, the allure of city fringe life, work and play is proving irresistible.

Convenience, low maintenance environments, less commuting, sustainability, and accessibility by public transport, cycling, or walking to work as well as access to study, food, culture, parks and health services are on the wishlist for people looking to live in the inner city.

For my stories like this, order your copy of  the summer 2024 issue of Kanebridge Quarterly magazine.

Melbourne’s inner city suburbs cling to the Hoddle Grid, the 1.6km by 0.8km area laid out to form the central activity area in early 1837 and is among the most desirable locale. Suburbs include Fitzroy, South Melbourne, Carlton, Collingwood, and Abbotsford. Richmond, East Melbourne and South Yarra are bordered by extensive parkland running from the Fitzroy Gardens, through to Yarra Park incorporating the MCG and across the Yarra River to the Domain Gardens. Belle Property partner Sam Fenna, specialising in premium city apartments, says there is an uplift in people who sold up during the pandemic, wanting to return.

A low maintenance lifestyle with easy access to parks and waterways are appealing to inner city residents in Melbourne. Image: Getty

“Some of them had coastal homes or in regional Daylesford and Trentham and we did see a peak of moves during the pandemic,” Fenna says. “A lot of them had boltholes in the city worth $2 million to $3 million and they sold up and went.

“They are starting to come back, saying they miss the action and want something back in the city.

“It’s places like Flinders Lane and all those little pockets of the city.”

Earlier this year, he inked a deal on a London townhouse inspired renovation for just under $2m to a country buyer looking for a city pad with a garage.

Sam Fenna from Belle Property says buyers have missed the vibrancy of the city.

Some of the more popular inner ring suburbs include Fitzroy and Carlton to the north of the city and Richmond and Cremorne to the east. Cremorne, formerly home to Bryant and May matches and Rosella sauce factories as well as the rag trade, has now been dubbed Silicon Yarra and is home to tech giants like Tesla, Seek among others. Employees want to live nearby.

Cremorne and Richmond, known as “Struggletown,” are close to the Melbourne Cricket Ground and Rod Laver Arena, beloved by many sports loving Melburnians.

One measure of popularity is the “walkability” of a suburb, allowing residents to perform daily tasks on foot. Walk Score rates inner suburbs like Carlton as a “walkers’ paradise” followed by Fitzroy, Fitzroy North, Melbourne, St Kilda, South Yarra, East Melbourne and South Melbourne. Victoria Walks, a health charity advising governments and business  on increasing walking participation, says the cost savings of living in a “walkable” community are overlooked.

“The ability to choose walking over driving to get to places is priceless,” Victoria Walks executive director Dr Ben Rossiter says.

“It’s better for your hip pocket, for your health and the environment. 

“Walking in your neighbourhood is important for building a sense of community connection.” 

The walkability of Melbourne’s inner suburbs is attractive to a wide range of buyers. Image: Getty

But not all inner suburbs are created equal, and he suggests anyone looking to buy or rent should spend time walking around the streets to see what they offer and what businesses, services and public spaces the area provides.

Rossiter says lockdowns highlighted the importance of having green space close to home.

“Inner Melbourne is blessed with parks and waterway walks,” he says. “But consider whether you will have to negotiate busy roads to access them. Noisy traffic and long crossing times can be a major disincentive to walk somewhere regularly.”

Also keep in mind that popular suburbs don’t necessarily have thriving shopping strips.

Fitzroys Real Estate 2023 Walk the Strip says the stretch between Lennox and Church streets on Richmond’s Bridge Road is the worst performer with vacancies at 15.5 percent, up from 11.7 percent last year. 

Yet, a few blocks away Gourmet Traveller Chef of the Year Thi Le runs two successful restaurants.

Davidson Property Advocates chief executive Tonya Davidson says the inner suburbs of Melbourne are a mixed bag and demand from buyers often depends on price point.

“What we are finding is an interest in high-end apartments. There are overseas people coming back into the market,” she says.

These include buyers with Foreign Investment Review Board approval as well as expats.

Davidson says while inner ring suburbs will always be popular, people are seeing value in the north, just past hip Carlton and Fitzroy to Brunswick and Coburg.

“East Melbourne will always be desirable due to position, transport and access to sporting facilities,” Davidson says. “It is popular with the business and medico demographics.” 

It has a median house price over the past year of $3,340,000 for houses and $750,000 for units, reflecting a mix of high-end properties and legacy of smaller units. She agrees that a walk score is important for some inner-city buyers. But that’s not the case for everyone.

Belle Property’s Fenna says while there is an uptake in car sharing, many of his buyers still want access to parking.

Many of these are “lock up and leave” residents who don’t want the big garden but still want to be able to hop in their own car, he says.

The Science-Backed Schedule for Your Perfect Weekend

WSJ’s Life & Work team presents Life Math, a series on how to optimise your time in 2024. Today: The best way to spend your time on the weekend.

Saturday and Sunday are often the most anticipated days of the week, yet optimising them remains an elusive goal for many of us.

Squandered weekends leave us feeling less happy and less motivated at work, research suggests. Those who put planning and intention into their weekends emerge on Monday feeling satisfied, accomplished and more productive throughout the workweek, says Elizabeth Grace Saunders, a time-management coach in Farmington Hills, Mich.

If we don’t plan our time well, we can end up marching through our obligations, or wasting time, without ever focusing on what we really want to do.

How to plan the perfect weekend? Behavioural researchers and time-management coaches suggest breaking it into six components: sleep, hobbies, socialising, exercise, work and chores, and unscheduled time.

Using recommendations from experts and federal guidelines, we came up with this equation. It’s important to remember these numbers aren’t hard and fast—stay flexible and make the math work for your life.

The perfect weekend equation:

Sleep (7 to 9 hours x 2 + ≤ 20 to 60 minutes napping) + Hobbies (~ 2 hours) + Socializing (0 to 2 events) + Exercise (≥ 45 minutes) + Work (≤ 2 hours) + Unplanned time (~ 3 to 4 hours) = A Great Weekend

Here’s how to incorporate those elements to build your best days off.

Sleep

This part of the “perfect weekend” equation is the most rigid.

Despite the tendency many of us have to take advantage of the time off by staying up and sleeping in later, we should try to keep our sleep schedules as consistent as possible to avoid social jet lag, sleep researchers say.

Sleep researchers generally permit one hour of wiggle room—so if you typically go to sleep at 11 p.m., try not to stay up past midnight. If your weekday alarm goes off at 7 a.m., rise and shine by 8 a.m. on the weekends. Finding yourself sleepy later in the day? Take a 10- to 30-minute nap in the early afternoon.

Most importantly: Make sure you’re getting the recommended seven to nine hours of sleep each night, even on weekends. If you’re among the roughly one-third of Americans who don’t get that recommended sleep during the week, you may be able to “catch up” by sleeping a few extra hours on the weekend, says David Reichenberger, who studies the links between sleep and health at Pennsylvania State University.

But don’t count on catching up forever. A recent study Reichenberger co-wrote found that among a small group of people who slept five hours a night during the week, their cardiovascular health measures worsened and didn’t return to baseline even after they were allowed to catch up on sleep over the weekend.

Hobbies

Having a hobby, or an activity we engage in during our time off for pleasure, has been linked to fewer symptoms of depression and higher levels of happiness, life satisfaction and even reduced risk of cardiovascular disease and cognitive decline.

Saunders, the time-management coach in Michigan, generally recommends people set aside roughly two hours for hobbies on the weekend.

Don’t worry if you’re not, say, a dedicated baker, painter or pianist. Hobbies can encompass much more than we might typically consider, says Daisy Fancourt, a professor of psychobiology and epidemiology at University College Londonwho researches the link between social and behavioral factors and health.

Something as simple as reading a book or cooking a tasty meal can serve the same purpose: to give us a sense of happiness, meaning and control in our lives outside of work.

Unplanned time

Scheduling unstructured time may sound silly. But failing to block out free time can leave us filling it with whatever’s right in front of us, like working or mindlessly scrolling, says Laura Vanderkam, an author and time-management expert based outside Philadelphia.

If you can, leave unplanned a chunky part of your Saturday or Sunday, roughly three to four hours, says Saunders. “If you make your weekend as packed and as busy as your weekday is, you will not come out of the weekend feeling refreshed,” she says.

This time is a good opportunity to let our brains enter so-called “default mode,” where our thinking extends beyond the here and now, allowing us to reflect and find meaning and purpose.

“It’s really important that all of us have dedicated, protected time in our lives to just be here now,” says Mary Helen Immordino-Yang, a developmental psychologist and neuroscientist at the University of Southern California.

Socializing

Robust social relationships are powerfully linked to physical and mental health and longevity benefits, and the weekend is a natural time to take advantage of them.

Social activities often require more advance planning than other parts of the weekend equation, so set aside time during the week to text or email friends and family about getting together, says Saunders, the time-management coach.

People typically spend twice as much time—nearly an hour—socialising on weekend days as on weekdays, according to the U.S. Bureau of Labor Statistics’s latest data on time use.

The amount of time you should spend socialising on the weekend depends on how energised or drained that togetherness makes you feel, she says. Introverts typically benefit from one social event every weekend or every other weekend, she says, whereas two social events per weekend is a sweet spot for extroverts.

If you have kids and most of your socialising naturally revolves around them, try to set some adults-only social time, too, says Vanderkam. You may find it easier to relax without your kids running around, and it can be easier to have uninterrupted grown-up conversations.

Work and chores

Pick a couple of small, achievable projects to see through to the finish line rather than trying to take on five things at once, says Vanderkam. You probably can’t clean out the entire garage, sort through your kid’s closet, vacuum out the car, wash all the laundry and grocery shop in one weekend.

Professional work, too, is sometimes inevitable on weekends. Avoid it if you can, but if a little work will help you feel less anxious, set some boundaries, behavioural researchers say. Stick to a clear time frame and goal, such as finalising one section of a report within a two-hour window.

Physical activity

Federal guidelines recommend at least 150 minutes of moderate-intensity aerobic exercise weekly, plus strengthening activities twice a week. If you’re spreading that out across the week, you may only need to set aside about 45 minutes for Saturday and Sunday.

But there’s good news for people who like to cram most of their exercise into the weekend. People who condensed their workouts into one or two days experienced health benefits similar to those who spread them out, a 2022 JAMA Internal Medicine study found.

The flexibility of the weekend allows for longer, varied workouts that can overlap with “hobbies” and “social” categories, says Heather Milton, a clinical exercise physiologist and supervisor of the NYU Langone Sports Performance Center. Try to incorporate both elements of aerobic and strength training, as well as some flexibility, she recommends.

It can help to plan an exercise block for the same time each weekend—such as a weekly Saturday morning yoga class or Sunday morning jog. Don’t have the time? Just try to move. Ideally, every 30 minutes or so, says Milton.

“Weekends are great for relaxation, but try not to Netflix and chill for 12 hours of the day without getting off the couch,” she says.

The Best Stock Funds of 2023

Large-cap companies led the way in 2023, benefiting the money managers who believed in them.

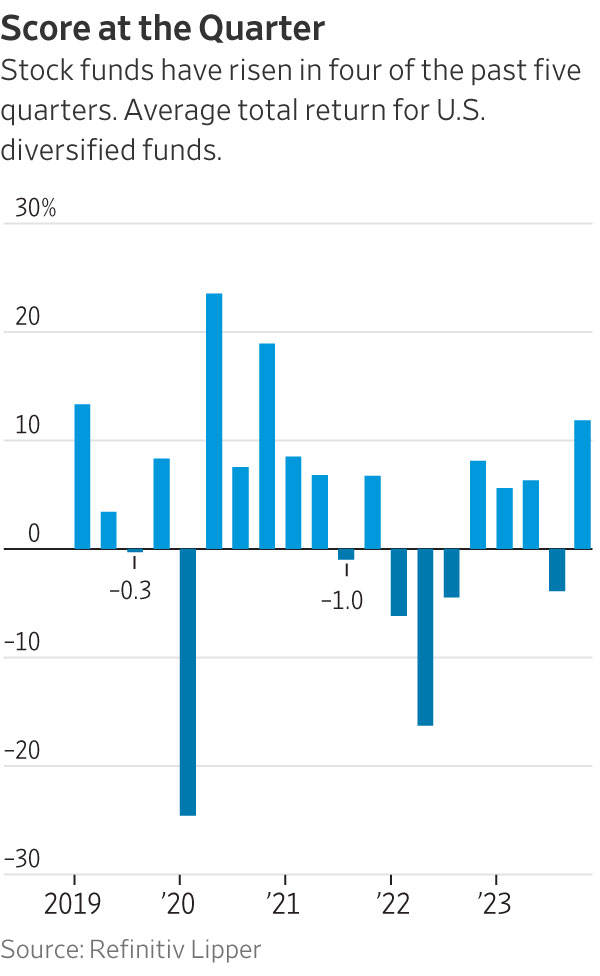
Driven by a rebound in large and megacap stocks, in particular the “Magnificent Seven” technology companies, mutual-fund managers who saw double-digit losses in the market rout in 2022 found themselves rewarded for their patience this past year.

Nine of the top 10 stock funds in The Wall Street Journal’s Winners’ Circle survey of mutual funds, which covers the 12-month period ended Dec. 31, are in Morningstar’s large-cap growth category—often with big weightings in outperforming sectors such as technology, communications services and consumer discretionary. Those S&P 500 sectors notched total returns, including dividends, of 57.8%, 55.8% 42.4%, respectively, easily topping the broader market’s 26.3% result.

Still, the Magnificent Seven paced the market. These stocks—Alphabet, Amazon.com, Apple, Meta Platforms, Microsoft, Nvidia and Tesla—all gained more than 48% last year.

Nvidia, whose chips have become synonymous with exploding interest in artificial intelligence, was the biggest winner among those stocks with a gain of 239%. It was followed by Facebook parent Meta at 194% and Tesla at 102%. These were popular holdings among the top-performing funds in the latest survey, though it varied by the individual manager.

Excluding those stocks, the S&P 500’s return was only 9.9%, according to S&P Dow Jones Indices. In other words, the Magnificent Seven accounted for more than half of the index’s 2023 performance and boosted the returns of many funds as well.

Still, there was plenty of good performance across mutual funds, and it wasn’t always contingent on those seven stocks. A rising tide lifts most boats.

Survey parameters

For the latest 12-month period, more than 1,000 of the 1,191 funds tracked in the Journal’s survey made double-digit gains. The average fund returned 19.7%, and only four funds registered declines.

To qualify for inclusion in the Winners’ Circle, funds must be actively managed U.S.-stock funds with more than $50 million in assets and a record of three years or more, as well as meet a handful of other criteria. The survey excludes index and sector funds, funds that employ leverage strategies and most quantitative funds. The results are calculated by Morningstar Direct.

As always, this quarterly competition isn’t designed to create a “buy list” of funds for readers, but to demonstrate the ways that specific investment strategies benefited from recent market trends. Some of the funds that were highlighted a year ago have fallen in the rankings just as growth portfolios have grabbed the limelight—and that phenomenon isn’t uncommon.

Moreover, not all funds cited in these quarterly surveys may be available to investors, and they may have elements that make them unsuitable for some investors, ranging from their fee structure to their longer-term performance or volatility.

Take the latest No. 1 fund, for example. The $500 million Virtus Zevenbergen Innovative Growth Stock Fund (SAGAX) lost 55.4% in 2022 and 10.1% in 2021 as tech stocks tumbled amid the Federal Reserve’s rate-hike campaign and recession worry.

The fund returned 65.2% last year, however, thanks to the big turnaround for the large-cap growth stocks.

Patience paid off

“Markets and management teams spent all of 2022 fearing and preparing for a recession that has so far failed to appear, but that excess pessimism really swung the pendulum too far in terms of market sentiment,” says Joe Dennison, a portfolio manager of the Virtus fund. “That has created some great opportunities for patient long-term investors.”

It holds five of the Magnificent Seven, three of which—Tesla, Nvidia and Amazon—are among its top 10 holdings. Tesla, its largest holding, stands at 7.7% of the fund.

These stocks aren’t new to Dennison and his co-managers. The fund first bought shares of Nvidia in 2017. Its holdings in Tesla and Amazon date to 2010 and 2008, respectively.

Dennison says the biggest contributors to the fund’s 2023 performance besides Tesla and Nvidia were MercadoLibre, an e-commerce company in Latin America, and Shopify, an e-commerce business platform. Those stocks gained 86% and 124% last year, respectively.

The Virtus fund doesn’t shy away from high valuations. As of Dec. 29, the trailing price-to-earnings ratio of stocks it holds was 70.4, excluding negative earnings. This approach, however, can be volatile.

Indeed, Dennison acknowledges “there will be volatility and periods of underperformance,” but he adds that it’s important to focus on longer-term performance and stick with companies that the managers believe in.

Best of the rest

No. 2 in the latest survey, with a return of 59.1%, is the $290 million Value Line Larger Companies Focused Fund (VALLX), which holds all of the Magnificent Seven. They were initially put into the fund before 2023—though it did add to Amazon, Google parent Alphabet, Microsoft and Tesla in the first nine months of last year.

It trimmed its positions in Apple and Meta over that stretch.

The fund’s manager, Cindy Starke, says that 2023 was all about “adding to names that we had more conviction in,” rather than trying to unearth new stocks.

Starke looks for companies she thinks can increase sales at a three-year annualised compound rate of 10% or more and annualised earnings growth of at least 15% for three to five years.

She points out that the fund had broad stock appreciation last year: 25 of the holdings gained at least 50% over the year’s first three quarters. (That fund and others release quarterly holdings with a lag after the quarter ends, but performance is updated daily.)

Besides the Magnificent Seven, the fund’s winners included Uber Technologies, which appreciated 149% in 2023. It was put in the portfolio in the fourth quarter of 2021 and was the fund’s largest holding, at 6.5%, as of Sept. 30. Starke increased her holding in 2023.

When she added Uber to the fund in 2021, she recalls, “I just thought it was very undervalued” and that “the growth model would mature.”

Other top holdings include Nvidia, initially put into the fund in 2018; Microsoft (2020); Alphabet (2011) and Tesla (2021).

Two other big gainers for that fund: Advanced Micro Devices, which leapt 127% last year, and cybersecurity firm CrowdStrike Holdings, which rose 143%.

At the same time, Starke did plenty of selling. She trimmed the fund to 39 names from 47 over the first three quarters of 2023, jettisoning stocks such as Goldman Sachs, Walt Disney, Bank of America, Estée Lauder and Devon Energy. “I just got out of the names that didn’t offer me the same kind of growth opportunity,” she says.

Rounding out the top four funds are the $500 million Baron Fifth Avenue Growth Fund (BFTHX), which returned 57.2%, and the $11 billion Fidelity Blue Chip Growth K6 Fund (FBCGX), up 55.6%.

An outlier

A party crasher at No. 5 is the Morgan Stanley Inception Portfolio (MSSGX)—the lone fund in the top 10 outside of the large-cap growth category.

It toils in small-cap issues, which lagged behind large-caps last year. The Russell 2000 index of small stocks returned 16.9% in 2023, trailing the S&P 500 by nearly 10 percentage points.

But the Inception portfolio punched well above its weight, notching a return of 54.4%.

The fund’s managers aren’t afraid to make outsize bets. As of Sept. 30, its information-technology weighting was 38%, compared with 21.4% for the Russell 2000 Growth Index—the fund’s benchmark.

One of its best holdings as of Sept. 30 was Affirm Holdings, which runs a buy now, pay later platform. The stock gained more than 400 % last year.

But that small-cap fund is an outlier in the Winners’ Circle. It is the only one outside of the large-cap growth category among the top 24 finishers in the survey.

At No. 6 is the $25 billion Harbor Capital Appreciation Fund (HACAX), returning 53.7%. As of Sept. 30, the Magnificent Seven accounted for six of its top 10 holdings.

The fund’s managers did make some hay in healthcare, an unloved S&P 500 sector that otherwise eked out a 2.1% return last year, including dividends.

One such healthcare winner it held is Eli Lilly. The pharmaceutical company’s stock returned 61%, helped by its strong position in a nascent class of drugs for weight loss.

“We’re trying to find companies that can generate above-average growth rates sustainably over an investment cycle,” says Blair Boyer, a co-manager of the fund.

Another healthcare company that fit the bill for the fund is Novo Nordisk. Its portfolio includes the Wegovy weight-loss drug. The stock was up more than 50% last year.

The fund unloaded its positions in Thermo Fisher Scientific, which sells testing equipment and measurement tools to laboratories, and life-sciences company Danaher. Thermo Fisher Scientific’s stock fell 4%, and Danaher dropped by 2%.

One of the fund’s biggest sector bets last year was consumer discretionary, representing 25% of the fund at the end of the third quarter, compared with a 16% representation in the Russell 1000 Growth Index.

Shares of vacation-rental company Airbnb, another of the fund’s holdings, surged by 59%.

Ultimately, while large-caps mutual funds enjoyed the Magnificent Seven-led rebound last year, it’s impossible to say how they will fare in 2024 given uncertainty about the economy and the path of the Fed’s monetary policy.

But despite fickle market sentiment, managers of top-performing funds say the key to their success is patience and staying true to their strategy even when things look bleak, as in 2022.

“It was about staying the course, having the conviction and adhering to our investment philosophy in good times and bad,” says Starke of the Value Line fund.

Property Investors Look Further Afield For Opportunities

More investors are looking beyond the neighbourhoods they live in for investment opportunities after the pandemic property boom saw regional markets surge in value at a greater pace than the capital cities, as more people who could work from home left the cities for greener pastures.

McGrath Estate Agents CEO John McGrath said this regional relocation of owner-occupiers opened investors’ eyes to markets outside their own neighbourhoods. Changes in marketing and technology brought about due to lockdowns, such as video inspections, online auctions and signing contracts electronically, helped buyers feel more comfortable with purchasing property remotely. “The prospect of phone bidding and purchasing properties sight unseen is no longer foreign,” he said.

Data from MCG Quantity Surveyors proves that investors are exploring new markets for investment. The latest data for 2023 shows the average distance between where landlords live and invest has ballooned to 1,502km, up from 857km in 2022 and 294km before the pandemic.

MCG managing director, Mike Mortlock, said the data revealed two insights. “Firstly, property investors remain agile and will park their capital in whichever investor-friendly national location and asset type offers the greatest possibility of maximising their return,” he said. “The second is that Western Australia has become the centre of Australian property investment. There’s little doubt its popularity with real estate buyers from the East Coast has increased the gap between home and investment.” MCG data shows 31.86% of Australian property investors bought in Western Australia in the first quarter of 2023, up from just 9.38% in the first quarter of 2022, revealing “a seismic shift away from east coast property investment”, he said.

In 2023, CoreLogic data shows Perth and Regional Western Australia delivered the best total returns (rents and capital growth combined) for investors of all capital cities and regional areas in Australia. Perth’s total return was 20.7 percent and regional Western Australia’s was 14.8 percent. The best-performing regions were Mandurah and Bunbury with 20 percent and 15 percent jumps in home values respectively over the year. Rents in Perth and Regional Western Australia also increased faster than any other area in Australia, up by 13.4 percent and 10.4 percent respectively.

One of the main attractions of Western Australia to East Coast investors is affordability. The Perth house price median is $691,100 and the regional house price median is $398,915. McGrath Estate Agents CEO John McGrath said: “This move towards remote investing has largely been driven by the perception of better capital growth prospects in the regions, and higher rental yields that usually come with more affordable properties.” Investors in regional areas can usually afford to buy houses, which typically deliver better capital growth than apartments, and they can buy with smaller loans, meaning they can manage rising interest rates more easily.

PropTrack recently put together a panel of industry experts and asked them to create a list of 100 suburbs that they think will outperform in 2024. PropTrack economist Anne Flaherty said 40 percent of the suburbs selected were in regional areas. PropTrak director of economic research Cameron Kusher said the selected regional areas were typically close to a capital city or had a diversified economy. “These tend to be key drivers in regional markets and reflect our expectations of the types of locations in regional areas likely to see the strongest price growth next year,” he said.

Here are some examples of the regional cities or suburbs tipped for outperformance in 2024.

NSW – Dubbo

Simon Pressley of Propertyology selects Dubbo. “Decades of official evidence supports Dubbo’s status as an extremely resilient and low risk option for property investors with a budget of up to $600,000,” Mr Pressley said.

VIC – Delacombe, Ballarat

Buyers’ agent Kate Hill from Adviseable says Delacombe is a fast-growing part of the Ballarat West Growth Area and offers strong capital growth potential and good yields. “Ballarat was recently identified by the ABS as the fastest growing inland city in Australia and, according to some forecasters, can expect more strong price growth,” she said.

QLD – Darling Heights, Toowoomba

Home to the University of Southern Queensland, Ms Hill says Darling Heights has a range of amenities and will benefit from Toowoomba’s involvement in the 2032 Olympics. “There is a massive program of infrastructure development underway, planning more than $13.1 billion of infrastructure and major projects, both private and public,” Ms Hill said.

SA – Victor Harbor

Mr Pressley says Victor Harbor is to Adelaide what the Sunshine Coast is to Brisbane. “It has one the highest rates of internal migration in the country. Very popular for the one in five Australians who now derive their income from home, and for retirees.”

WA – Mandurah

“Mandurah is the lifestyle capital of Western Australia because of everything it has to offer without the big price tag,” said Ray White Managing Director, Dan White. “When it comes to property, Mandurah offers something for everyone, from affordable options for first-home buyers to upmarket canal homes.”

TAS – Launceston

Mr Pressley says this regional city has a diverse economy and “one of the best lifestyle offerings in all of Australia”. “Over the last 20 years, the average annual capital growth rate for Launceston houses of 8.6 percent is far superior to Sydney and Melbourne. Rental yields are also superior.”

New Year’s Resolutions Financial Advisors Wish Clients Would Make

Every financial advisor knows the feeling of having their good advice ignored. Clients splurge when they shouldn’t, play it safe in retirement when they can afford to spend more, and just won’t update those darned beneficiary designations. But what if advisors could create New Year’s resolutions for their clients? Granted resolutions and follow-through are two different matters, but for this week’s Barron’s Advisor Big Q, we invited five advisors to create resolutions for their clients. Here’s how they responded.

Craig Robson, founding principal, managing director, Regent Peak Wealth Advisors

Create or pursue your own stretch goals. Those could be financial, personal, or relational. We always bucket aspirational goals in our clients’ plans, and I will periodically remind them and ask, “What is preventing you from pursuing those goals?” Another way to say it is, “If not now, when?” Examples could be building your dream home, starting a business, going for that C-suite job opportunity.

The second resolution is to take chances. Make yourself available for some new opportunities. For me, the pandemic was a huge reminder of this. We started our firm eight months before the pandemic started. In the summer of 2020, I decided to negotiate a five-year contract for brand-new office space. When everybody was leaving and parking lots were empty, we were going back in. We negotiated fantastic financial terms and got great new fresh office space in Atlanta. Obviously, think it through and be educated, but there’s nothing wrong with taking some chances.

Emily Millsap, manager, financial planning, Avantax Wealth Management

Take thetime to learn your generational wealth story. So many of our beliefs about money and financial behaviours are tied to what we’ve learned and observed from our family and our culture and our community. And we always try to make money about math and logic, but there’s a lot of emotion tied into why we make the financial decisions we do. Understanding how our current behaviours and beliefs are connected to the stories of those who came before us, and then passing those stories to the next generation, is such a powerful and healing thing.

There are a few books out there that I really like on this topic. Loaded: Money, Psychology, and How to Get Ahead without Leaving Your Values Behind touches on some of that. Anything by Dr. Brad Klontz; Mind over Money: Overcoming the Money Disorders That Threaten Our Financial Health is a great one. Those are good places to start, and then talking to your parents, grandparents, aunts, uncles, about what they remember, what they learned, how they felt about money.

If you really want to do a deep dive, you can build a genogram, which is like a family tree, but you outline levels of education and career and how ancestors behaved with money and what they thought about money. Another resolution is that anyone who carries anxiety about their financial future will seek out experts who can help calm their fears and make a plan.

Dane Burkholder, private wealth advisor, Ameriprise Financial

New Year’s resolution No. 1 is to update your financial plan. People spend so much time focusing on markets and investments and rates of return. But the beginning of the year is a really great time to step back and say, “What are my financial goals, and am I on track for those financial goals?” No. 2 is doing a 401(k) audit. That could be as simple as rebalancing the assets inside of the 401(k) or setting the account to automatically rebalance throughout the year. If you were fortunate enough to get a raise, increase your contributions.

Resolution No. 3 is looking at your emergency fund. We have a unique opportunity to get a positive return on cash, with money-market accounts and CDs at 5%. People who are sitting on large cash balances have a tremendous opportunity to keep money liquid and available, but earning some interest. No. 4 is managing emotions: There are going to be points where the market pulls back or potentially corrects, but sometimes the best strategy is to take no action. When you use emotion to create action, generally the result isn’t beneficial. If you have a house that’s worth $800,000 and you go on Zillow the next day and it’s worth $700,000, you’re not going to sell your house.

Andrew Crowell, vice chairman, wealth management, D.A. Davidson & Co

The markets moved upward dramatically last year, and it’s very likely that clients’ target allocations are different than their current allocations. Somebody who owned a little Nvidia at the beginning of the year now has 220% more in terms of market weighting. So it’s important to rebalance annually, because you may inadvertently be carrying more risk than you need to or want to.

And if Santa makes a list and checks it twice, we have to do the same with all of our beneficiaries on every retirement account, with our trust documents, and so forth. Things change, relationships change. People die, people divorce, people marry, and the list that may have been valid 12 months ago may not be valid today. So make an annual checkup appointment and look at all the beneficiaries listed on your company 401(k), the IRA rollover from your first job out of college and whatever else.

It’s always helpful to set a budget and prioritise what you are going to be saving for this year and create spending guardrails. Banks and brokerage firms will soon allow you to download spending summaries from the prior year; pie charts breaking out spending by category. It can be eye opening to see, “Wow, I know we ate out a lot, but that restaurant line is a lot bigger than I thought.”

Nicholas Yeomans, president, Yeomans Consulting Group

Start with getting organised. Folks say they have that desire, but when it comes to actually getting organised and lining up all their affairs, to put together their tax documents, their estate-planning documents, their portfolios, their 401(k)s and IRAs, everything’s everywhere. I work with a lot of people who are retired, and as you get older, things unfortunately happen, from incapacity to death. Often, there is one spouse left holding the bag, and now they’re hunting and pecking and trying to find out where everything was. They’re already in a state of emotional distress, and now you’ve compounded that distress. Organising is a gift to the spouse who might end up having to take care of you or make those final decisions after you’re gone.

My second resolution is to communicate with family. Younger generations are more proactive in communicating with their kids, but unfortunately, a lot of folks in that 60- to 85-year-old group tend to do a much poorer job. We’re talking about the organisation of your finances and who is in charge of what. Who’s your trustee, who’s your power of attorney, what are your wishes with your healthcare directive? Is everything in a lockbox in your office? And what were you thinking when you put your will together? Why did Sandy get more than Charlie? [Explanatory] letters are a great idea. However, it’s even more meaningful to bring everyone together every two or three years and give them an update as to what you’re doing and why you’re doing it.

Australians Say Home Ownership Means Happiness

Most Australians feel that home ownership is important for their overall happiness, providing not only a sense of financial security but also contributing to their emotional wellbeing. Those are the findings of a research report undertaken by the customer-owned Great Southern Bank.

The research contains insights from almost 2,000 Australians on how they’re feeling about their current living situation. It found homeowners are significantly happier with their homes than renters, and the more equity they have in their homes, the happier they feel. Happiness is highest for mortgage-free homeowners, with 57 percent saying they were ‘very happy’ compared to 45 percent of homeowners with a mortgage and 29 percent of long-term renters.

Megan Keleher, Chief Customer Officer at Great Southern Bank, said: “What this report illustrates is the strong link between home ownership and happiness – in fact 7 out of 10 Australians say home ownership is important to their overall happiness,” Ms Keleher said. “Just 5 percent – or one in 20 – say it is not at all important. And perhaps not surprisingly, happiness with our home increases as we get older, and as we move towards becoming mortgage-free.”

The report found that 51 percent of renters are feeling heavily burdened by their financial commitments compared to 36 percent of homeowners. About 84 percent of long-term renters say they are concerned about current cost-of-living pressures compared to 73 percent of homeowners. And 80 percent are worried about housing affordability compared to 62 percent of owners.

Ms Kelaher said 29 percent of renters and 18 percent of long-term renters were still feeling confident that they could achieve their home ownership dreams. One in two renters said they were hopeful of buying a home to live in within the next three years, however saving a deposit is the key barrier.

“Of course, we acknowledge that the homeownership journey can be difficult and one of the biggest challenges faced by first home buyers is saving a deposit,” said Ms Keleher. “For those buyers who are finding it difficult to save a deposit, there is support available from several government initiatives. For instance, the Federal Government Home Guarantee Scheme’s expanded eligibility criteria is helping more first-time buyers, as well as those who haven’t owned a home for many years.”

One in 10 respondents who had previously planned to buy a home are now holding off, saying they feel deterred by rising property prices (60 percent), the cost of living (60 percent) or rising interest rates (45 percent). New CoreLogic data shows the national home value rose by 8.1 percent in 2023. Meantime, interest rates have risen dramatically since May 2022 from an emergency low of 0.1 percent to 4.35 percent today.

The report also asked respondents how satisfied they were with various elements of their homes, such as style and location.

About 72 percent of baby boomers were happy with their home’s location compared to 61 percent of Gen Xers, 58 percent of millennials and 48 percent of Gen Zs. About 62 percent of baby boomers liked the internal look and feel of their homes versus 51 percent of Gen Xers and 48 percent of both millennials and Gen Zs.

It appears many Australians are living in homes that are too big or small for them, with the size of homes recording some of the lowest satisfaction scores. Just 65 percent of baby boomers are happy with the size of their homes compared to 48 percent of Gen Xers, 42 percent of millennials and 40 percent of Gen Zs.

China Is Pressing Women to Have More Babies. Many Are Saying No.

Chinese women have had it. Their response to Beijing’s demands for more children? No.

Fed up with government harassment and wary of the sacrifices of child-rearing, many young women are putting themselves ahead of what Beijing and their families want. Their refusal has set off a crisis for the Communist Party, which desperately needs more babies to rejuvenate China’s ageing population.

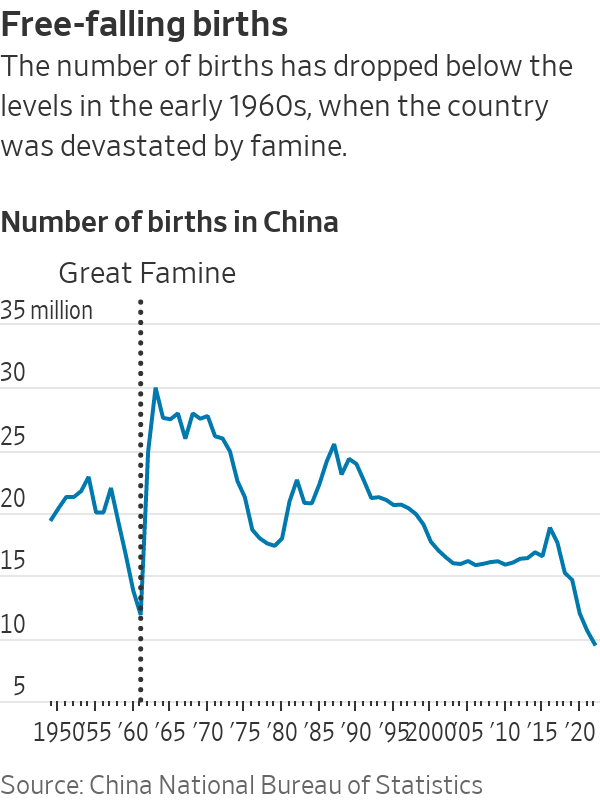
With the number of babies in free fall—fewer than 10 million were born in 2022, compared with around 16 million in 2012—China is headed toward a demographic collapse. China’s population, now around 1.4 billion, is likely to drop to just around half a billion by 2100, according to some projections. Women are taking the blame.

In October, Chinese Leader Xi Jinping urged the state-backed All-China Women’s Federation to “prevent and resolve risks in the women’s field,” according to an official account of the speech.

“It’s clear that he was not talking about risks faced by women but considering women as a major threat to social stability,” said Clyde Yicheng Wang, an assistant professor of politics at Washington and Lee University who studies Chinese government propaganda.

The State Council, China’s top government body, didn’t respond to questions about Beijing’s population policies.

Party lectures on “family values” are having little effect, even in rural parts of China.

Outside a mall in Quanjiao, a county in Anhui province, He Yanjing, a mother of two, said she has gotten several calls from community officials to encourage her to have a third child. She has no such plans. The preschool her son attended cut the number of classrooms in half because there aren’t enough children to fill them, she said.

Her friend, Feng Chenchen, the mother of a 3-year-old girl, said relatives are pressuring her to have more children, hoping she has a baby boy.

“Having had one child, I think I’ve done my duty,” Feng said. A second child, she said, would be too expensive. She said she tells relatives, “I can have another kid as long as you give me 300,000 yuan,” around $41,000.

Many young people in China, disheartened by a weak economy and high unemployment, seek alternatives to their parents’ lives. Many women view the prescribed formula of marriage and children as a raw deal.

Molly Chen, 28 years old, said the demands of caring for ageing relatives and her job as an exhibition designer in Shenzhen leave no room for kids or a husband. All she wants to do in her free moments is read or scroll through pet videos.

Chen followed the story of Su Min, a retiree who video-blogged about her solo road trip around China to escape a bad marriage. Chen said that the story, as well as online videos that women post about their lives, have deepened her impression that many men choose wives mostly as caretakers—for children, husbands and both sets of aging parents.

She lamented that she doesn’t have time even for a pet. “I can’t afford to take care of anything else outside of my parents and work,” Chen said.

Shrinkage

When Beijing said it would abolish its 35-year-old one-child policy in 2015, officials expected a baby boom. Instead, they got a baby bust.

New maternity wards were built only to close a few years later. Sales of baby-care products, including formula and diapers, have dropped. Businesses that focused on babies now target seniors.

New preschools built to make child-rearing more affordable struggle to fill classrooms and many have closed. In 2022, the number of preschools in China fell 2%, the first decline in 15 years.

Demographers and researchers predict that data will show Chinese births dipping below 9 million in 2023. The United Nations forecasts 23 million births in India, which in 2023 passed China as the world’s most populous country. The U.S. will have around 3.7 million babies born in 2023, the U.N. estimated.

The one-child policy brought much of China’s demographic gloom: There are fewer young people than in the past, including millions fewer women of childbearing age every year. Those women are increasingly reluctant to marry and have children, accelerating the population decline.

In China, 6.8 million couples registered marriages in 2022, compared with 13 million in 2013. The country’s total fertility rate in 2022—the average number of babies a woman has in her lifetime—is approaching one birth per woman, or 1.09. In 2020, it was 1.30, well below the 2.1 needed to keep a population stable.

The campaign for a “birth-friendly culture” has taken on the tone of an urgent national mission, with government-organised matchmaking events and a program encouraging military families to have more babies.

“Soldiers win battles. When it comes to giving birth to second or third children and implementing the national fertility policy, we are also taking the lead and charging to the front,” Zeng Jian, a top obstetrician-gynaecologist at a military hospital in Tianjin, told state media in 2022.

In August, residents of the western city of Xi’an said they received an automated greeting from a government number during the Qixi Festival, the Chinese equivalent of Valentine’s Day: “Wishing you sweet love and marriage at an appropriate age. Let’s extend the Chinese bloodline.”

The message drew a backlash on social media. “My mother-in-law doesn’t even push me to have a second child,” one person wrote. “I guess next, arranged marriages will come back,” another commented.

Beijing leans more to encouragement than the kind of coercion that marked the one-child policy. Local governments offer cash incentives for couples having a second or third child. A county in Zhejiang province gives a $137 cash bonus to every couple getting married before age 25.

In 2021, the city of Luanzhou asked unmarried people to sign up for a government-sponsored dating initiative that uses big data to find matches citywide. A district in the city of Handan provides a one-stop wedding-planning service.

Hide and seek

The shift means some women have gone from trying to dodge punishment for having too many children to being hounded to have more.

A decade ago, a woman surnamed Zhang was in a cat-and-mouse game with authorities after she decided to have a second child. She asked that her first name not be used.

While pregnant, she left her job to stay out of public view, fearful officials would pressure her to have an abortion, she said. After giving birth, in 2014, she stayed with relatives for a year. When she returned home, local family-planning officials fined her and her husband around $10,000. She said she was forced to have an intrauterine device implanted to prevent pregnancy. Authorities required her to have it checked every three months.

Months later, the Chinese government announced the one-child policy would be scrapped. For a while, authorities still demanded Zhang have her IUD checked.

She now gets text messages from officials encouraging her to have more children. She deletes them in anger. “I wish they would stop tossing us around,” she said, “and leave us ordinary people alone.”

There has been a tightening of licenses for clinics offering medical procedures to block pregnancies. In 1991, the height of the one-child policy, 6 million tubal ligations and 2 million vasectomies were performed. In 2020, there were 190,000 tubal ligations and 2,600 vasectomies.

On social media, people complain that getting a vasectomy appointment is as difficult as winning the lottery.

Officials have also tried to dial back abortions, a key tool for officials during the one-child policy. They have fallen by more than a third—from more than 14 million in 1991 to just under 9 million in 2020. China has since stopped releasing data on vasectomies, tubal ligations and abortions.

Pressurised populace

Wang Feng, a sociology professor at the University of California, Irvine, said there have been two conflicting shifts in Chinese society: a rising awareness of women’s rights and increasingly patriarchal policies.

For the first time in a quarter-century, no women are among the top two dozen officials on the Politburo. Since Xi took power in 2012, China has fallen 38 places in the World Economic Forum’s Global Gender Gap Report to No. 107 in the 2023 ranking of 146 nations.

In the Mao era, the party promised to end Confucian traditions that discriminated against women. Xi has instead stressed Confucian values, including the filial duty to have children. Families also pressure women into traditional roles.

Sophy Ouyang, 40, has known since middle school she didn’t want to marry and have children. Ouyang studied computer science, one of the few women in her village to pursue advanced schooling, and works as a software engineer in Canada.

Ouyang said that throughout her 20s, her family leaned on her to marry. Her mother said that if she had known Ouyang wouldn’t have children, she would have stopped her from getting a higher education.

Ouyang cut off contact with her family more than a decade ago. She has blocked her parents, aunts and uncles on social-media apps. “If I’m a bit more gentle with them,” she said, “they will take advantage.”

The Chinese government, which sees feminism as a nefarious ideology backed by foreign forces, has detained women’s-rights activists and erased their social-media accounts in a years long crackdown.

Even so, women have become more vocal online about their experiences relating to relationships, families and work. Their posts show a personal form of feminism that is harder for authorities to police.

Simona Dai, 31, started a podcast entitled “Oh! Mama” about birth and marriage after she learned that her mother had an abortion when she was eight-and-a-half months pregnant with a girl in the early 1990s.

Dai got married when she was 26 and said she had to endure her husband’s chauvinistic views, especially during the pandemic, when they argued about household chores. She became adamant about not having children, despite pressure from the couple’s families.

She has since applied to end her marriage. “If I didn’t divorce, I might have to have a baby,” she said.

A national debate over the treatment of women erupted in early 2022, when the video of a woman—a mother of eight, kept in a shed with a chain around her neck—sparked a social-media storm. The woman’s plight resonated with Chinese women who saw a connection to their own roles.

In recent years, Beijing has raised its guard against similar instances of social-media outrage.

A woman who worked at a branch of the All-China Women’s Federation in Guangzhou from 2020 to 2021 said the branch focused on preventing gender-related topics from going viral. She said it paid more to a tech company to police social-media comments than its budget for women’s advocacy.

During training, she said, employees were warned of serious repercussions if women’s issues in Guangzhou drew unwanted social-media attention. The women’s federation didn’t respond to requests for comment.

China’s cyberspace watchdog, which polices material seen as harmful to Chinese internet users, said in December that it was targeting content “spreading wrong views on marriage.”

Some women who decided years ago against marriage and children consider themselves lucky.

Ouyang, the software engineer in Canada, said, “I feel like I’ve completely dodged a bullet.”

—Jonathan Cheng and Grace Zhu contributed to this article.

The Formula to Get More Time Off Using Your Vacation Days

It is barely past New Year’s Day. If you’ve taken the day off, congratulations: You have aced your first test of vacation-day math.

We get only so many days of paid time off a year. And that is if you’re lucky—one in five U.S. private-sector workers gets no PTO, according to the Bureau of Labor Statistics. Without a strategy, you can have a generous number of vacation days and still feel like you never truly got away from it all.

Think of the times you took a mini-break from work only to feel stressed before and afterward. The average American worker with five years at the company gets 15 paid days of vacation in a year, BLS data show. That leaves little room for bad planning if you want a serious break or two, plus some long weekends and the occasional personal day.

Maxim No. 1: A vacation day equals more than a day of vacation when you attach it to a public holiday or two. Taking the day after New Year’s this year snags you a four-day weekend at the start of 2024. Timed just right between federal holidays and weekends, 15 days of PTO can turn into nearly 50 days of extended break time this year. (That is, if your co-workers don’t beat you to claiming those dates.)

Another guiding principle—Fridays off are overrated, and not just because they are peak traveling days. For a long weekend or a random personal day, there is evidence to suggest a Monday and Wednesday can be more satisfying. But more on that later.

A weeklong vacation vs. long weekends

First, some science: To really recharge, you need at least one weeklong vacation, bracketed between two weekends, research suggests.

In one study of more than 50 people who took vacations for an average two weeks, participants’ well-being levels didn’t peak until their eighth day off. A 2023 study of more than 300 vacationers found people who took between eight and 14 days off reported greater and longer positive effects once they returned to work, such as better sleep, than those who took shorter breaks.

One to two weeks off, in fact, appeared to have longer-lasting benefits than lengthier vacations. After a while, “you creep back to old habits,” says Ty Ferguson, a research associate at the University of South Australia in Adelaide who co-wrote the study. His own recent getaway—several days down the coast—went bust when his three children, ages five and under, came down with a bug. Then it was time to return.

“I should take more of my own advice,” he says.

One reason taking a week-plus vacation is important is that is enough time to actually reduce workloads. Network-equipment giant Cisco recently conducted a deep data dive on employees’ work habits and well-being, examining more than three years’ of metrics such as virtual meetings, badge-ins, PTO and engagement surveys. When workers took a day or two off, the number of meetings they had in the month didn’t change much—they just packed in more work before and after their time off.

Meeting loads dropped sharply for workers who took at least five consecutive days off. The fewer the meetings, the greater tendency to report healthier routines and better stress-coping abilities, Cisco found.

“I always believed in the long weekend because it can be so hard to take a week off,” says Cisco’s chief people officer, Kelly Jones. “I was wrong.”

Maximising public holidays

To get the most out of your finite days off, consider Gail Martino’s PTO hack for 2024. “I’m a leisure laggard,” says the senior project manager in New Haven, Conn., of her habit of waiting to take vacation time until things get slower. (Hint: That is never.) Then there is a scramble to use it or lose it toward the end of the year, with the days she does take off feeling not terribly satisfying.

“You wonder, why am I so tired?” she says.

In recent years, she’s become a bird watcher and wants to take a couple of birding trips along the Eastern Seaboard in 2024. “I spend a week in the woods, among trees and nature, and that is an incredible break,” she says. “Now I want to chart out the entire year.”

Scanning the 2024 calendar, she devised a spreadsheet of dates bridging public holidays and weekends with a theoretical 15 vacation days and four personal days. (Working at Unilever for 18 years, she got about a week more PTO than that in 2023.) The result was 50 days of extended breaks, including 9-day stretches in July and over Christmas:

A little tweaking can wring nearly the same number of extended break days with just 15 vacation days and no personal days—that is, if you get a full slate of federal holidays off and don’t have to trade off with co-workers:

The case for Mondays and Wednesdays off

Want to take a three-day weekend that isn’t attached to a federal holiday? Take Monday off instead of Friday, suggests Jim Burch, a 38-year-old software engineer in Phoenix and an avid hiker. Taking Fridays off often results in cramming five days of work into four, he points out.

“I’d get so stressed out on the Thursday before,” says Burch, who at his current job, has more autonomy over his schedule than in earlier jobs.

Delaying gratification until Monday means your co-workers have no choice but to start the workweek without you. Back Tuesday, you can quickly catch up on whatever emails or developments you missed, he says.

Then there is the unexpected pleasure of a Wednesday off. “It is like a midweek weekend,” says Rachel Blenkhorn, a social-media production manager for a real-estate investment trust who lives in Warren, Mich. It is long enough to relax or take care of appointments yet short enough to get back in the work groove on Thursday, she says.

There is science as to why, says Dawna Ballard, a professor at the University of Texas at Austin and an expert in chronemics, the study of time as it relates to communication.

“Everyone has a different chronotype,” or their own biologically driven pace, she says. A break after two days’ work gives you a second chance in the week to return to your internal rhythm. Psychologically, it also creates a bit of “slack” in the workweek, alleviating the stress that comes from feeling like there is too little time to get everything done.

However you plot your vacation days in 2024, don’t leave any on the table. They aren’t just good for you, there is evidence they are good for your career.

An Ernst & Young study of its employees showed every extra 10 hours of vacation was linked to an 8% improvement in year-end performance reviews. Another study found people who took more than 10 vacation days a year were more likely to get a raise or bonus than those who took fewer days.

Now that is a formula anyone can get behind.

Where property prices are rebounding around the country

Australian home prices rebounded strongly in 2023, new figures released today have shown.

The Home Value Index from property data provider CoreLogic revealed prices surged by 8.1 percent last year after falling -4.9 percent in 2022. However, recorded growth is nothing like the rises in 2021, which saw home prices swell by 24.5 percent.

CoreLogic research director Tim Lawless said while the greatest increases were seen at the start of 2023, consistent interest rate rises announced by the RBA put a dampener on growth as the year progressed, with just a 0.4 percent increase in December.

“This was the smallest gain in our national monthly HVI since values started rising in February,” Mr Lawless said. “After monthly growth in home values peaked in May at 1.3 percent, a rate hike in June and another in November, along with persistent cost of living pressures, worsening affordability challenges, rising advertised stock levels and low consumer sentiment, have progressively taken some heat out of the market through the second half of the year.”

While regional areas saw record price rises during COVID, it is now the Australian capitals leading increases in home values, Mr Lawless said.

“Stronger conditions across capital city markets is a reversal of the early COVID trend which saw regional markets experience higher demand amid strong internal migration,” he said.  “Regional migration trends have mostly normalised through 2023, and the significant capital gains recorded through 2020 to 2022 has meant many regional markets have become less affordable.”

However, growth across capital cities is uneven, with Perth recording the highest annual increases at 15.2 percent, followed by Brisbane on 13.1 percent and Sydney on 11.1 percent. The results were followed by Adelaide (8.8 percent), Melbourne (3.5 percent) and Canberra (0.5 percent). Darwin and Hobart values declined over the past 12 months, down -0.1 percent and -0.8 percent respectively.

In Perth, the top performing suburb was Armadale, up 25.2 percent, followed by Gosnells, 22.6 percent.

In Brisbane, home values in the suburb of Nathan are up 22 percent on last year, followed by Mt Gravatt, up 21.1 percent.

For the Sydney market, Blacktown lead the way, with a 15.8 percent increase in home values, followed by the inner west suburbs  of Marrickville – Sydenham – Petersham, which increased by 15.3 percent.

Rank

SA3 Name 

SA4 Name 

Median Value

Annual change 

Greater Sydney

1

Blacktown

Sydney -Blacktown

$969,287

15.8%

2

Marrickville -Sydenham -Petersham

Sydney -City and Inner South

$1,741,931

15.3%

3

Hornsby

Sydney -North Sydney and Hornsby

$1,485,422

15.3%

4

Strathfield -Burwood -Ashfield

Sydney -Inner West

$917,641

14.9%

5

Eastern Suburbs -North

Sydney -Eastern Suburbs

$1,988,175

14.6%

6

Warringah

Sydney -Northern Beaches

$2,068,585

14.5%

7

Canterbury

Sydney -Inner South West

$1,085,111

14.3%

8

Mount Druitt

Sydney -Blacktown

$812,868

14.1%

9

Merrylands -Guildford

Sydney -Parramatta

$1,060,399

14.1%

10

Leichhardt

Sydney -Inner West

$2,007,850

14.0%

Greater Melbourne

1

Darebin -North

Melbourne -North East

$762,619

7.9%

2

Banyule

Melbourne -North East

$935,214

7.7%

3

Monash

Melbourne -South East

$1,223,086

7.6%

4

Knox

Melbourne -Outer East

$910,533

7.5%

5

Manningham -West

Melbourne -Inner East

$1,388,013

7.1%

6

Manningham -East

Melbourne -Outer East

$1,539,018

6.9%

7

Whitehorse -West

Melbourne -Inner East

$1,213,085

6.7%

8

Whitehorse -East

Melbourne -Outer East

$1,185,513

6.1%

9

Casey -North

Melbourne -South East

$808,703

5.3%

10

Casey -South

Melbourne -South East

$758,745

5.1%

Greater Brisbane

1

Nathan

Brisbane -South

$1,079,497

22.0%

2

Mt Gravatt

Brisbane -South

$1,117,075

21.2%

3

Sunnybank

Brisbane -South

$1,026,758

19.4%

4

Carindale

Brisbane -South

$1,212,544

19.1%

5

Holland Park -Yeronga

Brisbane -South

$756,166

18.8%

6

Springwood -Kingston

Logan -Beaudesert

$638,552

17.1%

7

Chermside

Brisbane -North

$945,095

16.7%

8

Rocklea -Acacia Ridge

Brisbane -South

$935,200

16.2%

9

Nundah

Brisbane -North

$794,173

15.7%

10

Forest Lake -Oxley

Ipswich

$665,472

15.4%

Greater Adelaide 

1

Playford

Adelaide -North

$474,782

14.3%

2

Gawler -Two Wells

Adelaide -North

$590,250

13.7%

3

Salisbury

Adelaide -North

$582,159

13.2%

4

Tea Tree Gully

Adelaide -North

$700,396

11.5%

5

Port Adelaide -West

Adelaide -West

$691,116

11.0%

6

Onkaparinga

Adelaide -South

$663,042

9.9%

7

Port Adelaide -East

Adelaide -North

$737,926

8.5%

8

Marion

Adelaide -South

$797,606

8.3%

9

Campbelltown

Adelaide -Central and Hills

$859,213

8.2%

10

Burnside

Adelaide -Central and Hills

$1,416,110

8.2%

Top 10 capital cities SA3s with the highest 12-month value growth – Dwellings. Source: CoreLogic

Greening the property market: why more vendors advertised sustainable features in 2023

Just under 15 percent of homes for sale in FY23 were ‘green listings’, new research reveals.

Green listings, which are defined as having at least one environmentally-friendly feature providing energy or water savings, such as solar panels, a home battery and rainwater tanks made up 101,479 of the 687,874 homes that went onto the market in FY23, Australia’s largest real estate network, Ray White, reports.

Queensland had the highest proportion of green listings overall in FY23 at 20.3 percent. This compares to 19.6 percent in the Northern Territory, 19.5 percent in South Australia, 16.1 percent in the ACT, 15.7 percent in Western Australia, 11.6 percent in Tasmania and 11.4 percent in both New South Wales and Victoria. The number of green listings advertised has been growing over the past three years as homeowners think more about their carbon footprint and embrace sustainability. The number of listings with one or two green features has risen from 17.2 percent of listings in 2020 to 19.5 percent in 2023, according to Ray White.

Skyrocketing electricity prices and the availability of government incentives to encourage homeowners to invest in eco-friendly features are no doubt contributing to higher interest in green homes. A growing uptake of electric vehicles (EVs) is also leading to more homeowners installing EV chargers in their garages. The Electric Vehicles Council of Australia reports that the number of sales of EVs in the first half of 2023 exceeded the total number sold in 2022.

Buyers’ interest in green features is prompting more agents to include such details in the advertising copy for homes for sale, said Ray White data analyst, William Clark. “Over the last three years, there has been an increasing proportion of listings with ‘solar panels’, ‘battery’ or ‘off-grid’ appearing in advertising copy,” he said. “This is not an exhaustive list of ways a house can be green, however solar panels were the most frequently advertised, while batteries and being off-grid make a house green to the greatest degree.”

In New South Wales and Victoria, the suburbs with the highest percentage of green listings were all in regional areas. In other states and territories, there was a broader mix across regional and capital city suburbs. Clark said green properties were more commonly houses on large blocks of land. “With regional areas having a higher proportion of houses rather than units, single-family dwellings may retrofit green features such as solar panels and battery packs quicker and more autonomously than units and complexes with large strata groups. This means states, cities and suburbs with more houses and fewer units will see a higher proportion of green listings.”

Here are the suburbs with the highest percentage of green listings advertised in FY23.

Top suburbs for green listings

1. Mount Mee, Moreton Bay region of QLD, 92.3%
2. Battery Point, Hobart, TAS, 90.9%
3. Riverbend, Logan City, QLD, 85.7%
4. Sandy Creek, Somerset region of QLD, 85.7%
5. Eerwah Vale, Sunshine Coast of QLD, 84.6%
6. Jiggi, Northern Rivers region of NSW, 84.6%
7. Wamboin, Southern Tablelands of NSW, 84%
8. Wallalong, Port Stephens in NSW, 81.3%
9. Echunga, Adelaide Hills, SA, 76.9%
10. Gnangara, Perth, WA, 76.5%

Source: Ray White, suburbs with at least 10 listings advertised in FY23

The greening of Australian homes is being helped along by regulation, with a new law in Victoria banning gas connections in newly built properties coming into effect yesterday. The ACT was the first state or territory to introduce such a law, which came into effect there in December.

Tech That Will Change Your Life in 2024

It’s been a crazy year in tech:

• Artificial intelligence infiltrated everything.

• Elon Musk and Mark Zuckerberg agreed to a cage fight (which never happened).

• High-schoolers made pornographic clones of their classmates.

• A high-profile tech CEO was fired and rehired over a weekend.

• Oh, and Apple unveiled its least-mainstream product since the G4 Cube.

We could go on, but we’re here to look forward. That’s the best part about this annual exercise, where we all pile into an electric time-travel vehicle and set the Google Maps destination to The Future.

So what can we predict for 2024? AI as far as the…A-eye can see. We won’t even pretend to know all the things generative AI will do to our devices, our jobs, our lives—and our elections. But we promise you won’t be able to escape it. We’ll see other things too: the decline of the dreaded password, a boom in cleaner energy, increasing regulation around kids on social media, and more.

And yes, Apple will start selling a $3,500 face computer that aims to change how we see the world, or at least our living rooms.

Here are our predictions for the coming year in tech.

Is it real?

When photos of a bull walking on train tracks in New Jersey recently went viral, many people’s first thought was, “Did AI make this?” No, the photo was the real deal. (Don’t worry, the bull is safe now.)

This is the internet challenge of 2024: How do we tell the real from the AI? The generative-AI product flood will continue, but also expect more tools to help us pinpoint artificially generated text, photos, video and audio.

OpenAI, specifically, has promised a feature that will identify whether an image is created by its Dall-E 3 image generator. TikTok has said it is working on ways to detect and automatically label AI-generated content.

The Adobe-led Content Authenticity Initiative, which provides technology to embed information about the origin of an image or video into the file, will also continue to gain steam. Microsoft has said it will launch a tool for political candidates and campaigns that allows them to add credentials to media so people will know how it was created or edited. Camera maker Leica recently announced a new camera that automatically embeds such credentials in its photos.

At some point, we might just regard content without credentials as suspicious.

EVs struggle to accelerate

If you’re expecting 2024 to be the Year of the EV Boom, think again. “It’s not that EV sales are down, it’s that the pace of growth is slowing down,” said Barclays analyst Dan Levy.

That deceleration looks to continue but it marks a turning point: More mainstream car buyers are now catching their breath and beginning to assess their EV options. Two of the biggest consumer pain points—price and charging—will start to improve. Especially for people looking beyond Tesla.

Sometime in 2024, Ford, General Motors, Rivian and others will be able to charge at many of Tesla’s charging sites. That should significantly increase the number of places EV drivers can stop to charge on a long road trip. Additionally, we’ll see the launch of more fast-charging stations funded through the Biden administration’s National Electric Vehicle Infrastructure program. Here’s hoping they work—and actually accept credit cards.

Starting Jan. 1, if you’re buying an EV that’s eligible for a federal tax credit you can get that discount at the point of sale. You will no longer have to wait until you file your taxes. The bad news: Fewer EVs will qualify for the credit. But at least there are some sub-$40,000 EVs on the way, including the Chevy Equinox EV and Volvo EX30.

The clean-tech boom begins

Electric vehicles may seem like the embodiment of so-called “clean tech”—driven in no small part by a certain eccentric billionaire and his car company. But the EV supply chain is enabling hardware companies of all kinds to make use of really big batteries, and the critical “power electronics” that go with them.

For example, in Vermont, the biggest regional utility is turning batteries into a distributed energy-storage network it calls a “virtual power plant.” In-home batteries can recharge from the grid when energy is plentiful, and put it back into the grid when demand shoots up or there are outages, increasing reliability and saving customers money. Even electric vehicles can help in a similar way: Ford says its electric F-150 can power your home in a blackout.

And the relentless rollout of new sources of low-carbon and renewable energy is proceeding apace, including offshore wind, rooftop solar and geothermal power from the earth’s own heat. Startups—backed by big money—are looking to develop a generation of smaller, safer modular nuclear reactors, too.

AI + PC = ?

In 2024, every major manufacturer is aiming to give you access to AI on your devices, quickly and easily, even when they’re not connected to the internet, which current technology requires. Welcome to the age of the AI PC. (And, yes, the AI Mac.)

What’s coming is what engineers call “on-device AI.” Like our smartphones, our laptops will gain the ability to do the specialised computing required to perform AI-boosted tasks without connecting to the cloud. They will be able to understand our speech, search and summarise information, even generate images and text, all without the slow and costly round trip to a tech company’s server.

On Dec. 14, Intel announced its entrants into this race, chips with built-in neural-processing units. Qualcomm announced similar chips in late October. Both silicon giants will compete to power Windows laptops and Chromebooks. Look for more announcements of chips to enable on-device AI, possibly from Nvidia and AMD. Apple—which brought variations of its neural-engine-equipped mobile chips to laptops and desktops in 2020—will be making that specialised processing power available to software developers in new ways.

The hardware will show up before the compelling software applications do, but we’ve already seen some promising demos—like fast AI-powered photo-editing tools.

Longer life for older gadgets

Unlike milk and bread, there’s no expiration date printed on our gadgets’ packaging. That doesn’t mean they don’t have them. Modern, internet-connected devices remain tied to their makers after we buy them. And when the makers stop providing services and software updates, they die.

A growing number of manufacturers and brands are extending software support, however. Apple—which updates iPhones for about six years, and Macs for six to eight years depending on the model—was the gold standard, but it has fallen a bit behind Alphabet’s Google. For its new Pixel 8 phones, Google upped support to seven years. The company also said it will provide updates to Chromebooks for up to a decade starting in 2024.

Samsung previously updated phones for just two years, with four years of security patches. It recently committed to four years of system updates, with an additional year of security. Microsoft announced earlier this month that after support for Windows 10 machines ends in 2025, customers can continue receiving security updates for a fee.

By stretching devices’ lifespans, companies could reduce some of the 6.9 million tons of electronics waste we generate annually, according to nonprofit public-interest group U.S. PIRG.

Apple’s mixed reality meets the real world

Will Apple’s Vision Pro change the way we work by putting floating 3-D spreadsheets on our office walls? Will it make us all yearn to FaceTime with holo-grandma? Will it finally make 3-D movies cool? Or, at $3,499, will it be the world’s most expensive paperweight? We find out in early 2024.

In early trials, we’ve been impressed with just how natural it is to navigate the digital interface with just hand waves and finger taps. It still is quite a substantial piece of hardware you have to put on your head, however, battery pack and all.

Given its price tag and its first-generation status, the Vision Pro isn’t positioned to be a mainstream hit. Instead, Apple’s betting on early adopters and software developers to define the killer apps of spatial computing—the idea that we can blend our real lives and digital worlds in new ways. As Apple Chief Executive Tim Cook said during the Vision Pro’s introduction, it’s “the beginning of a journey.”

Cracks in Apple’s garden walls

Perhaps the president of the European Commission should just move her office to Cupertino, Calif. In 2023, EU legislation forced Apple to give up its proprietary Lightning port in favor of USB-C on the iPhone 15. Next year, EU regulation will push Apple to make additional changes.

While Apple’s App Store has been the only way to install apps on the iPhone, the EU’s Digital Markets Act aims to change that. It requires the “gatekeepers”—specific tech companies—to stop restricting users from getting apps from outside its own app stores. The deadline to comply is March 7. A recent Securities and Exchange Commission filing from Apple stated that the company “expects to make further business changes in the future” to the App Store. (Google’s Android already allows users to install apps downloaded from outside its Google Play app store.)

It’s unclear if Apple would change the App Store only in the EU or around the globe. An Apple spokesperson declined to comment on the company’s plans.

Then there’s Apple’s tightly protected iMessage. Beeper, a new app that brings iMessage to Android devices, has regulators pressuring the giant to open up its exclusive iMessage chat platform. Separately, Apple has agreed to adopt RCS, a messaging standard that will make “green bubble” texting with Android phones a bit more like iMessage.

Passkeys in more places

Passwords are lousy. When hackers exposed information belonging to around 6.9 million customers of DNA test-kit company 23andMe, the company said the attackers tried credentials stolen from other websites. Because people often reuse their usernames and passwords, thousands of logins worked.

That’s why, in 2023, companies including Google, Apple and Amazon moved toward passkeys, a type of login that can replace passwords and two-factor authentication codes. Starting next year, Microsoft will roll out passkeys for businesses.

A passkey is more secure than a traditional login because each is unique, it won’t work on fake sites designed to trick us and it can’t be stolen from company servers. It’s stored inside password managers and can be accessed with a face or fingerprint scan.

Today, over eight billion accounts are passkey-enabled, according to Andrew Shikiar, executive director of FIDO Alliance, which oversees security standards for passkeys. Shikiar expects 20 billion passkey-capable accounts by the end of 2024.

Rocking the vote in 2024

Millions can now generate images and videos with AI—and potentially influence elections around the world. In 2024, an estimated two billion people will vote in 50 countries. While manipulated media isn’t new, the ability to create convincing AI-generated sounds and imagery on a dime is. The White House said generative-AI systems have the potential to “erode public trust and safety in democracy.”

Former President Donald Trump posted a parody of Republican Ron DeSantis’s campaign launch with a video featuring AI-generated voice clones. In turn, a pro-DeSantis super PAC ran a television ad attacking Trump, using an AI-generated version of his voice. Meta Platforms is requiring advertisers to disclose when political ads on its Facebook and Instagram contain digitally altered media.

AI-enabled content isn’t the only concern. We can expect just as much or more old-fashioned disinformation compared with the last presidential election, too, said Erik Nisbet, a professor of communication at Northwestern University. That’s because some social-media platforms have either changed their policies or pared back their content-moderation efforts, Nisbet said.

Research has shown a particular rise in malign content on X, he added. The company didn’t respond to a request for comment. Meta now allows ads to say past elections were “rigged” or “stolen,” a false claim often repeated by Trump. At a conference, Meta’s head of global affairs said private-sector companies shouldn’t arbitrate whether politicians can “make claims or counterclaims about the legitimacy of previous elections.” Google’s YouTube will also no longer remove content questioning the legitimacy of former elections, saying the action could “have the unintended effect of curtailing political speech.”

Ride in a self-driving car—no, really

Robotaxis and self-driving vehicles in general had a rough 2023. GM subsidiary Cruise lost its license to operate in California and subsequently laid off about a quarter of its workforce. Tesla faced lawsuits over its “full self-driving system” on account of its apparent reliance on human monitoring, despite the marketing. And residents of San Francisco, the self-driving-est city in the U.S., expressed doubts about this technology.

Yet amid the chaos, there have been winners—in particular Alphabet subsidiary Waymo, which is continuing to expand its robotaxi service to more cities. If you travel to Phoenix, San Francisco, Los Angeles or Austin, Texas, you can hop in one of the company’s driverless taxis today. And it’s…surprisingly normal?

Meanwhile, Mercedes-Benz gained approval to roll out the first hands-free, eyes-off-the-road autonomous driving system in the U.S. It only works on certain roads, under certain conditions. Jeep and Chrysler parent Stellantis is working on a version, which it says will arrive in 2024. Ford says it will have its version in 2025.

No surprise, then, that in Phoenix, you can now hail a Waymo robotaxi through Uber, thanks to a recently announced partnership. Yes, the future is here. You just might have to go to Phoenix to find it.

Another social-media reckoning

As they seem to every year, Meta and TikTok face massive lawsuits, new laws, curbs from regulators, and the possibility of huge fines.

In 2024, Meta will have to contend with a grab bag of suits from more than 40 state attorneys general trying to force the company to change features of its products that the AGs allege harm minors. These include features that attempt to maximise teens’ and adolescents’ time spent on Meta subsidiary Instagram.

The company said: “We share the attorneys general’s commitment to providing teens with safe, positive experiences online, and have already introduced over 30 tools to support teens and their families.”

In December, the New Mexico attorney general filed a suit alleging the company steers predators to the accounts of children on Instagram. In a statement, Meta said it uses technology, industry protocols and partners in law enforcement, including state attorneys general, “to help root out predators.”

Should the suits somehow force Meta to make its products less appealing, they may accelerate users’ flight to TikTok. That could reignite the long-smouldering fire in Congress to ban the TikTok app outright. The initiative has won bipartisan support, but not enough to make it law. States have attempted their own remedies, but in November a federal judge blocked Montana’s TikTok ban, signalling that such state-level laws are unlikely to stand.

Meanwhile, age verification sounded like a promising move to protect kids on social media. But doing it effectively means clearing some high technical and administrative hurdles. It’s not likely you’ll see that in 2024.

Beyond heartbeats and nighttime Zs

Wearable gadgets have long tracked heart rate and sleep. Soon, they’ll be out for blood.

The Wall Street Journal previously reported that Apple is studying a way to track blood pressure through sensors in the Apple Watch. Next year—when Apple is expected to commemorate the watch’s 10th anniversary with a new design—the company might finally release the feature, which can notify a watch wearer when blood pressure is trending upward and direct the user to verify the measurement with a traditional inflatable cuff, according to a report in Bloomberg.

Other wearables may not be far behind. Fitbit filed a patent application for a display that could estimate blood pressure when pressed. Samsung has offered blood-pressure measurement on its Galaxy Watches for several years, though the feature isn’t available in the U.S. for regulatory reasons. Aktiia is a wrist-based wearable with an optical sensor that can capture 24/7 blood-pressure data. It’s currently only available in Europe, and is awaiting authorisation from the Food and Drug Administration for commercial availability in the U.S. Omron has a larger wearable device available in the U.S. now.

There’s certainly a market for this metric. The devices could make it easier to manage high blood pressure (aka hypertension), which affects as many as 119 million American adults, according to the Centers for Disease Control and Prevention.