How China Miscalculated Its Way to a Baby Bust
China’s baby bust is happening faster than many expected, raising fears of a demographic collapse. And coping with the fallout may now be complicated by miscalculations made more than 40 years ago.

The rapid shift under way today wasn’t projected by the architects of China’s one-child policy—one of the biggest social experiments in history, instituted in 1980. At the time, governments around the world feared overpopulation would hold back economic growth. A Moscow-trained missile scientist led the push for China’s policy, based on tables of calculations that applied mathematical models used to calculate rocket trajectories to population growth.

Four decades later, China is ageing much earlier in its development than other major economies did. The shift to fewer births and more elderly citizens threatens to hold back economic growth. In a generation that grew up without siblings, young women are increasingly reluctant to have children —and there are fewer of them every year. Beijing is at a loss to change the mindset brought about by the policy.

Births in China fell by more than 500,000 last year, according to recent government data, accelerating a population drop that started in 2022 . Officials cited a quickly shrinking number of women of childbearing age—more than three million fewer than a year earlier—and acknowledged “changes in people’s thinking about births, postponement of marriage and childbirth.”

Some researchers argue the government underestimates the problem, and the population began to shrink even earlier.

Following the data release, researchers from Victoria University in Australia and the Shanghai Academy of Social Sciences predicted that China will have just 525 million people by the end of the century. That’s down from their previous forecast of 597 million and a precipitous drop from 1.4 billion now.

“Our forecasts for 2022 and 2023 were already low but the real situation has turned out to be worse,” said Xiujian Peng, a senior research fellow at Victoria University who leads the population research in Melbourne.

China’s fertility rate is approaching one birth for every woman , less than half the 2.1 replacement rate that keeps a population stable. In the late 1970s, the fertility rate hovered around 3.

At the time, China was coming out of the chaos of the Cultural Revolution and about to embark on economic reforms. The country’s leader, Deng Xiaoping, and other officials became alarmed when a group of scientists told them that unless they started restricting births, China would have more than four billion mouths to feed in a hundred years.

An essay by some of the scientists published by the official People’s Daily in early 1980 suggested China’s search for a response to overpopulation “points to bringing the fertility rate down to 1…each couple having only one child.”

That fall, China started enforcing the one-child policy nationwide—but the calculations had missed some crucial factors.

Population fears

China wasn’t the only country worried about overpopulation at the time. The rapid rise in the global population in the 1960s and ‘70s prompted fears that humanity would reproduce faster than food production could rise, an idea argued nearly two centuries earlier by economist Thomas Malthus.

Chinese officials were increasingly reviving scientific research after the Cultural Revolution. While social scientists had been persecuted by Mao’s Red Guards, others doing work related to the military had been partly shielded.

The group included Song Jian, a protégé of the father of China’s atomic-bomb program and one of China’s top scientists working on satellites and rockets. Song had studied in Moscow, where he got advanced degrees in a branch of mathematics known as control theory and in military science. Military officials sent him to a launch site for rockets and satellites in the Gobi Desert to escape the chaos of the Cultural Revolution.

Song, who eventually became China’s senior cabinet member heading science and technology, is now 92. He didn’t respond to requests for comment sent to the State Council and the Chinese Academy of Engineering.

In 1975, Song had been part of a Chinese academic delegation visiting the University of Twente in the Netherlands, where he got to know a Dutch mathematician, Geert Jan Olsder. Three years later, the two met a second time, at a conference in Finland.

Olsder, now in his 80s, said he talked about how his research with other mathematicians had been inspired by the warnings about finite global resources and how mathematical models could be applied to birthrates.

Song spoke with the others in fluent English and showed a clear interest in mathematical modelling, Olsder wrote in an email. If the two hadn’t met, he said, he’s sure that some kind of population policy would have started in China, but perhaps a little later. “I feel like a domino stone in a long series of such stones,” he wrote.

Song refined his modelling over the next few years, and with a team of scientists began calculating how different fertility rates could affect China’s population size. In late 1979 he began to present officials with reports based on their modelling. He calculated that, at a constant fertility rate of three babies for every woman, China’s population would hit 4.26 billion by 2080.

With his computer-assisted mathematical models and political connections, Song caught the attention of top leaders. He argued that rapid population growth would prevent China from becoming a rich, modern country, said Susan Greenhalgh, an anthropologist at Harvard University who has written books about the one-child policy.

“He used a frightening narrative of a coming demographic-economic-ecological crisis to persuade people,” she said.

To ward off skepticism, officials said China could switch gears if births dropped too much. “In 30 years, the current problem of especially dreadful population growth may be alleviated and then [we can] adopt different population policies,” the Communist Party said in an open letter in 1980.

Within a little more than a decade, the fertility rate had dipped below the replacement rate. The cohort of young women was still massive, which kept the population growing. But the number of newborn girls was quickly dwindling.

Impact

As the decades passed, a growing number of demographers and economists called out the policy as outdated and flawed. China’s fertility rate would have gone down on its own as life expectancies rose and economic conditions improved, they say.

One factor missing from Song’s population math was human behaviour. The government’s sometimes brutal enforcement, including forced abortions and sterilisations, as well as decades-long propaganda about the benefits of having a small family , left a lasting one-child mindset. The modelling also failed to take into account the traditional preference for sons. If couples could only have one child, they would prefer to have a boy.

Young women are now at the core of China’s demographic dilemma. They are increasingly reluctant to have children—and there are fewer of them every year.

Greenhalgh, the Harvard anthropologist, said that the women growing up under the one-child policy were raised in line with Beijing’s goals of a smaller but what it called “higher-quality” population: well-educated, savvy and independent. “These women are not going to accept going back to the family to be housewives,” she said.

Apart from cultural and social changes, Song’s model hadn’t taken into account economic forces, such as the enormous migration flows to cities unleashed by Deng’s reforms, which played a bigger role than anyone had imagined in pushing down fertility rates, researchers have said.

Zuo Xuejin, a retired demographer who is leading the research team at the Shanghai Academy of Social Sciences, sounded alarms about demographic implosion more than a decade ago, saying the conditions that may have warranted birth-restriction measures had all faded away.

“For many years overpopulation was China’s major concern. It was difficult to convince the government and the public that China will have the problem of fast decline and aging of the population,” Zuo wrote in an email.

Song has said he believed it had been a good call. China had successfully defused the bomb that could have led to a “population explosion,” he wrote in a 2010 essay published by the University of Jinan, his alma mater. “Zero growth [in population] is the destiny of modern mankind and an urgent task for contemporary China,” Song wrote. He estimated China’s population wouldn’t start shrinking until after 2035. He was off by more than a decade, with official data showing the drop starting in 2022.

Beijing has said the policy prevented 400 million births, a claim it has often put forth as a kind of Chinese gift to the world, including at the 2009 climate summit in Copenhagen. Demographers have disputed the figure, saying China’s fertility rate would have gone down on its own as economic conditions improved.

Demographer scramble

Even when Beijing dropped the one-child policy in 2015, leaders didn’t abolish birth restrictions altogether. Instead, it just pivoted to a two-child policy. Now, Beijing is urging people to have three, trumpeting the need to return to a “birth-friendly culture.”

Entrepreneurs, economists and demographers have tried to convey the idea that China needs more babies .

James Liang , co-founder and chairman of travel service provider Trip.com Group and a research professor of economics at Peking University, co-founded YuWa Population Research Institute, a private think tank focused on demographic and public policy analysis.

Liang estimated that China needs to devote 5% of its gross domestic product—roughly equivalent to its education spending—on direct subsidies to promote births and lower the costs of raising children in order for the fertility rate to recover to 1.4, the average rate of advanced economies. His company gives its long-term employees an annual cash bonus of 10,000 yuan ($1,406) for each of their children until they are 5 years old.

Demographers are trying to catch up on the rapidly falling births. The United Nations’ population predictions for China, which were based on the country’s 2020 census and assumed a fertility rate of 1.19, are already out of step with reality.

Patrick Gerland, head of the U.N.’s population estimates and projection section, said their computing tries to capture long-term trends and isn’t made for rapid changes. He agrees with other researchers that put China’s fertility rate closer to 1.0.

“In the case of a country like China where the fertility from one year to the next year has been changing so fast, we’ll have smaller population [projections] than what we had expected two years ago,” he said. The U.N. plans to update its forecasts in July.

Yi Fuxian, a senior scientist in obstetrics and gynaecology at the University of Wisconsin-Madison and a critic of China’s birth restrictions, has long argued the situation is even worse than official data suggests. Yi believes China’s population actually started shrinking years ago, based on birth estimates pieced together from other available data, such as school enrolment and the number of vaccines for newborns.

“All of China’s population policies for decades have been based on erroneous projections,” Yi said. “China’s demographic crisis is beyond the imagination of Chinese officials and the international community.”

Once a generation of young people has made up their minds, it’s hard to change them, said Cai Yong, a sociologist at the University of North Carolina at Chapel Hill.

It’s possible fertility rates could now increase with official messages and policies promoting bigger families to a newer generation, said Cai, but “if it’s going to happen, it’s not going to happen in the short term.”
London Townhouse Amid ‘Ted Lasso’ Set Selling for £4.5 Million

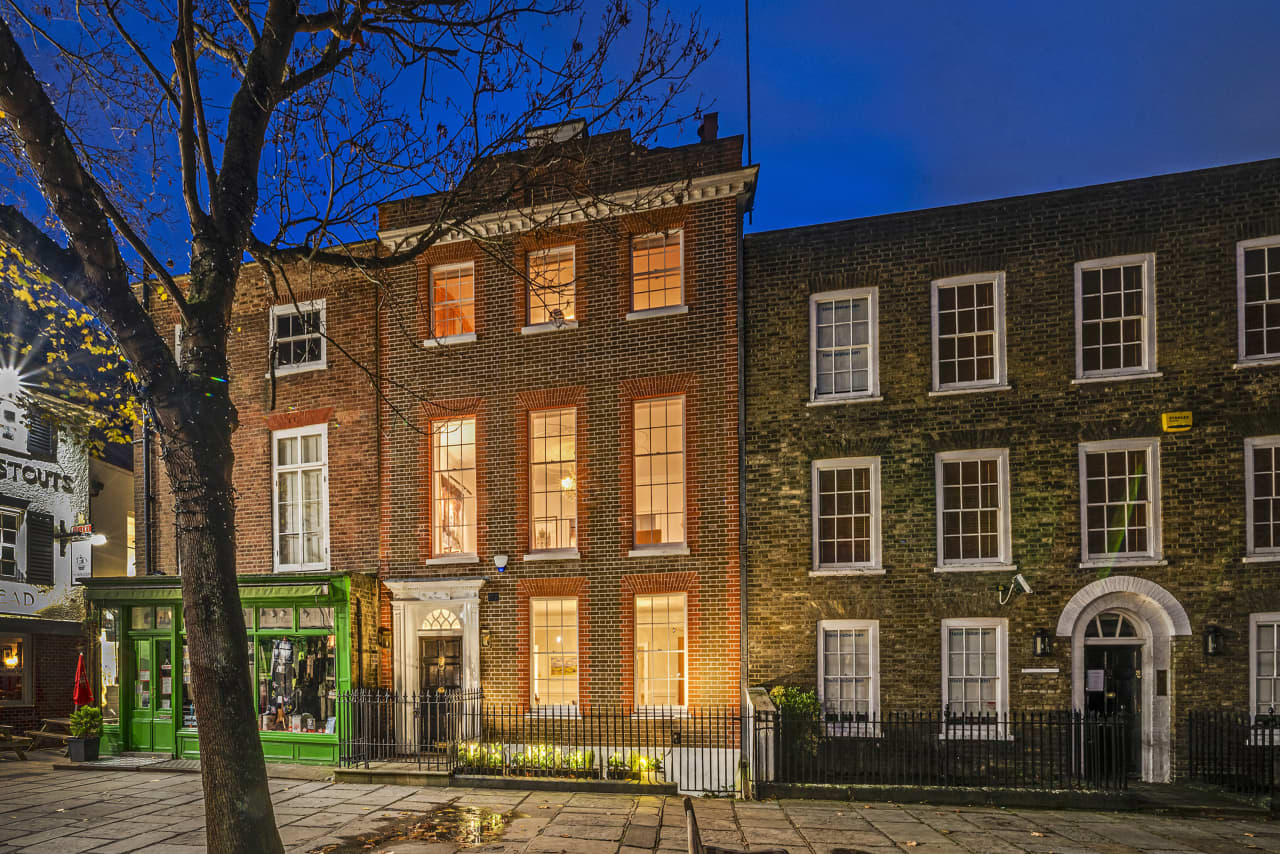
Fans of “Ted Lasso” take note: A lavish home in Richmond Green—a pocket of London that viewers of the much-loved Apple TV+ series will instantly recognize—has come to the market for £4.5 million (US$5.68 million).

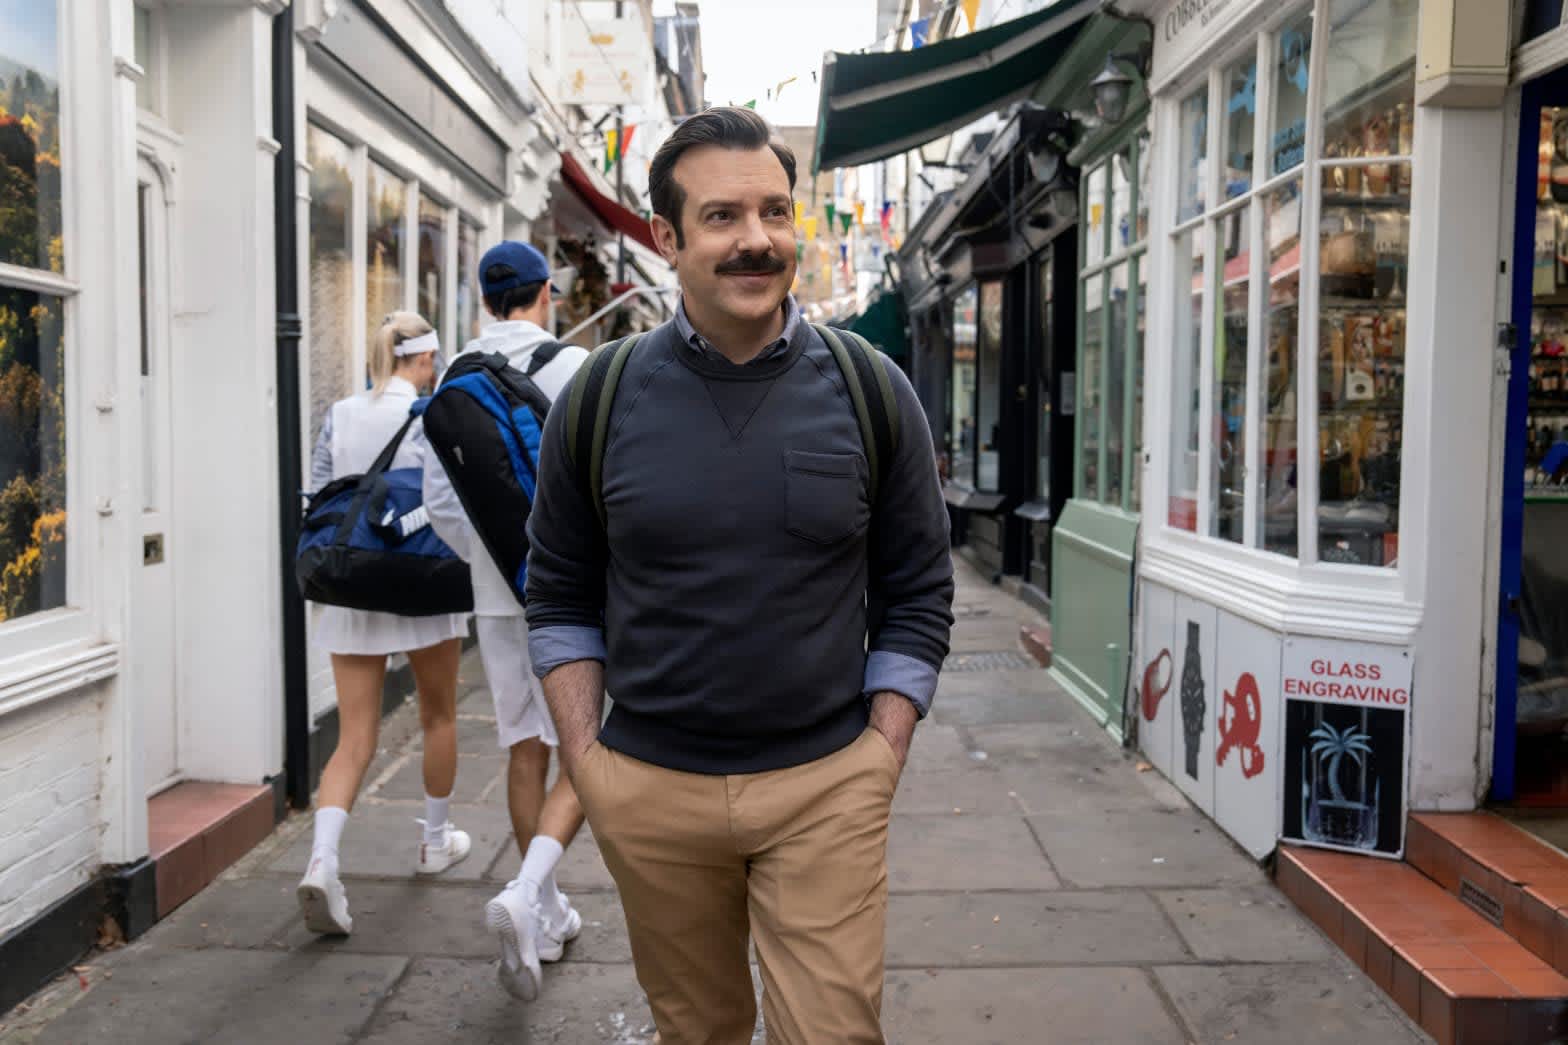
Richmond Green and the townhouse’s immediate surroundings were a major filming location for the Emmy Award-winning show. Ted’s flat is around the corner; the local pub, where Ted and Coach Beard go to grab a pint, is just steps away; and the green itself, directly in front of the house, featured in plenty of scenes throughout the series.

The red-brick house, which dates to the mid-18th century, is a “fabulous example of Georgian architecture and craftsmanship,” said listing agent Peter Norgrove of Savills, which brought the home to the market earlier this week. Richmond Green is a historic village “immortalized as Henry VII’s former jousting ground” and now, as the set of the hit TV series, Norgrove added.

“Ted Lasso” filmed all around Richmond Green, including on this side street, just steps from the house.
Apple TV+

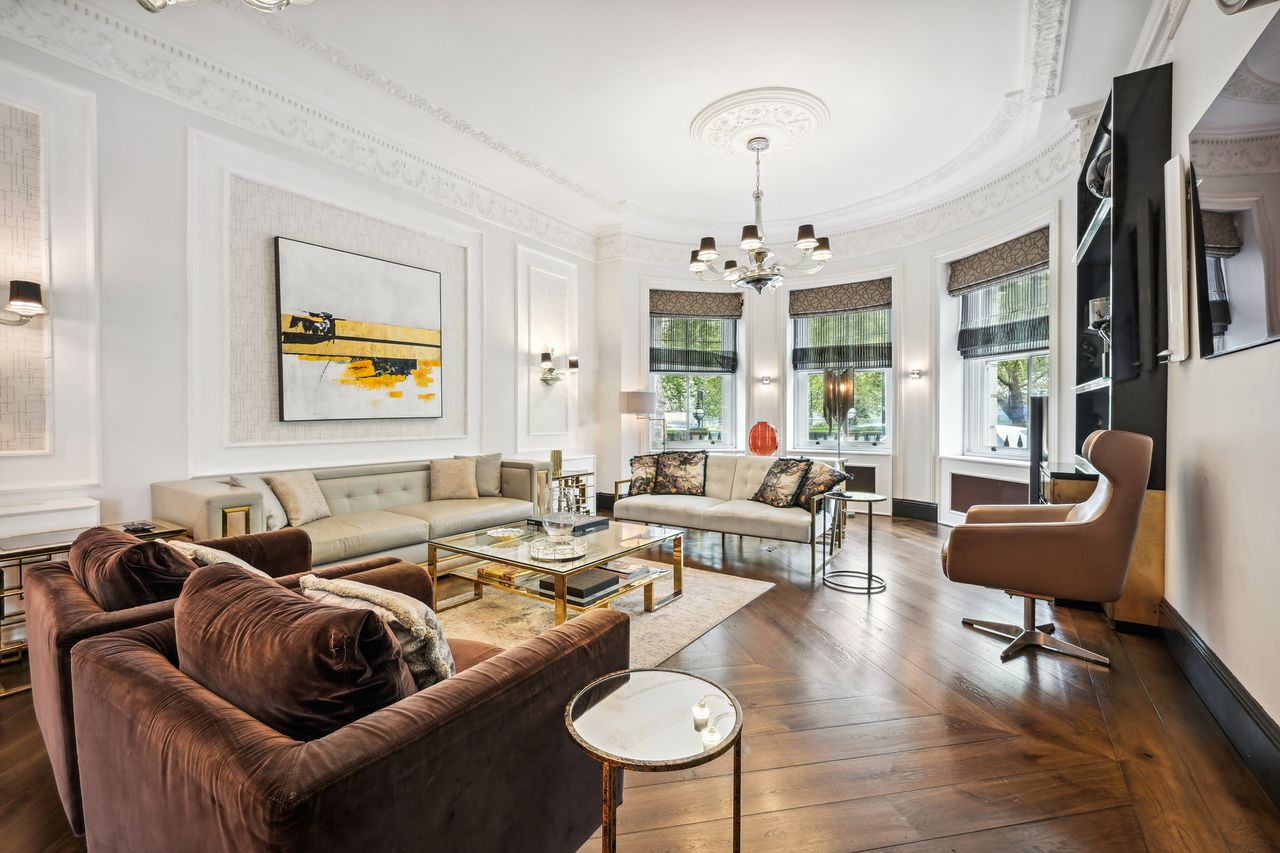
Set behind wrought iron railings, the four-bedroom property is loaded with period charm across its 3,698 square feet, from the high ceilings, fireplaces and ceiling cornicing to the window shutters, wide exposed floorboards and paneled hallway.

The sellers, who couldn’t be reached for comment, embarked on a “sympathetic renovation that has been carried out with great thought, depth of quality and attention to detail,” according to the listing.

There’s a drawing room that spans the full width of the house and features three floor-to-ceiling windows; a dining room; a media room; a bespoke kitchen with direct access onto the courtyard garden; a study; and four bedrooms including a sizable primary suite with views out over the Green.

The home last changed hands for £2.95 million in 2014, property records show.

This article first appeared on Mansion Global .

A weekend to get hearts and motors racing

It’s not often car enthusiasts have the opportunity to immerse themselves in an indulgent weekend of motorsports in the heart of Sydney. Yet, that is what Concours D’Elegance offers from March 1-3 2024 at Sydney’s Cockatoo Island. 

Raise a glass of Champagne Pommery to the classics of motoring with 40 collectors’ cars on show from all over the world and attend expert talks unveiling the history — and histrionics — of these incredible machines. 

If your tastes are more contemporary, there will also be a number of supercars on show, including McLaren, Lamborghini, Aston Martin and Bentley. For those keen to embrace the future of sustainable motoring, it’s an opportunity to see examples from Polestar, Rolls Royce and ARC up close.

With lunch prepared by renowned chef Sean Connelly, this is so much more than  a car show — it’s an unmatched motoring experience. Whether you are a motoring lover — or you know someone who is — this is a rare opportunity to be among the best things on wheels at an exclusive event.

Reserve your tickets for the best three days of automotive heritage, modernity, and indulgence at the Sydney Harbour Concours D’Elegance.

Reserve your tickets for the best three days of automotive heritage, modernity, and indulgence at the Sydney Harbour Concours d’Elegance.

Use the discount code [ROBBREPORT20] when you purchase tickets to get 20% off. 

Book here  for an unforgettable experience.

Strong auction results point to the return of buyer confidence

The weekend showed the highest preliminary property auction clearance rates since mid year 2023, new data shows.

The CoreLogic weekend market summary reports that the capital city clearance rate hit a high of 76.2 percent, the strongest result since the first week of June last year.

CoreLogic research director Tim Lawless said the results were a further rise since the previous week’s preliminary clearance rate at 73.9 percent, which was later revised down to 68.3 percent, and represented further evidence of solid rebounds in property prices.

He says the auction results may be a reflection of rising confidence amongst buyers in anticipation of an earlier than expected drop in interest rates.

“The newfound strength in auction markets is a radical turnaround from the December results last year, where the preliminary capital city clearance rate fell to the mid 60 percent range while final clearance rates dropped to the mid 50 percent level,” Mr Lawless said. 

“The early part of the year can show some seasonality, however, with both the volume of auctions and the clearance rate coming in high over the past two weeks, it looks like the year has started with a much better fit between buyer and seller pricing expectations.”

China’s Carbon Emissions Are Set to Decline Years Earlier Than Expected

China’s massive rollout of renewable energy is accelerating, its investments in the sector growing so large that international climate watchdogs now expect the country’s greenhouse-gas emissions to peak years earlier than anticipated—possibly as soon as this year.

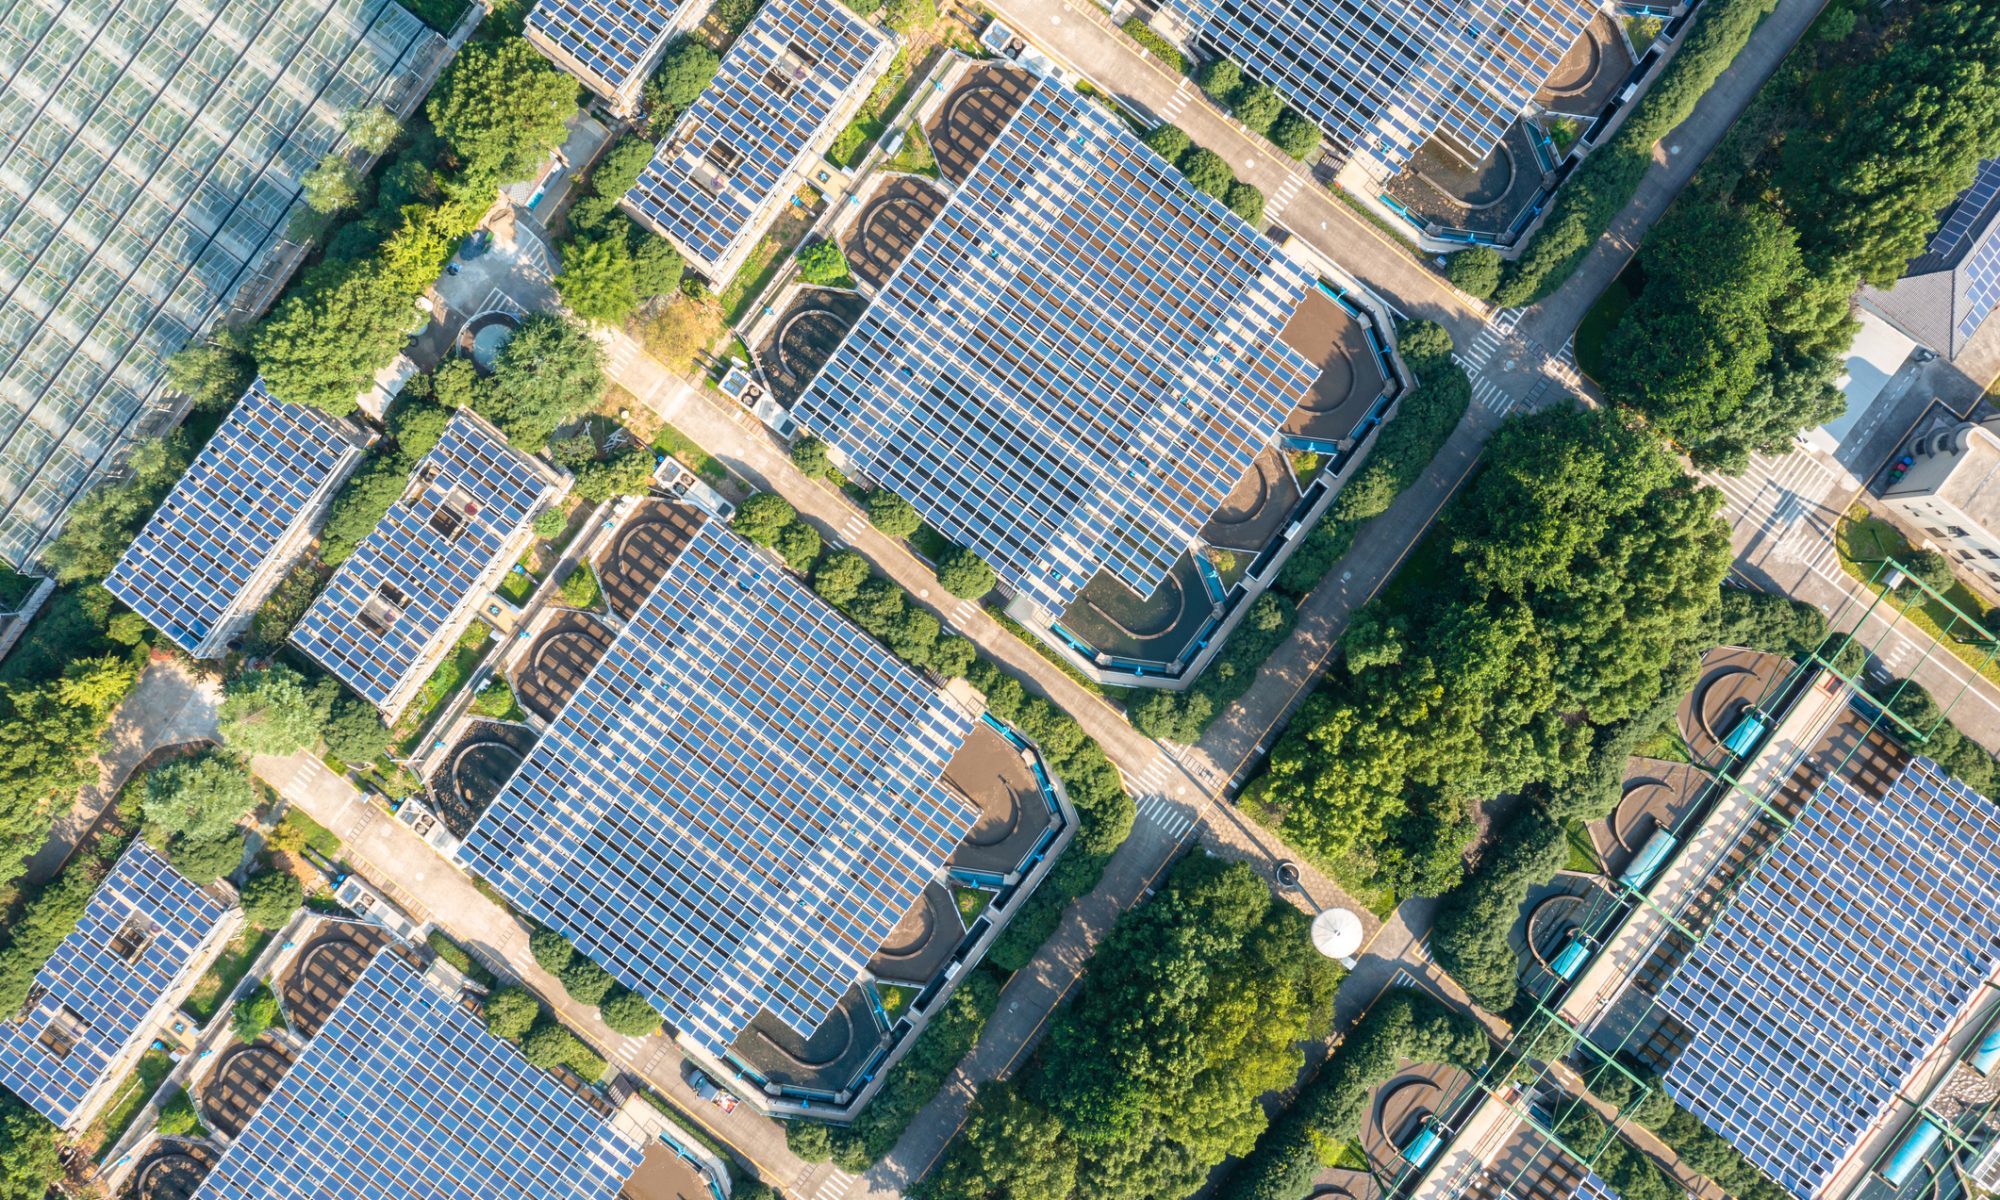
China installed 217 gigawatts worth of solar power last year alone, a 55% increase, according to new government data. That is more than 500 million solar panels and well above the total installed solar capacity of the U.S. They appeared everywhere from the deserts of Inner Mongolia to the mountains of southwest China to rooftops across the country, including on the Great Hall of the People on the edge of Tiananmen Square.

Wind-energy installation additions were 76 gigawatts last year, more than the rest of the world combined. That amounted to more than 20,000 new turbines across the country, including the world’s largest, planted on towers in the sea off China’s east coast.

The low-carbon capacity additions, which also included hydropower and nuclear, were for the first time large enough that their power output could cover the entire annual increase in Chinese electricity demand, analysts say. The dynamic suggests that coal-fired generation—which accounts for 70% of overall emissions for the world’s biggest polluter—is set to decline in the years to come, according to the Paris-based International Energy Agency and Lauri Myllyvirta , the Helsinki-based lead analyst at the Centre for Research on Energy and Clean Air.

China’s expanding renewables footprint is shaping the global response to climate change. Its companies are the leading manufacturers of clean-energy technology, from solar panels and wind turbines to electric vehicles. That is stoking concerns in the rest of the industrialized world about depending on China for their energy supplies in the future.

At the same time, China’s deployment of renewables at home is breathing new life into international climate diplomacy . Its rapid emissions growth long provided fodder for critics who said Beijing wasn’t committed to fighting climate change or supporting the Paris accord , the landmark climate agreement that calls for governments to attempt to limit warming to 1.5 degrees Celsius over preindustrial temperatures. Now, analysts and officials say Beijing’s efforts are lending momentum to the Paris process, which requires governments to draft new emissions plans every five years.

“An early peak would have a lot of symbolic value and send a signal to the world that we’ve turned a corner,” said Jan Ivar Korsbakken, a senior researcher at the Oslo-based Center for International Climate and Environmental Research.

In 2020, Chinese leader Xi Jinping pledged that the country’s emissions would begin falling before 2030 and hit net zero before 2060, part of its plan prepared under the Paris accord. He also said China would have 1,200 gigawatts of total solar- and wind-power capacity by the end of this decade. The country is six years ahead of schedule: China reached 1,050 gigawatts of wind and solar capacity at the end of 2023, and the China Electricity Council forecast last month that capacity would top 1,300 gigawatts by the end of this year.

“China’s acceleration was extraordinary,” said Fatih Birol , the executive director of the Paris-based International Energy Agency.

Chinese authorities publish regular data on energy consumption and generation but not overall greenhouse-gas emissions. Transition Zero, a U.K.-based nonprofit that uses satellite images to monitor industrial activity and emissions in China, says the official data are “broadly aligned and consistent” with theirs.

Once the peak arrives, some analysts expect an emissions plateau to follow rather than a rapid fall in the following years. That is a problem, scientists say, because the world’s major emitters must sharply cut global emissions this decade—by 43% compared with 2019—to fulfill the Paris accord.

Climate Action Tracker, a scientific consortium that evaluates governments’ emissions plans, rates China’s current policies as “highly insufficient” to meet the 1.5 degrees Celsius goal . Its latest analysis, published in November, says China’s emissions should peak by 2025. If wind and solar installations can average 300 gigawatts a year—as they did last year—China’s emissions should fall significantly by the end of the decade, the consortium says. The actions and policies of the U.S., where emissions have been falling, were graded as “insufficient.”

Still, moving China’s timeline for an overall emissions peak forward could shave off around 0.3 to 0.4 degrees Celsius of projected global warming if emissions started to decline next decade, analysts say. Emissions plans submitted to date under the Paris accord would put the world on track to warm by 2.5 degrees Celsius this century, a United Nations Environment Program report said in November.

China is still building coal-fired power plants , fueling criticism from Western officials that it is locking in carbon-dioxide emissions years into the future. Beijing has been telling Western officials that the new plants won’t be as polluting as they fear. They are replacing older, higher-emitting plants, and will run far below full capacity, used largely to maintain electric-grid stability as China generates more of its power from intermittent wind and solar. In November, China unveiled a system of capacity payments for coal-fired plants that will allow them to earn money even when they are running as backup power sources. Xi said in 2021 that China would begin to phase down its coal consumption starting in 2026.

The exact timing of China’s peak depends on factors such as economic growth and weather in the next few years, analysts say. Growth is expected to slow following China’s real-estate sector slump —unless Beijing undertakes a major new program of economic stimulus that would boost industrial emissions. Another spell of drought this summer would push the country’s coal plants to run harder to replace lost hydropower generation.

The most certain variable in the equation is the breakneck pace of China’s renewable-energy rollout, which analysts expect will continue to add 200 to 300 gigawatts of new wind and solar capacity a year. The investments in renewable energy have become a major driver of the Chinese economy. The country’s clean-energy spending totaled $890 billion last year, up 40%. Without that growth, investment in China would have been flat as the country reels from the slump in its real-estate sector, according to the Centre for Research on Energy and Clean Air.

The investments include clean-energy installations and the construction of enormous factories to produce solar panels, wind turbines, batteries and electric vehicles—turning the country into the leading manufacturer of clean tech. Its factories in those sectors now have plenty of unused capacity . The adoption of electric vehicles is happening so rapidly that analysts say peak gasoline demand in China was already reached last year.

At the United Nations COP28 climate conference in Dubai in November, Xie Zhenhua , then China’s climate envoy , said the government would calculate the year and absolute volume of the country’s emissions peak. He also said Beijing is drawing up its next emissions plan under the Paris accord.

“Our country will do as it’s said and strive to do even better,” he said. “I have faith.”

These Families Are Shutting Down the Bank of Mum and Dad

The parents have been paying the monthly phone bill and covering rent for far longer than in prior generations . Some are helping their children with down payments to buy homes. Others are putting a roof over their kids’ heads well into their 20s and 30s to help them save because they can’t cover rising costs of living.

That comes with a price tag. More than a quarter of parents who are helping their children financially said it caused them to postpone retirement, according to a recent Credit Karma survey . More than half had to cut back on living expenses and about a third took on debt.

Feeling stretched, they are negotiating the terms of separation.

Nancy Clark and her then-28-year-old son, Reid Clark, had just sat down to dinner in June 2022 when the conversation turned to when he would move out. The topic had come up before, but this time they decided to set a date one year later.

Nancy, now 60, said she remembers thinking: “I know that becoming financially independent needs to feel a little painful.”

Reid set off on his own last June. He ditched a job managing his family’s three ice cream shops in New Hampshire for a gig as the assistant to a professional ice hockey team’s mascot in St. Paul, Minn. He also works at an M&M’s store.

Nancy bought him groceries when he moved in and occasionally gives $50. By this June, Reid will no longer get any financial help if he’s short. He hasn’t needed to hit up his mum for rent money in the past few months. “I want to chart my own path in life,” he said.

Taking such a gradual approach and framing the conversation around gaining financial independence give it a positive spin, said Rocky Fittizzi , a wealth strategies adviser at Bank of America Private Bank. Telling your children you’re cutting them off suggests it is a punishment.

An emotional decision

Many adult children are living at home, or moving back in, to save money. The cost of food and rent have jumped, and more college graduates are saddled with student debt. The share of 25-to-29 year-olds with student loans rose to 43% in 2022 from 28% in 1992. The rise was even bigger for those between 30 and 34, according to a recent report by the Pew Research Center.

Some 20% of men and 12% of women between 25 and 34 years old lived at home last year, far higher than two decades ago, according to Census Bureau data.

During the pandemic, layoffs and money strains forced some adult children and their parents to live together and share finances, said Arne Boudewyn at Insights Squared Consulting Group, a family wealth consulting company.

Worries over losing the close bonds forged during those years may add to the stress of ending monetary help, financial advisers said.

“Letting go is often harder for parents these days because we need to feel needed as much as we want to feel wanted,” said Bobbi Rebell , the founder of Financial Wellness Strategies, which gives workshops for parents about how to teach their children to be financially responsible.

Tough love, but not too tough

Pam Lucina still remembers the day about 30 years ago when her father told her she was off the payroll. She was in her first year of law school. Her parents had paid for her undergraduate education. Because she assumed they would pay for law school too, she had chosen a pricey school.

She graduated with $40,000 in student debt and couldn’t afford to contribute to her 401(k) for about five years.

“I know that my parents sacrificed to give me what they did and I’m grateful for all of their past support but I wish I had been more prepared,” said Lucina, 52, now an executive vice president at Northern Trust .

Lucina said the experience was a main reason she became a financial adviser. She has three daughters, and recently asked the oldest to complete her own college financial-aid form.

She tells clients that even if they have good intentions when cutting off their kids, it can feel to the children as if their parents are withholding money to punish them.

“Assure them that love is not contingent on finances,” she said.

Create an exit strategy

There are times when financial help is necessary. With a health issue or addiction, parents often use a special needs trust, where funds typically go directly to the child’s treatment and recovery. Others may opt to help children temporarily after a layoff.

But financial advisers said parents need to set boundaries.

Ashley Kaufman ’s parents told her she would need to move out of their Manhattan apartment, where she was living rent-free, once she saved $100,000 for a down payment on her own place.

The cybersecurity consultant hit her goal by the time she was 25, but she wasn’t sure she was ready to move out right then. She enjoyed seeing her younger siblings regularly and playing with her family’s dog named Waffles, she said. Her parents encouraged her to go to some open houses anyway.

Kaufman, who is the stepdaughter of Rebell from Financial Wellness Strategies, is now 27. She bought her apartment around two years ago.   She’s happy to be building equity in her place.

“I’m glad my parents gave me a little nudge,” she said.

—Julia Carpenter contributed to this article .

‘Mornings on the Seine’ Painting by Claude Monet Could Fetch Nearly $23 Million

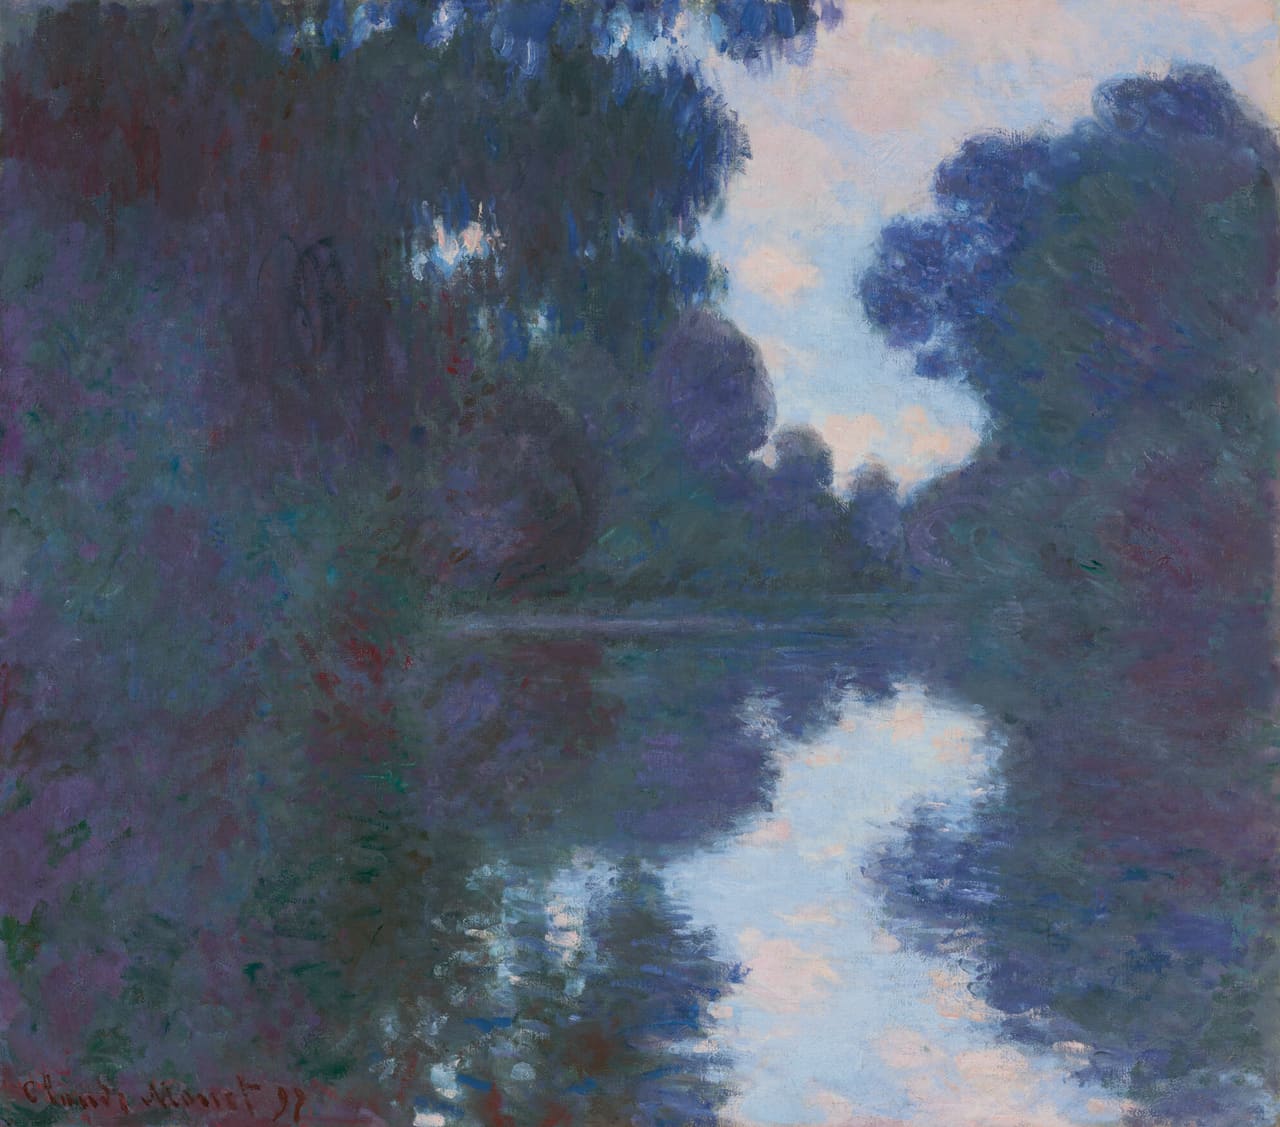
Christie’s will sell a painting from Claude Monet’s Matinées sur la Seine series at its evening sale of 20th- and 21st-century art on March 7 in London for an estimated price of up to £18 million (US$22.7 million).

Matinée sur la Seine, temps net (Mornings on the Seine, clear weather) , 1897, was consigned by an unnamed collector who bought it in May 1978 at a Sotheby’s auction in New York for US$330,000, according to Christie’s. The painting is among early examples of Monet’s practice of serialising specific scenes, “a technique that would ultimately transform his art,” Christie’s said in a news release.

In this example, Monet painted the river Seine during summer mornings in 1896 and 1897. “Tracing the sun as it passes over the scene, from the first rays of light at dawn, to the full brilliance of the sun at mid-morning, this extraordinary sequence of works was conceived as a connected, interrelated sequence of canvases,” Christie’s said.

A viewer can see the sun rising across the canvases when they are exhibited as a group, the auction house said. It was after Monet painted the Creuse valley in central France at different times of day in 1889 that he returned to the idea of serialization. A painting from the Creuse series, Prairie fleurie à Giverny , 1890, also will be offered during the March 7 evening sale. Christie’s has not placed a value on the work yet, which is being consigned from a Japanese collection.

Another example from the Seine series, also painted in 1897, sold at Christie’s in November 2017 from the collection of Nancy Lee and Perry R. Bass. Titled simply Matinée sur la Seine , the painting sold for nearly US$23.4 million. Matinée sur la Seine, temps net has not been seen publicly since 1990, when it toured in an exhibition titled “Monet in the ‘90s: The Series Paintings,” which opened at the Museum of Fine Arts in Boston before traveling to the Art Institute in Chicago, and the Royal Academy of Arts in London.

The painting will be on view in New York from Friday through Wednesday, before being shown in Hong Kong from Feb. 21-23 and then in London, March 1-7.

The Spectacular Crash of a $30 Billion Property Empire

René Benko was a high school dropout and convicted criminal. But by 2018, he was at the pinnacle of global real estate.

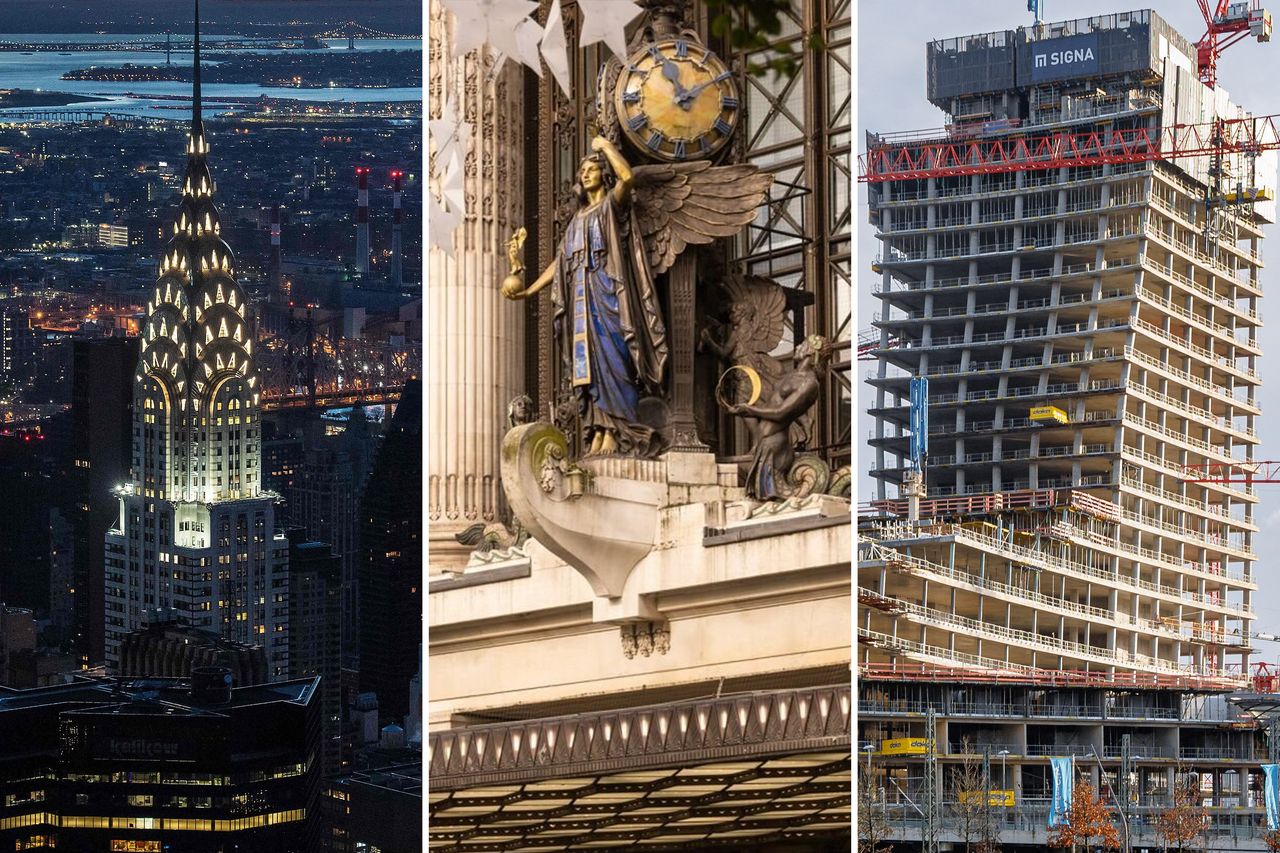
His company, Signa Holding, launched a glassy, J-shaped skyscraper on the banks of the River Elbe in Hamburg, Germany. The design of the 800-foot tower resembled a chart showing exponential growth. Hamburg’s mayor, the future German Chancellor Olaf Scholz , lauded Signa’s good reputation with banks when the city picked the developer to build the tower.

“Signa is financially strong,” he said. It wasn’t.

Benko’s sprawling, $30 billion empire of trophy real estate and department stores has imploded into the biggest property bankruptcy in Europe since the global financial crisis. The mess threatens to unleash significant losses on scores of lenders and investors and freeze half-built developments in numerous city centers.  Stakes in Manhattan’s Chrysler building , upscale British retailer Selfridges and sporting- goods groups in the U.S. and Europe face the block. Auctioneers are selling off Signa’s bookshelves, doormats, 700-bottle wine collection and a diamond-shaped award for Europe’s 2021 real-estate brand of the year.

The Hamburg tower is halted—leaving a 330-foot tall concrete stump. The unravelling marks a dramatic reversal for the self-made entrepreneur, who once lavished backers with hops on his yacht, a top-of-the-line Bombardier Global Express jet and trips to Signa’s multiple Austrian hunting grounds, complete with a shooting guide on the company payroll.

Left tallying their losses are heirs to the Tetra-Pak and Peugeot family fortunes; billionaire Ron Burkle ; and marquee sovereign-wealth funds from Singapore, Saudi Arabia and the United Arab Emirates. Dozens of banks lent money, including Citigroup and Swiss bank Julius Baer, whose chief executive resigned on Feb. 1 after the bank wrote off $700 million on loans tied to Signa. Spokespeople for Citigroup, Julius Baer, Peugeot Invest , Singapore’s GIC, and the UAE’s Mubadala declined to comment. The others didn’t respond to requests for comment.

Insolvency administrators say they are still getting to the bottom of the group’s corporate structure. But public filings, investors and former employees paint a picture of an empire that combined persuasive salesmanship with extreme financial engineering—an unsteady foundation that crumbled when the low interest rate era ended. In fundraising presentations, Signa told investors it was offering conservative, low-debt investments in iconic properties to be held for generations. Investors said they have since learned through Signa’s legal filings the companies had far more debt than they knew.

Many were invested in discrete parts of the larger company, unaware of convoluted cross-investments and large amounts of borrowing across hundreds of vehicles. An attorney for Benko said a list of questions sent by The Wall Street Journal contained “credit-damaging” and inaccurate allegations, but declined to provide specifics.  

Some of Benko’s associates disagree that Signa’s structure was at fault, but rather see the implosion as a result of herd behaviour by lenders. Former Austrian Chancellor Alfred Gusenbauer, who served on Signa company boards, told Austrian state radio in January that the group overextended in retail, draining cash, and that the European Central Bank told banks not to provide more financing. ECB supervisory board chairman Andrea Enria has called that suggestion bizarre, and said Signa wasn’t targeted, but rather part of a broader examination of banks’ commercial real-estate exposure.  

Benko, 46, was raised with modest means in Innsbruck, the quaint Austrian city nestled in the Alps. He was a star junior indoor climber and, at 17, dropped out of high school and began converting attic lofts, he has said in Austrian media interviews. He said he raised money from an heir to a gas station fortune, and quickly built up his business, expanding throughout the 2000s. He ran into trouble in 2012, convicted of an elaborate scheme in which prosecutors said he commissioned a former Croatian prime minister to push Italian officials including Prime Minister Silvio Berlusconi to help contest a tax bill on Signa-owned Italian properties.

Though the tax bill wasn’t reduced and the court said money never changed hands, a judge called it a “model case of corruption,” Austrian media reported at the time. Benko was sentenced to the equivalent of probation. It could easily have been a fatal business blow. Such convictions are typically toxic in the eyes of the large lenders and major investors that fuel the market. Instead, Benko trained his salesman skills at wealthy European families who could be swayed by his personal pitch, former employees said. He met scions of one family fortune after another for dinners over glasses of Château Lynch-Bages, which sells for $200 a bottle, they said. He plopped down a specially made hard-bound book half the size of his desk. Paging through photos of property after property, he would tell stories behind the deals and rattle off detailed numbers from memory, staring into the eyes of his would-be investors for what some said were uncomfortably long periods.

Officially, Benko wasn’t in charge. Around the time of his conviction, he structured the companies so he was neither Signa’s chief executive nor on its executive board, instead serving as chairman of an advisory board. But inside Signa, Benko ran the show, making critical decisions and appeared indistinguishable from a normal CEO, former employees said. Funds eventually rolled in from Switzerland’s Falcon Bank and Ernst Tanner , the chairman of chocolate maker Lindt & Sprüngli and from local Austrian lenders. Signa snapped up buildings in Vienna’s historic “Golden Quarter” and department stores like   Munich’s Oberpollinger. Benko boasted Signa was second only to the Catholic Church in owning Vienna property.  One key to Signa’s growing empire was a financial maneuver in which Benko’s companies functioned as both landlord and tenant for department stores. This allowed Signa to reap outsize benefits by moving money from its department store business to its landlord business through hiked rents, former Signa employees involved said.  That extra rental income was worth far more in the landlord arm through what a former employee called “multiple arbitrage.”

Long-term leases instantly increase the value of properties substantially—and investors tend to value income at landlords at more than 20 times the annual proceeds. At retailers, where business is seen as more fickle, investors value it at less than half that level. This allowed the real estate unit to borrow and raise investment based on the higher valuations.  In 2012, Signa joined with mining magnate Beny Steinmetz to buy a portfolio of Karstadt department stores, a chain that dots Germany. The following year, Signa raised rents on a chunk of them and extended the leases to 30 years in return for upfront cash payments. Signa’s Karstadt unit reported the total amount it owed for leases jumped to €3.9 billion, up from €3.3 billion the prior year, according to corporate filings.

A person close to Steinmetz said the joint venture with Signa lasted only three years and that his team wasn’t involved in day-to-day management. He added the Steinmetz organization hasn’t had any contact with Benko or Signa since 2015. Benko and others at Signa justified the rent hikes by saying the department stores had been paying below-market rates, and that Signa would modernize and turn around the money-losing businesses so they could eventually afford the higher payments, former employees said. High-profile acquisitions like Karstadt and the growing roster of wealthy backers helped Benko attract high-profile allies. Former Morgan Stanley Chairman Walid Chammah advised him on fundraising; Gusenbauer, the former Austrian chancellor, and a deputy chancellor both joined his board, and the Peugeot family invested . 

The value of properties reported by his two main real-estate companies rose to €3.6 billion in 2014, surpassed €10 billion in 2017 and more than €18 billion by 2020—extraordinary growth in a slow-moving sector.  Luxuries piled up, including a ski chalet, fine art, two private jets and the Roma, a 203-foot yacht, which Benko parked in front of Europe’s annual real estate conference in Cannes, France, former employees said.  Signa purchased a stake in two Austrian newspapers in 2018, and further expansions in retail gave it a giant department store empire across Austria, Germany, Italy and Switzerland.

Benko pushed into the U.S. in 2019 with a splashy purchase: Signa and a partner paid about $150 million for the Chrysler Building, giving each a 50% stake. Photos of the art deco skyscraper went up around Signa’s offices.  As they grew, Signa’s real-estate companies boasted high profits—on paper, at least. Signa called itself “the best performing real-estate company in Europe” in a 2018 investor presentation Between 2017 and 2021, the main real-estate unit, Signa Prime, had a combined €3.4 billion in profits, it said in Austrian corporate filings.

But all of Signa’s profits over that period were from paper gains. Signa marked up the values of its own properties by €4 billion, meaning the company would have otherwise reported substantial losses.  In the same period, Signa Prime spent more on interest payments and dividends—€1.9 billion—than the €1.6 billion it received in rental revenue, an unusual situation for a large property owner.  Pushing up values was a key focus within the company, former executives said. Employees focused heavily on appraisals, giving rent projections and other evidence to outside appraisers in a bid to get high values, according to those employees. Many investors and lenders relied on the outside appraisals. Dividends were based largely on property values, so higher values boosted returns. Appraisers valued the company’s office properties at 41 times the income they produced in 2021, corporate filings show. Comparable publicly traded office companies’ property portfolios were valued around 20 to 25 times income, according to Green Street, a real-estate advisory firm.

Signa’s figure “doesn’t make sense for any portfolio,” said Peter Papadakos , head of European Research at Green Street. “That’s something I’ve never seen for listed office companies.” He said Signa’s numbers for its hotel and retail properties—valued at 30 times annual income in 2021—were similarly off the mark.  Rising paper values allowed Benko to boast of low debt ratios, hovering around 50% of building values, he told investors, according to presentations. That left a healthy buffer in case the market turned.

Some properties, however, had a layer of debt on corporate shells that sat between the properties and the real-estate company, which itself had numerous layers of debt.  Benko’s 50% calculation typically omitted billions of dollars in liabilities that increasingly weighed on its finances. Called Genussscheine, a hybrid between debt and equity, it promised investors a share of any profits in a year from Signa companies or individual projects. Even though under German accounting principles it isn’t technically categorised as debt, interest was steep—in the high single digits—on some of these notes and they had to be repaid or refinanced upon maturity.  As Signa grew and Covid hit, rents proved unsustainable at the department stores. In 2020, Signa’s German department store unit filed for bankruptcy. To make sure the company would continue to pay the high rents that underpinned Signa’s property values, Signa gave the unit a 200-million-euro lifeline in the form of a loan that was later forgiven. Meanwhile, Signa needed money to fund dividends and an array of large developments started in city centers around Europe.

In December 2021, a unit of the Benko empire that sold bike and tennis gear went public by merging with a special-purpose acquisition company established by Ron Burkle’s Yucaipa. Citigroup gave loans and big U.S. mutual funds bought bonds. A Benko family trust owned nearly half of the stock, which was worth $3.2 billion at its peak. Signa joined with Central Group—run by Thailand’s Chirathivat family—to pay $5 billion for Selfridges, the tony British department store chain known for ostentatious displays on London’s Oxford Street. The Saudi Public Investment Fund helped fund the deal. The empire wobbled in late 2022, when a triple whammy hit. Prosecutors in Austria raided Signa Holding’s offices as part of a sprawling probe into alleged government corruption.

Galeria, Signa’s flagship German department store, filed for insolvency in October 2022, after limping for years. And the sports arm called on Benko for hundreds of millions of dollars in emergency money because of plunging sales. Benko started showing signs of stress. During the day, he would hype himself up by drinking over half a dozen espressos and chain smoke one Cuban cigar after another, filling his jet’s cabin with smoke, former employees said. He had a bad temper, the former employees said. In one meeting, he called his chief financial officer a “fette Sau,” or a “fat pig,” according to a person who was present. In spring 2023, Signa Development, one of Benko’s many arms, sold some buildings to raise cash. But the proceeds didn’t stay with the company, according to people familiar with the matter and statements from ratings agencies.

Instead of being reinvested into the company and ongoing developments as required under the terms of bonds it issued, the cash flowed to other Signa companies, the people said. Fitch Ratings called it a “breach of financial separation” that wasn’t supposed to happen.  In August, Signa sold a resort overlooking Lake Garda to a Benko family trust.  Signa wasn’t able to find a loan crucial to paying for the rest of the Hamburg skyscraper that was under construction and stopped paying its contractor.  In October, Signa Holding backed out of paying Signa’s U.S. sports retailer another €150 million it had promised. The publicly traded retailer declared bankruptcy days later.

A €200 million bond went unpaid by Signa Prime the next month. The defaults sparked a cascade of insolvencies, first by Benko’s holding company, and then by Signa’s two main real-estate companies. Two days before the holding company filed for bankruptcy, it sold a ski chalet to an entity controlled by the “Laura Foundation,” a Benko family trust that shares the name of one of Benko’s daughters, according to corporate filings.  More insolvencies within the Signa web are expected, and investors and lenders are bracing for the final bill. Bonds tied to Signa Development are trading at just 13 cents on the dollar, implying the debt investors think they may lose virtually everything.  Numerous Signa development sites have stalled, leaving boarded-up sites in Munich, Berlin and Düsseldorf. The site of the 800-foot Hamburg tower sits idle, with Signa’s name on the fence covered with graffiti as politicians debate its future.

The Australian property investment market bounces back

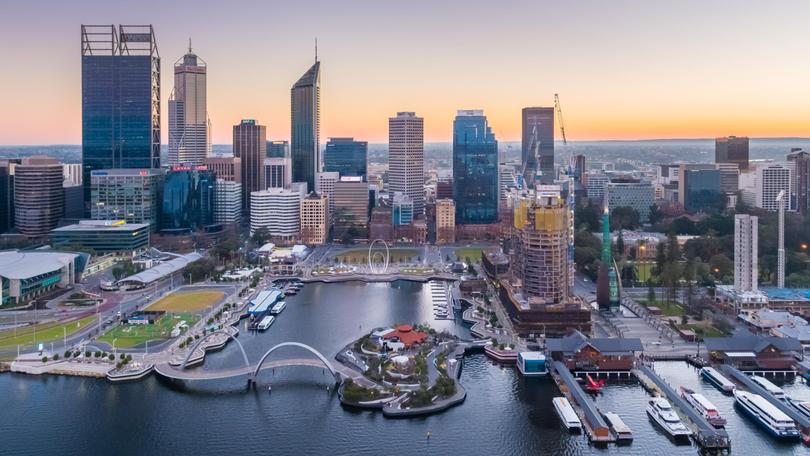
Aerial: Perth city skyline Elizabeth Quay

Investors are returning to the property market after an exodus in early 2023 and a significant decline in investor buying between 2015 and 2020. The lack of investor activity has been seen as a  contributor to today’s massive undersupply of rental homes. That five-year decline began after the banks applied higher interest rates to investor loans in a bid to slow investor loan growth, as requested by the prudential regulator.

However, the latest lending data from the Australian Bureau of Statistics shows a 20.4 percent increase in the value of investor loans over the past year, indicating more investors are buying property. This is welcome news for renters across the country, who are finding it exceedingly difficult to secure affordable accommodation amid rapidly rising rents and record-low vacancy rates of about 1 percent.

Last year’s surprisingly strong price growth across most of Australia’s markets has likely inspired more investors to look at property again. Capital growth is typically the primary goal of new investors, with yield seen as simply a way to help pay off the mortgage over time. However, yield becomes more important when interest rates are rising, and a 40 percent increase in rents since the pandemic means many city and regional markets are now delivering healthy yields above 5 percent.

Investors are also increasingly looking beyond their own neighbourhoods for more attractive property investment opportunities, typically in cheaper markets. Research by MCG Quantity Surveyors shows the average distance between landlords’ homes and their investments was 1,502km in the year to November 2023. Prior to the pandemic, that average distance was just 294km.

Western Australia provides an example of this trend, and is one of the hottest markets among out-of-area investors today. This follows a 15.6 percent lift in Perth’s median house price to $691,100 in 2023 – the highest capital gain of any capital city – along with an 8.2 percent increase in regional house values to a median $477,690 – the third highest gain among Australia’s regions, according to CoreLogic figures.

“WA and Perth have caught the eye of Eastern States investors,” said Joe White, president of the Real Estate Institute of Western Australia (REIWA). “They’re drawn by the value our market offers. Despite increases over the past few years, our property prices are much more affordable than the east coast and we’ve had significant rent price growth. This means properties have the potential for very good yields.”

Total returns including capital growth and rent on investment houses reached a staggering 20.8 percent in Perth last year, and 14.5 percent in regional areas, according to CoreLogic data.

Why Americans Are So Down on a Strong Economy

Clayton Wiles, a truck driver in North Carolina, earns about 20% more than three years ago. Kristine Funck, a nurse in Ohio, has won steady pay raises, built retirement savings and owns her home. Alfredo Arguello, who opened a restaurant outside Nashville when the pandemic hit, now owns a second one and employs close to 50 people. But ask any of them about the state of the American economy, and the same gloominess surfaces. “Unstable” is how Arguello describes it.

Said Funck: “Even though I’m OK right now, there’s a sense it could all go away in a second.”

There’s a striking disconnect between the widely shared pessimism among Americans and measures that show the economy is actually robust. Consumers are spending briskly —behaviour that suggests optimism, not retrenchment. Inflation has tempered . Unemployment has been below 4% for 24 straight months, the longest such stretch since the 1960s. The disconnect has puzzled economists, investors and business owners. But press Americans harder, and the immediate economy emerges as only one factor in the gloomy outlook.

Americans feel sour about the economy, many say, because their long-term financial security feels fragile and vulnerable to wide-ranging social and political threats. Reliable steps up the economic ladder, such as a college degree, no longer look like a good investment. War overseas, and an emboldened set of hostile nations, have made the world feel dangerous. Uninspiring leaders at home, running a government widely seen as dysfunctional, have left people without hope that America is up to the challenge of fixing its problems. The broad reasons for America’s dim outlook suggest that even further improvement in the economy might not be enough to lift the nation’s mood.

In an election year, that is shaping up as one of President Biden’s biggest impediments to winning a second term. He has received little credit so far for an economy that has foiled predictions of a recession and instead grew 3.1% in the past year, far ahead of the pace in 2022. By some metrics, that improvement is starting to give way to slightly rosier views of the economy. Consumer sentiment, as measured by the University of Michigan, recently posted the biggest two-month increase since 1991 . Yet it remains about 20% lower than during the robust economy of early 2020, just before the Covid-19 pandemic started, and it stands at about levels typically seen at the end of a recession rather than in an economy posting solid growth. Interviews with Americans across the country—some affluent, some just scraping by; some with advanced degrees and others with blue-collar jobs; some Republican, some Democrat—show they are weighed down by fears of an unpredictable world in which no one in government or business is competent to steer the nation through precarious times.

“You could argue unemployment is 3.7%, but who cares with this level of uncertainty?” said Arguello. “Because that’s what people are feeling. They’re not feeling hope. They’re not feeling one country. They’re feeling a divisive, divided United States of America.”

No ‘coherent plan’

Theresa Foster estimates her family’s net worth is up because the value of their home in suburban Albany, N.Y., has risen around 20% since the pandemic started.

“But every time I go to the store I am shocked by the prices,” said Foster, who earns more than $200,000 combined with her husband’s income. “I feel like we’re on really thin ice, that it’s really fragile, that neither political party has any theoretical foundation for what they want to do with the economy.”

Foster, 57, earned a master’s degree on GI Bill benefits and works part time at a nonprofit, while her husband works full time in human resources. To her, the notion that cooling inflation should ease her financial worries is akin to telling a person who is bleeding out that the flow of blood has slowed.  What upsets her, she said, is that the government continues to spend money while racking up blunders, such as the botched withdrawal of U.S. forces from Afghanistan. None of that instills confidence in leaders’ ability to handle other complex issues.

“I feel like no matter what they tell me about the economy, they don’t really know, because they don’t have a coherent plan,” she said.  The coming election has left her dispirited about the likely nominees, President Biden and Donald Trump , whom she calls “Loser 1 and Loser 2.” Foster voted libertarian in the last two presidential elections in protest and was registered independent until she recently registered as a Republican to vote against Trump in New York’s presidential primary in April. Funck, the nurse in Milford, Ohio, said she sees the country’s decline in the high number of uninsured and unhoused patients whom she cares for at a large Cincinnati medical centre. “

The politicians seem to be making out really good and then everybody else is struggling,” said Funck, who is 52 and an independent voter who backed Biden in 2020. She earns about $90,000 a year, had her student loans forgiven after two decades, and has no children to support. Still, she constantly fears she’ll be derailed by an unexpected expense, and worries that the wars in Gaza and Ukraine could push up the prices of oil and grain.  After her mortgage and car payments, groceries and utility bills, there’s very little left over, she said. She’s prioritised saving for retirement “because I’m not expecting Social Security to be around, and I have to be able to support myself.”

Economic cracks

While many groups of Americans have made gains during the pandemic recovery, some cracks have emerged.  Americans in lower-paying industries saw some of the strongest pay raises in recent years, but wage growth is now slowing overall, and more so for these workers . Research from the Federal Reserve Bank of Dallas found that low-income households disproportionately bear the brunt of inflation , in part because of the high share of their income that goes toward food, gas and rent.  While inflation has cooled substantially from its peak in 2022, wage growth only began to outpace price increases in mid-2023 , meaning many Americans are still reeling from a long stretch in which it felt like their earnings couldn’t go far enough. The unemployment rate remains at near-record lows, but layoffs have hit some sectors of the economy with force, including technology and some other white-collar fields, such as accounting and media.

James Welch, a married father of two, moved his family from Atlanta to Plano, Texas, to take a job as a manager at an online fitness company after he was laid off early in the pandemic from a hotel company. Last July, he was laid off again. Welch, 49, said he’s depleted close to $450,000 in retirement and emergency savings in recent years to fund the move, medical expenses and costs for two children in college. His wife’s salary of roughly $72,000 annually as an operations manager is keeping the family afloat.  Welch said he thinks he was the victim of cost-cutting moves at the company. He said shortly after he was laid off, he saw his job reposted for lower pay.

Mood mismatch

To many economists, the negative outlook doesn’t reflect the current economic life of most Americans.

“There’s some justification for some negativity about the economy, but nothing resembling the amount of negativity seen in some of the survey data,” said Jason Furman , a top economic adviser to President Barack Obama . Furman said that, historically, inflation and unemployment levels have been predictors of consumer sentiment, and that the recent spate of rising prices had unsettled consumers. “It’s just not a good enough reason for them to be as down on the economy as they say they are,” he said.

Many Americans point to structural changes in the economy that have left them anxious about the future. The decline of company pensions has shifted more of the risk of funding retirement from employers to workers. And many who once thought they could count on a college degree as a ticket into the middle class now question its value.  Amy Bos, 44, a married mother of three in Jackson, Mich., said she wouldn’t necessarily recommend college for her 18-year-old daughter. Bos herself returned to college in her 30s to help her upgrade from a job as a pharmacy technician to higher-paying work in human resources, which roughly doubled her pay to $30 an hour. But she said she sacrificed immensely to pay off $41,000 in student loans, which she did only recently.

“A lot of people go to college and either don’t work in their degree field or get a lot of debt for a job that doesn’t have the ability to make very much money,” Bos said.

Some 78% of Americans said they aren’t confident their children’s lives will be better than their own, a Journal-NORC survey found last year. That’s a record in surveys dating to 1990. Only 36% said the American dream— the idea that anyone can get ahead with hard work —still holds true, down from 53% who had said so about a decade earlier, another Journal-NORC poll found. In Wilmington, N.C., the Wiles family feels like they’re sliding backward financially despite pay raises and frugal habits.  Clayton, 44 years old, makes $10,000 more than he did three years ago in his job as a tow-truck driver, bringing the family’s annual income to $58,000. But the Wiles can’t afford to fix their broken-down truck and plan to draw from modest retirement savings to pay for health insurance for their two children when they lose Medicaid eligibility this year.

Haleigh, 30, is in school to become a teacher, but worries that even the addition of an extra salary won’t enable them to start saving for a down payment on a house.  The combination of higher borrowing costs and higher home prices has made buying a home much less affordable. New 30-year fixed-rate mortgages, though down about a percentage point from last fall, are close to 7%, compared with under 3% three years ago. The increase in rates means a borrower typically has to pay hundreds of dollars more a month for a house that costs the same.

“I don’t think the American dream still exists,’’ said Haleigh. “I don’t think it’s attainable anymore. Because you need money to make money, and I think you either start out ahead or you’re constantly playing catch-up now.”

Political skew

One factor in the downbeat outlook is that many Americans view the economy through a political lens. Their opinion is more optimistic when the party of their choice holds the White House. In the weeks before the 2016 election, only 11% of Republicans rated the economy as excellent or good, CNBC polling found. That jumped to 26% right after the election, even before Donald Trump was sworn in as president, and rose to 73% within a year. By contrast, Democratic views of the economy turned more negative over the same period.

Some analysts find signs that the partisan skew in views of the economy is particularly powerful now, with Biden in the White House, because Republicans are more likely than Democrats to adopt a negative view when their party is out of power.

“We find that Republicans cheer louder when their party is in control and boo louder when their party is out of control,’’ wrote Stanford University economics professor Neale Mahoney, who held White House positions under Biden and Obama, and Ryan Cummings, a Ph.D. student, in a November Substack posting. By statistically “adjusting the decibel level’’ so that the two parties cheer equally, they found that about 30% of the gap between consumer sentiment and what would be predicted by the economic data could be explained by what they called “asymmetric amplification” of consumer sentiment according to a person’s political party.

In a complementary study, two Brookings Institution analysts found that news about the economy reported in legacy news media—big-city papers such as the Atlanta Journal-Constitution, the Washington Post and The Wall Street Journal—has been more negative than what would be predicted by actual measures of the economy. The San Francisco Fed’s index of daily news sentiment, which measures the positive or negative outlook of economic stories in news publications, had correlated well for several decades with measures of unemployment, gross domestic product, inflation and stock prices, according to research by Ben Harris, who was the top economist in the Biden administration’s Treasury Department, and Aaron Sojourner.

But in 2018, news sentiment turned more negative than the economic fundamentals, and the negativity gap has widened during the Biden administration. The study didn’t include broadcast media, such as Fox News or MSNBC, that are widely seen as tilted toward one party or the other. Nor did it prove that negative news caused lower consumer sentiment. Michael Strain , director of economic policy studies at the right-leaning American Enterprise Institute, said that the economy as people experience it in their daily lives explains most of the disconnect. While he sees some mismatch between sentiment and economic fundamentals, he believes that the corrosive impact of inflation accounts for much of it given its broad reach and because people became accustomed to very small price increases in recent years.

“When people say they don’t feel good about the economy, we should believe them,” Strain said.

‘Dark clouds’

Arguello, the Nashville-area restaurant owner, got into the food-service industry in May 2020, early in the pandemic. After ending a 30-year career at General Electric , where he was most recently a senior executive, the 65-year-old decided to buy and operate a burger franchise with his son, a recent college graduate, as a way to teach him how to run a business while deepening his own roots in his community after years of travel.

The Mooyah burger franchise they opened was successful enough that they opened a second location. Fourth-quarter revenues in 2023 were 15% higher than in the prior year, Arguello said. Despite his personal success, Arguello said he believes that “the light at the end of the tunnel is not there yet” for a nation emerging from the pandemic and its high-inflation trauma. Many other nearby restaurants have recently closed, he said, and more broadly, he’s concerned that America is suffering because political leaders are putting their party’s needs above the country’s.

“You have this political instability, a world that is very unstable, with this economic uncertainty,’’ said Arguello, who is originally from Nicaragua. He considers himself right-of-centre politically and would vote reluctantly for Trump this year if he is the GOP nominee. “What people are sensing is not whether the inflation is becoming moderate,” he said. “It’s that the dark clouds remain.”

How to Handle Making More—or Less—Money Than Your Friends

Over the past year, I’ve watched as one friend lost a job, another scored a life-changing bonus, two took huge pay cuts and yet another sold a home at a large profit. As for me, my financial life sort of stayed the same. But what did all this mean for my friendships?  An individual change in someone’s financial situation can have ripple effects throughout our greater social groups and wider peer networks, researchers and therapists say. One person’s financial loss and another’s sudden windfall can affect the ways in which we stay connected with our friends, and fights about money can lead to personal money problems or even friend breakups.

“The perception is ‘Oh, we’re on the same path,’ and as you get older, that’s not the case,” says Blake Blankenbecler , a financial therapist and friendship educator. “There is space to talk about it with your friends. But can it be cringy to talk about? Yes. Is it important to talk about? Yes.”

Humans typically gravitate toward people who are similar to us in some way, and we cling to that sense of similarity as the friendship grows and changes, says Rebecca Adams , professor of social work at the University of North Carolina-Greensboro. Individual privileges like family money, inherited wealth and more don’t always mean that perception is accurate, of course; but at the onset of a friendship, this sameness breeds closeness.

A growing divide

When we meet in college (as I met the folks now making up one of my oldest and dearest friend groups) or deskside at a job (how I bonded with two of my newer besties) we perceive ourselves to be on equal financial footing with the people we hold close. We chased down bargain-store deals and planned ad hoc dinner parties of rent-week leftovers. During an internship in New York, my best friend and I crammed together in the world’s tiniest sublet, subsisting off Trader Joe’s coupons and our dreams for the future.  But more than a decade removed from those days, our financial lives have branched in all sorts of different directions. As we grow—or not—in our respective careers, these gaps in income and wealth will only widen, says Rhaina Cohen , a podcast producer and author of the coming book on friendship, “The Other Significant Others.” But we’re also loathe to change our behaviour or discuss how these individual ups and downs will affect the glue holding the friend group together.

“In my early mid-20s, people were pretty open about what they could and couldn’t afford, and things being expensive, but I think as people have risen up the career ladder, there is less conversation about that,” Cohen says. “The awkwardness of acknowledging that people are in really different places keeps people from having those conversations. But as we get older, these divides are more likely to crop up.”

Opening up the conversation

More often than not, the friend who’s suffered a financial setback feels the burden of communicating their new needs to the group—but doing so can be much, much harder to put in practice.  Ashley Appelman , a 36-year-old living in Washington, D.C., took a significant pay cut after making a big career transition a few years back. At the time, her social calendar stayed packed with numerous friends’ weddings and bachelorette parties. Rather than bow out of these commitments or suggest cheaper alternatives, she decided that putting flights on her credit card and forgoing her savings goals was worth avoiding awkward conversations and pitiful glances.

“You don’t want to disappoint people,” she says. “I have given into so many things where I didn’t really have the budget, and I just did it.”

In her four decades of financial advising, Eileen Freiburger , managing director of the Garrett Planning Network, says she has often seen people’s behaviour change after a big money move in either direction. The friend in a lower-paying job finds themselves spending far outside their means, or the pal with more in the bank feels guilty after picking the expensive restaurant for dinner.

“Who you surround yourself with and your own value system will actively impact the next stages of how you handle your money,” Freiburger says. “Are you picking up those tabs because suddenly you can? Are you trying to spend with the Joneses?”

From her perspective, she has seen immense value in holding on to people who can ground you in your original values system, the rules you lived by before these “life happens” moments rocked your financial life. Sometimes, these people are the old friends from before; other times, they’re new friends you make after.

Finding the path forward

Financial advisers and friendship educators agree: Whichever side of the financial divide you now find yourself, the way forward for many true friendships is having more open, honest conversations about money and how it affects our relationships.  These don’t have to be scary or stilted discussions, Cohen says, and they don’t have to happen in overtly formal, intimidating settings.

She recommends using a real-life example to open up a bigger conversation. For instance, if you’re buying tickets to an event, ask your friend how much money they plan to spend and why. That, in turn, can kick off a much deeper conversation about your relative finances. Cohen recommends a thoughtful line that struck me as especially empathetic and easy: “What would be helpful from me to make sure we’re on the same page about what we do together and how we spend money?’”

“There is so much that goes unsaid in friendship,” she says. “What I would want people to do is talk, to have open conversations with their friends about big transitions and big differences.”

Personally, I’ve been the friend in both positions: the richer friend and the definitely-not-rich one.  I recently passed on a luxe vacation with one set of dear friends. I agonised over the decision, fantasising about suddenly finding a great flight deal or stumbling upon a can’t-miss hotel deal. After enough hours staring at travel booking sites, though, I knew my budget just couldn’t stomach it. And even though my friends understood—and of course they did! They’re good friends for a reason!—I had to hype myself up to send the “Hey guys, I’ve been thinking about our trip…” text.

Admitting I had to back out felt like a tiny failure, like I wasn’t as committed to the friendship as I had been in years past.  But when another pal recently took a large pay cut as she pursued a more demanding—and lower-paying—career, I found myself on the other side of the table. After a handful of conversations about her reduced salary and inflexible schedule, I remembered my own struggle to send that text. I took the initiative to bring up the new discrepancy, suggesting we move our usual dinner-and-drinks hangouts to a lower-key TV night in.  Six months later, I have to say: Both of our budgets are happier for it.

The state leading Australia economically for the first time

South Australia is leading the country economically, with a population surge post-COVID boosting economic demand, lowering unemployment and creating a property market boom. Amid a national housing undersupply crisis, South Australia has the best rate of new home building activity and house prices have risen 10 percent in Adelaide and 9 percent in regional South Australia over the past 12 months.

CommSec’s quarterly State of the States report compares the states and territories on eight economic measures: economic growth, retail spending, equipment investment, unemployment, construction, population growth, housing finance and dwelling commencements. The report compares each measure against the long-term trends for each state and territory to determine the out performers.

According to the latest report, South Australia is the best-performing economy and comes out on top in four categories — economic growth, unemployment, construction work and dwelling starts.

The states and territories were ranked in the following order:

• South Australia
• NSW and Victoria (equal second)
• Western Australia
• Tasmania
• ACT
• Queensland
• Northern Territory

CommSec chief economist Craig James said this is the first time in the 15-year history of the report that South Australia has emerged as Australia’s leading state economy.

“Population growth in South Australia has tripled over the past two years, which is showing up in a strong housing market and overall economic activity,” Mr James said. He commented that Australia’s resilient jobs market and strong population growth are underpinning all state and territory economies, however high interest rates and the cost-of-living crisis have led to a slower pace of economic growth in all of them.

Economic activity in South Australia in the September quarter was 9 percent above its four-year average level of output. NSW was in second spot at 8.3 percent above its four-year average. Trend unemployment in South Australia was 3.8 percent in December, which was 36.5 percent below the state’s decade-average. Tasmania ranked second at 3.9 percent, 32.8 percent below its norm.

South Australia ranked first for construction work, based on the total real value of residential, commercial and engineering work completed in trend terms in the September quarter. South Australia completed just over $4 billion of construction during the period, which was 23.4 percent above its decade average, ahead of NSW with $19.7 billion of work, 18.3 percent above its average.

South Australia is also building new homes at a more rapid rate than any other state or territory. In the September quarter, South Australia booked 2,852 dwelling starts, which was just 2.3 percent below its decade average. Tasmania was second with 703 starts, 3.2 percent below its average. Dwelling starts in the two most populous states in Australia were woefully below their decade averages. In NSW, 10,536 starts were recorded, down 28.8 percent on the decade average. In Victoria, there were 12,666 starts, down 20.7 percent on normal trends.

The downside to South Australia’s economic growth has been a greater rate of inflation. Adelaide recorded the highest annual inflation rate in the September quarter at 5.9 percent, ahead of Perth at 5.8 percent. But this was only slightly above the national inflation rate of 5.4 percent. Last week, the Australian Bureau of Statistics released the December quarter national inflation figures, which revealed a substantial fall from 5.4 percent to 4.1 percent. This was among the reasons that the Reserve Bank kept interest rates on hold after its first meeting of the new year this week.

I Said Yes to Every Upgrade in Las Vegas. Here’s What It Cost.

LAS VEGAS—Few places vacuum money from you like this glittering gambling and entertainment playground.  That’s true for the visitors in town for Sunday’s Super Bowl —official motto: Excessive Celebration Encouraged. And it’s true for visitors any time, with the $US200 seats at the pool and the $US800 bottle service at nightclubs. All before you step onto the casino floor.  You can fly here for as little as $US50 if you play your cards right. But people come to Vegas to spend, and the businesses here know it. This place hits travellers with potential upgrades every few steps. So I flew in for an experiment, a real-life version of the Jim Carrey comedy “Yes Man” (or “Yes Day” if you’re a Jennifer Garner fan). I said yes to every upgrade and VIP package to see just how much you get for your money, and what can be skipped. I had parameters. The $US3,999 helicopter ride to the top of Valley of Fire State Park for yoga was out. As was the $US4,000-a-night upgrade offer to a three-bedroom presidential suite at my hotel.  Still, I cut lines, got a massage in the reserved seats at the Aria sportsbook during an NFL wild-card game, relaxed in a private lounge before a show at the Sphere , and drank a French 75 from a prime window seat at the Eiffel Tower Restaurant. In all, I spent $US976 to upgrade my Vegas visit.  Was every upcharge worth it? Absolutely not. But a few are worth your money.

Yes, yes and yes

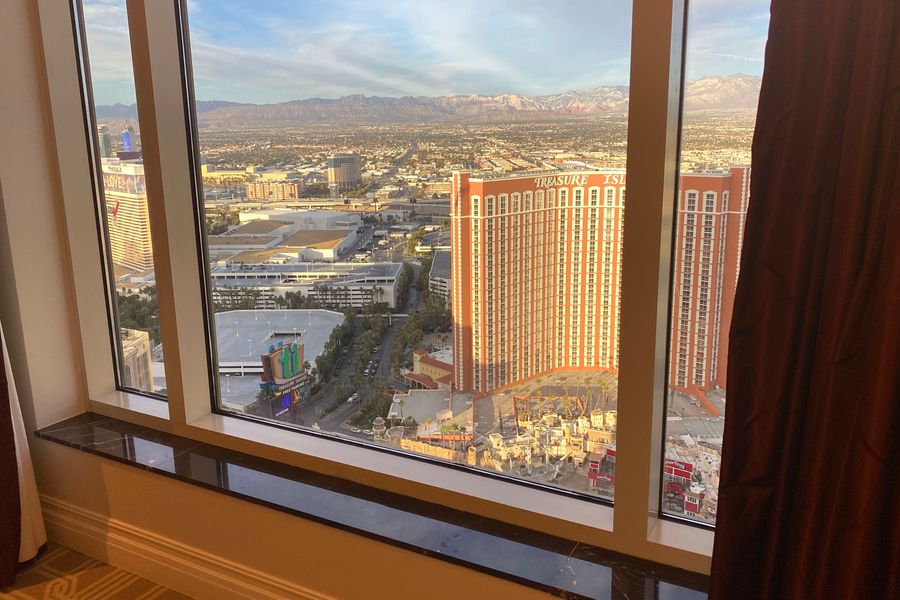
The offers began minutes after I booked a room for two nights at the luxury all-suite Palazzo resort. The price: $US480 before taxes and fees for two nights, a relative bargain on a holiday weekend in January. How much for a room booked last-minute for Super Bowl weekend? $US1,700 a night. I landed two upgrades after an email prompt gauged my interest: $US75 for early check-in and $US57 a night for a city view, the cheapest room category upgrade. Early check-in fees irk me , but this was worth it after my early flight. I was in the room by 11 a.m.  The room was swank. The view of Treasure Island and the Mirage was nothing special.

A city view room at the Palazzo resort, where travel columnist Dawn Gilbertson paid an extra $57 a night plus taxes to upgrade the view. PHOTO: DAWN GILBERTSON/THE WALL STREET JOURNAL

I headed to Area15, an arts and entertainment complex. First stop: Meow Wolf ’s Omega Mart, a popular immersive art experience that takes visitors into a bizarro grocery store that links to an alternate dimension. Admission is $US54; upgrading to a $US99 VIP package promised to “enhance my experience”   but bought me a souvenir pin, VIP lanyard, a cocktail and a 15% discount I didn’t use at the gift shop. Maybe the good stuff comes with the $US129 scavenger hunt package. (As I perused products like cans of faux La Croix in mashed-potato flavour and wandered a dizzying hall of mirrors, I wondered how many visitors upgraded with a trip to a local dispensary beforehand.) Admission to stroll around the rest of Area15 is free, but I upgraded to a $US35 pass, which included five attractions, the best of which was the outdoor Liftoff ride with great views of the Strip.

Cutting lines for crab legs

Many resorts here gave up the buffet business for good during the pandemic . The Wicked Spoon buffet at the Cosmopolitan of Las Vegas still packs them in. Saturday brunch had an hourlong wait during my visit. VIP line to the rescue! $US35 gets you a head start on the $US62 all-you-can-eat feast of snow crab legs, sushi and slow-roasted strip loin. The best part: The manager overseeing the line comped the fee because she said she enjoyed talking to me and a friend while we waited. (I never identify myself to employees as a Wall Street Journal reporter on these types of assignments.) Suddenly playing with house money, I sprang for the unlimited mimosa package for $US33 after tax and tip, to go with the brunch base price. There is a 90-minute limit, but I had places to be.

One movie, $US245

My colleague Jason Gay calls the Sphere, the giant orb that sits behind the Venetian, a “beach ball peaking on acid.” He paid $US539 to see U2 at the new venue.  In the biggest single splurge on my trip, I paid $US245 to see a 50-minute movie there. The Director’s Seat package promised VIP entry, pre show lounge access with free beer, wine and snacks and a souvenir Sphere T-shirt. The VIP entry was the best perk, letting me skip the clogged Regular Joe lines. I was one of the first people in the atrium, where a humanoid robot named Aura chatted with me and a couple from Arkansas who also took the VIP plunge. The robot asked them the secret to their 55-year marriage. We met again in the nearly empty lounge before the Darren Aronofsky show “Postcard From Earth.”

Delta Sky Club this ain’t: The small food spread included soft pretzels with cheese and mustard. The bartender did dig out a great local IPA, Atomic Duck, and pointed me to the popcorn that VIP guests could take into the movie. The package promises premium seating for the show, a trip around the globe in which seats rattled when elephants or a jumbo jet rumbled across the giant screen. My seat was good, albeit one row up and an aisle over from my friends who paid $US79 for their standard tickets.  The final Yes Day in Vegas is a spendy blur: $US190 to watch the Lions and Rams duke it out in an NFL playoff nail-biter from a high-top table with food and alcohol included in a roped-off section at Aria Resort & Casino. The rest of the sportsbook was standing room only. Then there was the $US40-a-person fee for the window seat at the Eiffel Tower Restaurant overlooking the dancing Bellagio fountains. The couple celebrating their anniversary one table back couldn’t believe I paid the fee.  I left Vegas a little spoiled and out of sorts. When Southwest Airlines offered a $US50 upgrade to jump to the front of its boarding line on my flight home, I clicked buy. Can’t wait to explain that one to the folks in Expense Accounting.

Luxury Rents Around the World Rose Faster Than Sales Prices 2023

Luxury residential rents remained strong globally in 2023, outperforming capital values in 28 of the 30 cities tracked in the Savills World Cities Index, according to a report from the British real estate company on Wednesday.  On average, luxury rents increased by 5.1% last year, compared to the average home price growth of 2.2%. “In the face of economic uncertainty, the prime residential rental market proved resilient in 2023,” said Kelcie Sellers, associate at Savills World Research.

“Continuing a trend from the past year, prime rental value growth outpaced capital values, largely driven by a lack of stock in global prime markets and increased levels of demand from individuals and families who would look to purchase a property, but are holding off until the economic and interest rate situations stabilise.”

Lisbon was by far the leader in rental growth, with luxury rents increasing by an average of 39% over the year and by 22% in just the second half of 2023, according to the report.

“Lisbon has seen an influx of people moving to the city, attracted to its climate, the quality of life on offer and strong business environment. But some have been more reluctant to enter the purchase market in Lisbon due to rising house prices and increasing interest rates,” Sellers said. “While the supply of houses in the rental market has not kept pace with demand, leading to a rise in rental prices throughout Portugal, it remains comparatively priced compared to other rental markets in Europe and will likely continue to attract new renters and investors over the coming year.”

Singapore led the Asia-Pacific region, with its rental growth at 12.3%, though that was down from 32.3% in 2022. Hong Kong also saw luxury rents increase, jumping by 5.9%, as high deposit requirements, increased interest rates and an influx of buyers from Mainland China drove would-be buyers to the rental market, according to Savills.

As for the year ahead, a slight increase in luxury rents is expected across the 30 global cities, though the price growth may be less than usual.

“Looking at the year ahead, prime rental prices are forecast to record a slight increase for the 30 cities covered in the World Cities index, as would-be prime buyers continue to turn to rental markets, but this growth will likely remain below the historic average,” Sellers said.  Savills predicts that Amsterdam will lead this year’s rental growth index, with a forecasted increase of 6% to 7.9%, as the city has seen a spike in demand in tandem with limited supply and increased regulations on the private rented sector.

Why London’s Wealthy Are Renting Instead of Buying

With London luxury real-estate prices on the slide and a collapse in high-end deal volume, it has been a tough year for prime central London real estate.  But the prime rental market is thriving.   People in need of a London base are increasingly opting to take the flexible, minimal-commitment housing option rather than buying, and paying Britain’s high taxes, in a stalled market. As a result, prime rents are escalating. House price analyst LonRes found that average prime rents in London increased 3.5% between December 2022 and December 2023. Average prime rents are now 29% above pre pandemic levels notched during the period of 2017 to 2019.

Separate research from estate agent Beauchamp Estates found that 63 London homes were rented out for $6,370 or more per week—about $330,000 per year—between January and June 2023.  Buying agent Liam Monaghan, managing director of London Central Portfolio, said many of his prime tenants live a global, itinerant lifestyle. They include soccer players, actors and film producers and tech entrepreneurs.

“They can obviously afford to buy these properties, but perhaps they are on a short-term contract or are growing a business and have got a lot of wealth quite quickly and are jumping between lots of different countries and are still working out where they want to live,” said Monaghan. Nina McDowall, head of lettings at estate agent Strutt & Parker’s office in Knightsbridge, one of London’s most expensive neighbourhoods, said many of her renters are considering buying a London property but only when they find the perfect home at a great price. “There are a lot of people who are weighing up their options,” she said. “They might also be sitting tight to see if prices slide further.”

Others, such as Antonio Volpin, simply don’t see London property as a great investment opportunity. Volpin, who is Italian, moved to London for work in 2011, initially living out of hotels. When his wife and two sons joined him in London in 2012, the family started renting.

The Georgian exterior of a rental property in Mayfair that is renting for $37,900 per week. PHOTO: CHESTERTONS

“We mulled the idea of buying a property, because the market was very strong, but I thought it could not grow forever, and with my work I am not sure where I will be next year,” said Volpin, 61, a consultant for asset and fund management firms.

The family’s decision to continue renting proved prescient, because prime central London’s house prices have stagnated for almost a decade. According to LonRes, average sale prices in prime central London increased by just 2.3% between 2013 and 2023 (from $2,130 per square foot to $2,180 per square foot). In 2016, Volpin’s job took him to Singapore, and now he and his university professor wife are based in Rome. Their two sons, aged 26 and 22, opted to remain in London so their parents, who visit regularly, have continued to rent a three-bedroom, three-level, apartment in the affluent, historic neighbourhood of South Kensington, 2 miles west of the city centre.

Antonio Volpin has been renting in central London since 2012 and considers it a more flexible option than buying. PHOTO: OLGA PODPORINA FOR THE WALL STREET JOURNAL

Volpin has signed a nondisclosure agreement prohibiting him from revealing his monthly rental costs, but a spokeswoman for his estate agent, Winkworth, said that a similar property would cost up to $191,000 per year.

“Certainly with that money I could buy, but the point is that at the moment it is more of a kind of holiday home,” Volpin said. “When I come, I want to be close to downtown and to the friends I made while living in London.”

McDowell believes that the reason top-end rental prices have accelerated while home sale prices are falling is simple: Demand for these types of rentals is high and there is a serious undersupply of high-specification, turnkey properties.

“They are as rare as hen’s teeth,” she said. “Super-prime tenants will not sacrifice or compromise on many things. The condition and functionality of the property has to be slick and beautiful, and they will pay big prices, or pay one or two years in advance, to secure the right property.”

But while rents are rising, prime-central London landlords still have to work hard to attract high-paying tenants who expect five-star standards. “I have had people who want walls to be ripped out or massive extension work,” said Sinead Conlon, head of corporate and relocation services at John D Wood & Co. estate agents. “Some of them want interior-design furniture packages costing about $32,000 to $127,000 per month. They are all looking for an add-on.”

In one memorable case, Conlon was able to rent a substantial house in the north London suburb of Primrose Hill to a tenant who wanted the toilets in the bathrooms, 17 of them, to be replaced with Japanese models with built-in bidets. The tenant, who paid around $70,000 per month to rent the house for a year starting in 2021, eventually settled for just 10 new toilets to be fitted.

“But they are around £25,000 [$32,000] a pop, so it was not exactly cheap,” said Conlon.

Another problem facing landlords is dwindling profit margins. Interest rates have jumped and, since 2020, landlords cannot deduct mortgage interest from their tax bills, said Becky Fatemi, executive partner of Sotheby’s Realty UK. The administration of renting a property is also not cheap. Fatemi said landlords should expect to pay their estate agent between 8% and 15% of the annual rent to find and install a tenant. Management fees, if required, add another 5% to the cost.

Vickram Mirchandani currently owns and rents out two prime London properties. He is painfully aware how hard it is to turn a decent profit even in a hot rental market. Mirchandani, 46, who is British, bought a five-bedroom family home in the upscale neighbourhood of Belgravia, about 10 years ago. They lived in the home full time, but he and his wife became increasingly disillusioned with life in Britain and left London in October, then moved to Dubai with their young family in January—they have one child and are expecting a second.

Vickram Mirchandani and his wife
CREDIT:Vickram Mirchandani

Mirchandani has decided against trying to sell the property until London’s property market has revived. In October 2023, tenants moved into the 4,200-square-foot townhouse, paying just under $8,900 per month in rent.

“It was gone within a week, on the second viewing, for the asking price,” said Mirchandani, a renewable-energy developer. “In hindsight, I could probably have got a little bit more.”

Mirchandani also owns a second property, a three-bedroom penthouse in Belgravia, which he had originally hoped to flip. “The plan was to purchase it, develop it, and sell it at a handsome margin,” he said. “But after Brexit that handsome margin never materialized.” The apartment is also rented out, fetching $11,500 per month. “I actually got over asking price for that one because the tenant has a dog and I said, ‘Fine, but that will be an extra 10%,’ ” said Mirchandani. “I am very happy with the prices achieved.”

He is less happy with the yields his capital is earning. He estimates that after costs, including income tax, he is earning around 1.5% to 2%. England’s major banks are currently offering interest rates of around 4% to 5%. Longer term, Mirchandani is still weighing his options. “I could keep them in the hope that someday some miracle will happen and they will go up, but if we like it in Dubai we will probably sell the properties,” he said.