Kanebridge Property of the Week: Earlswood brings two eras together in Randwick

Alexander Phillips has unveiled his first newly launched trophy campaign since establishing Ray White Phillips & Co, with the landmark Randwick estate Earlswood being offered with a guide of $10.5 million.

The listing is an early statement for Phillips’ new Woollahra-based agency. Less than a month after opening, Ray White Phillips & Co had already secured more than $30 million across a series of booked auction campaigns, including the $9 million sale of 92 Ocean Street, Bondi, and sales in Waverley, Bronte, Clovelly, Paddington and Coogee.

Phillips also recently sold 9 Kenneth Street, Tamarama, for $20.25 million, the highest reported Eastern Beaches sale of 2026.

The latest addition to the agency’s books is one of the eastern suburbs’ more distinctive estates.

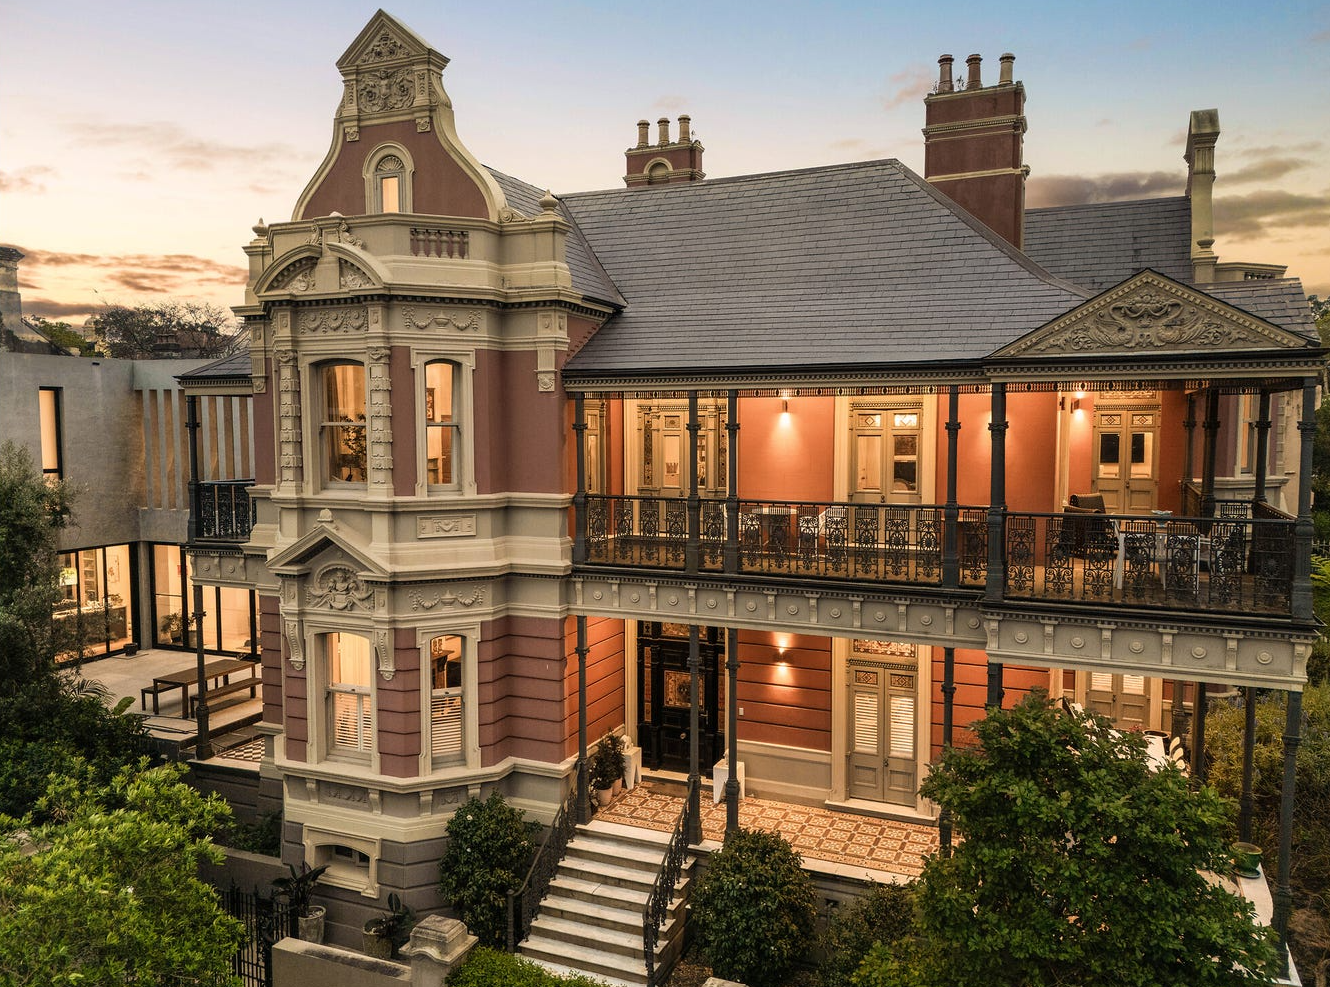
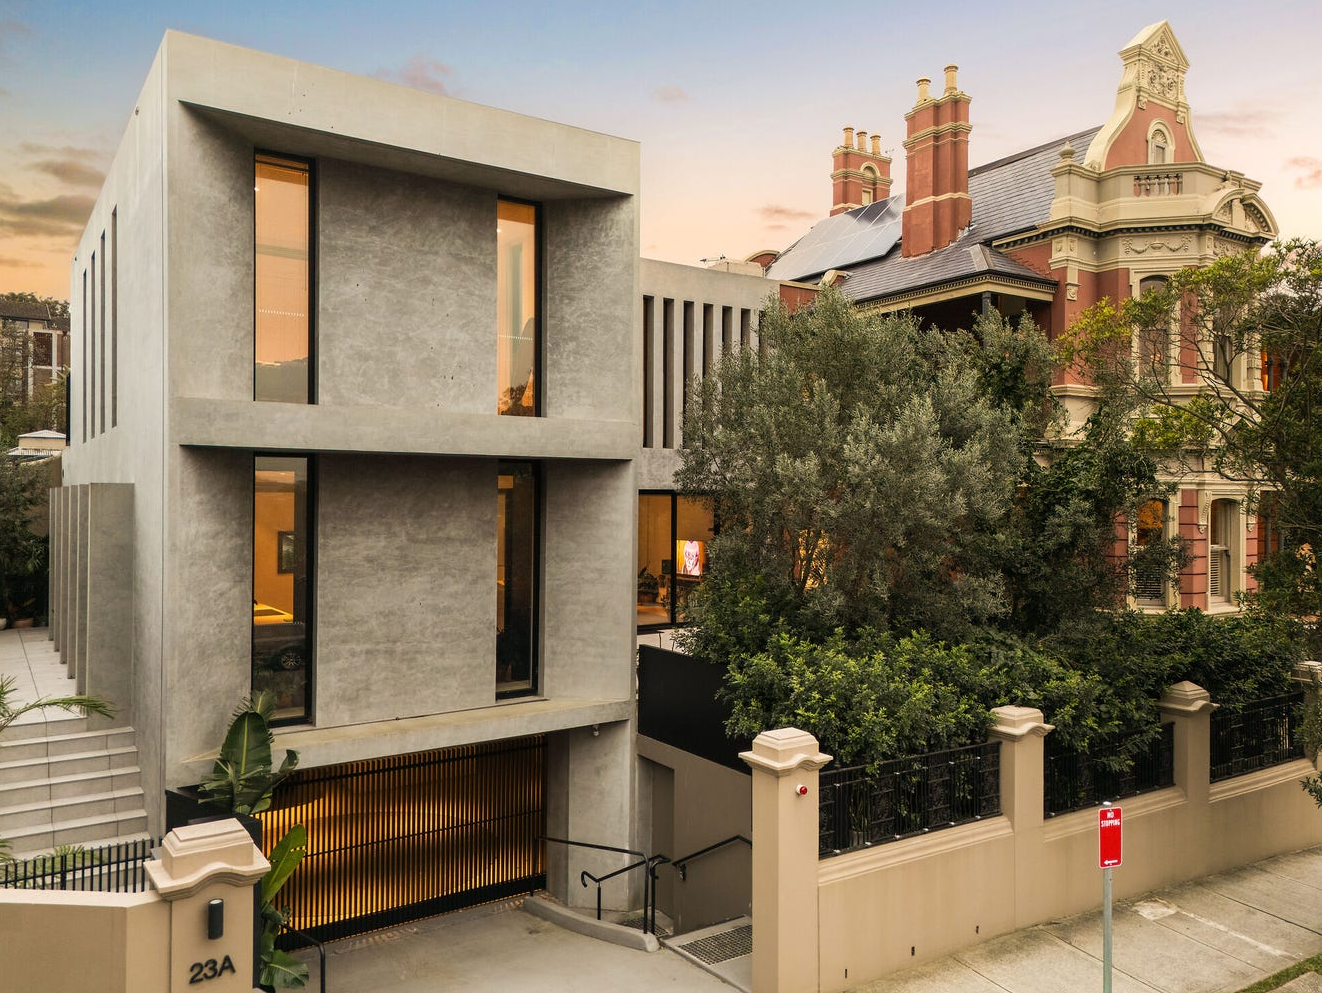
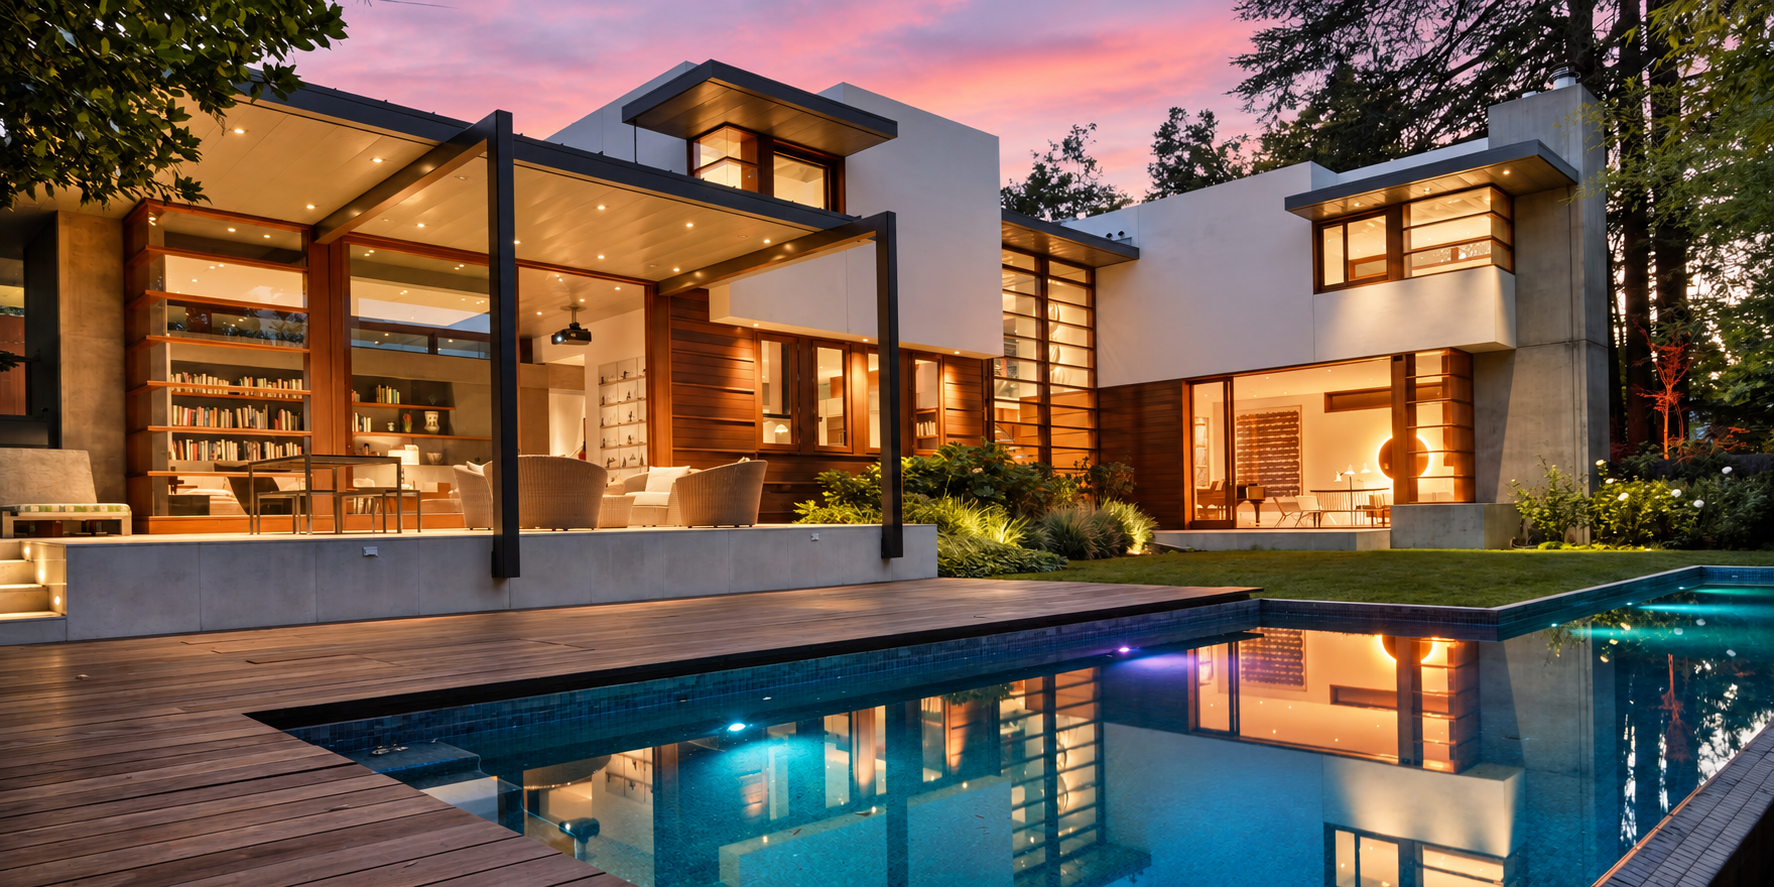
Occupying 778 sqm at 54 Dutruc Street, Earlswood pairs a restored Victorian Italianate manor with an adjoining two-storey contemporary residence designed by X-PACE Design Group.

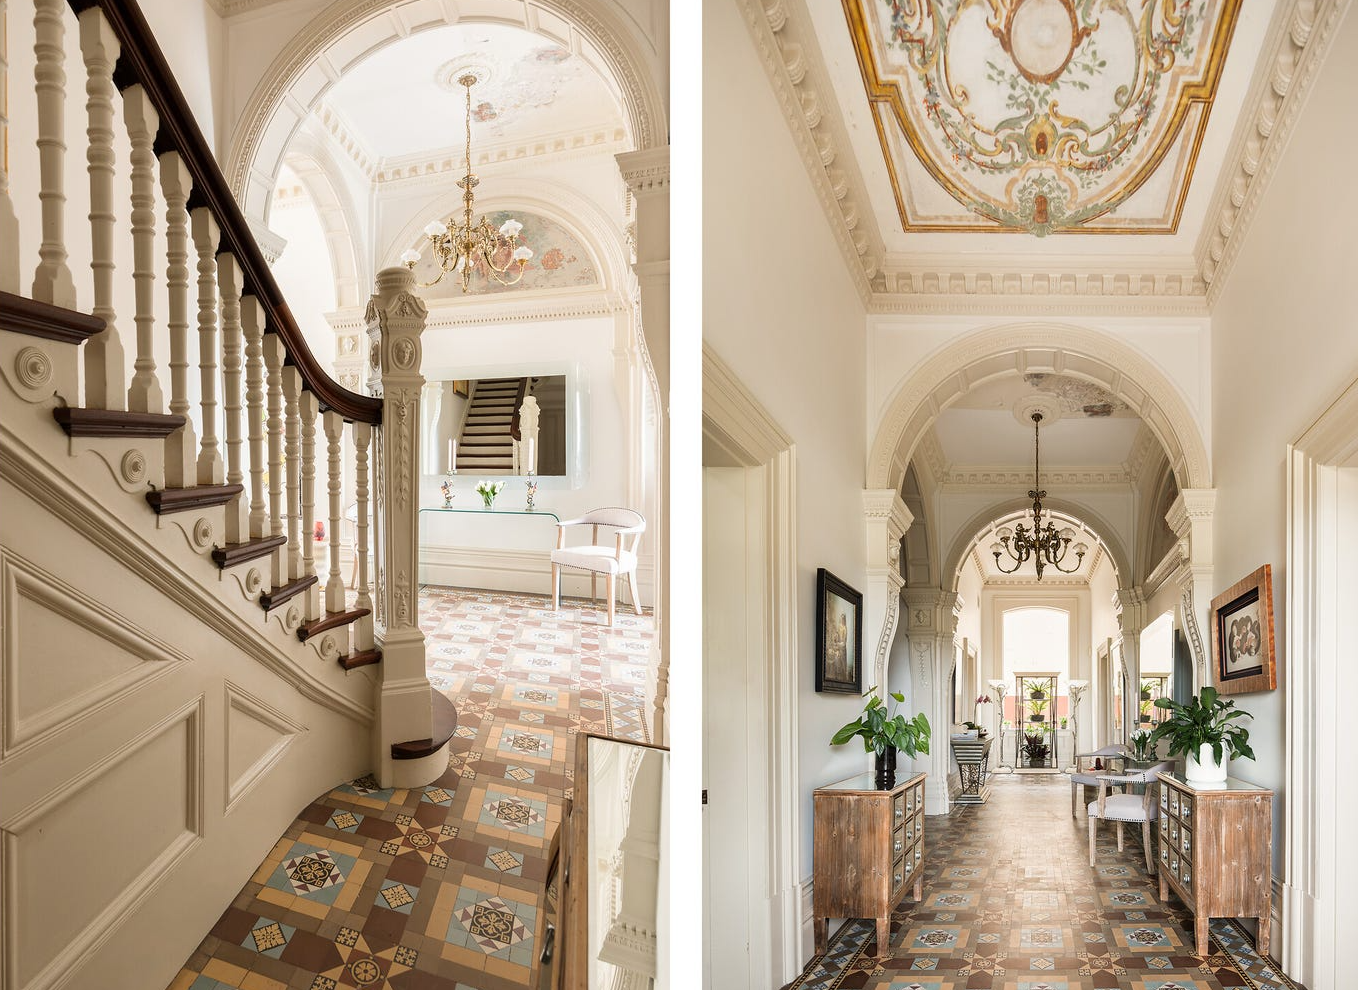
The original home was built in 1891 and is a locally listed heritage residence within Randwick’s St Marks conservation area. Its restoration retains much of the formality and detail expected of a grand Victorian property, including a substantial entrance foyer, frescoes by Augusto Lorenzini, four-metre ceilings, marble fireplaces and a series of reception and entertaining rooms.

Four king-sized bedrooms are arranged on one level, while an attic retreat captures views towards the ocean. More recent additions include a custom kitchen with Gaggenau appliances, a butler’s pantry, Spotted Gum floors and ducted air-conditioning.

Next door, the second residence takes a distinctly contemporary approach. Off-form concrete, wide oak floorboards and clean architectural lines establish a deliberate contrast with the ornate historic manor.

The modern home contains three upper-level ensuite bedrooms, two living areas, a designer kitchen, courtyard and north-facing rooftop terrace. Villeroy & Boch-appointed terrazzo bathrooms and Italian lighting continue the detailed finish found throughout the estate.

Although architecturally different, the two homes have been designed to operate together or independently. Each has its own entrance, while both connect to a four-car basement containing a vehicle turntable, wine cellar and internal lift access.

The configuration lends itself to multigenerational living, accommodation for adult children or extended family, or a principal residence with a separate income-producing home. The properties have also been prepared for possible future title subdivision, subject to council approval.

The estate spans approximately 717sqm of internal floor area and has a 39-metre frontage to Rae Street, as well as landscaped gardens and dual-street access. It last changed hands for $10.75 million in November 2023, according to publicly available property records.

Earlswood arrives as Phillips begins the next phase of a 24-year career in Sydney’s eastern suburbs. He has been ranked among Australia’s leading residential agents for more than a decade, with his team reported to transact more than $1 billion in property annually across more than 400 clients.

Phillips said his decision to launch Ray White Phillips & Co was driven by the industry’s increasing reliance on technology, data and network reach, while maintaining his team’s focus on the eastern suburbs.

For Ray White, Earlswood provides an appropriately high-profile introduction to its newest prestige operation: a rare dual-residence property that offers both a carefully preserved piece of Randwick’s history and a markedly contemporary way of living.

Earlswood at 54 Dutruc Street, Randwick, is being marketed by Alexander Phillips of Ray White Phillips & Co through expressions of interest closing November 5.

BNW joins growing wave of UAE developers targeting Australia

A growing number of major UAE property groups are turning their attention to Australia, with BNW Developments the latest to establish a local presence.

BNW has officially opened a Sydney office after hosting more than 300 investors, property professionals, wealth advisers and industry figures at its launch event.

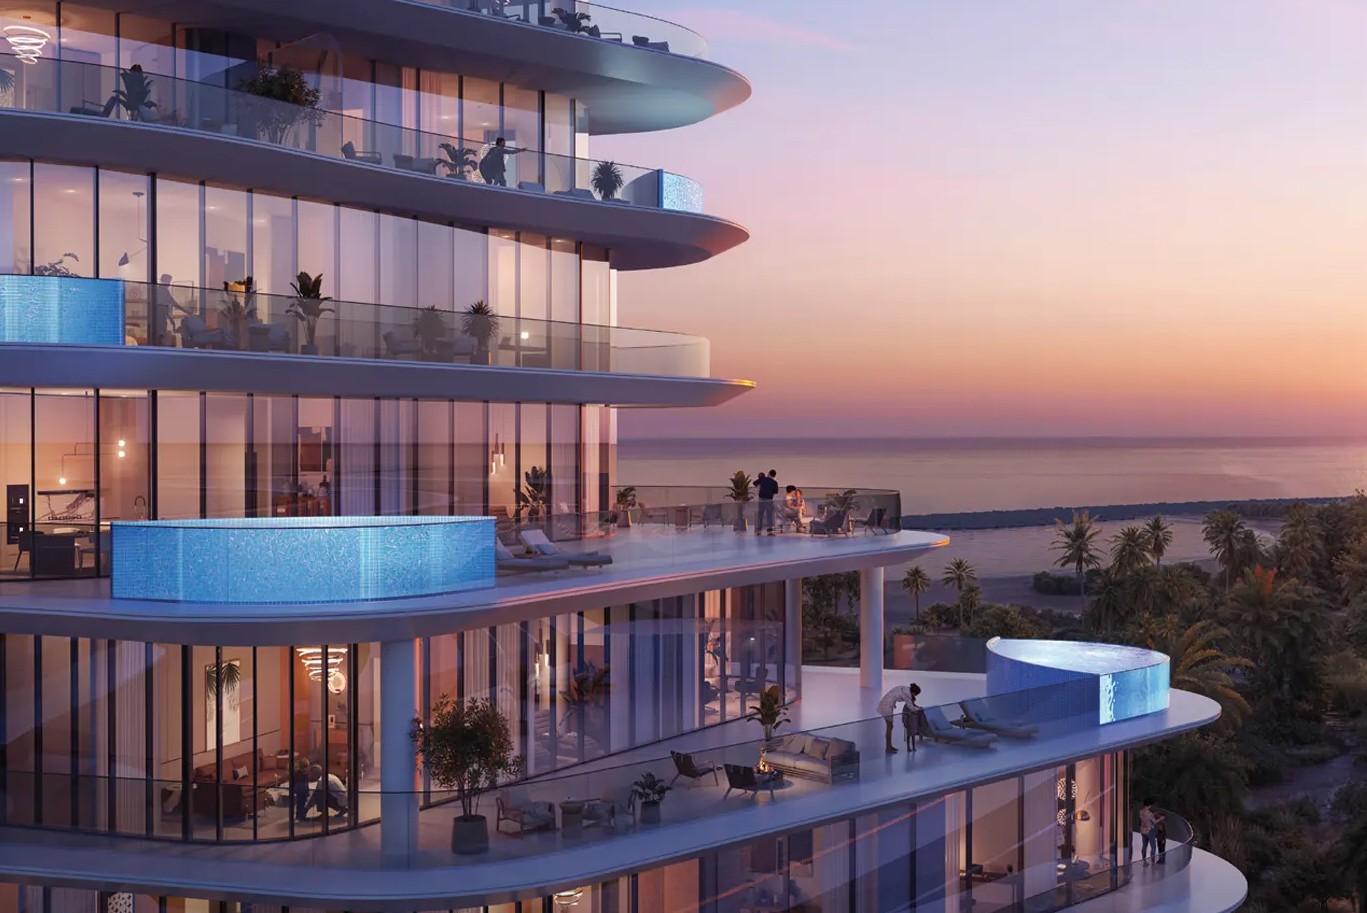
The new office will give Australian buyers local access to BNW’s portfolio of residential and hospitality-led developments in Dubai and Ras Al Khaimah. Its projects include branded residences and waterfront developments combining private homes with hospitality, dining, leisure and tourism facilities.

BNW has an AED32 billion development pipeline, equivalent to approximately $12 billion, spanning projects in Dubai and Ras Al Khaimah. Its portfolio includes developments associated with Tonino Lamborghini, Radisson Blu and Wyndham Hotels & Resorts.

Among them is Tonino Lamborghini Residences in Ras Al Khaimah. BNW is also active on Al Marjan Island, the waterfront destination where the Wynn Al Marjan Island integrated resort is under development.

The developer recently announced Dolce Residences in partnership with Wyndham Hotels & Resorts. Billed as the world’s first residences carrying the Dolce name, the boutique Al Marjan Island project is planned to include 93 premium residences and five retail tenancies.

BNW Developments chairman and founder Dr Ankur Aggarwal said attendance at the Sydney launch indicated that Australians were increasingly interested in the UAE as both a property and lifestyle destination.

“The response to the opening of our Sydney office has been extremely encouraging,” he said.

“Dubai and Ras Al Khaimah offer a very different lifestyle proposition to Australia, from waterfront living and luxury hospitality to world-class dining, entertainment and tourism.”

Dr Aggarwal said the Sydney office would allow buyers to examine BNW’s portfolio locally and work with a team familiar with the Australian market.

The move comes as Australia attracts increasing interest from UAE-based developers seeking opportunities beyond their home market.

Arada entered Australia in 2024, initially announcing a $2.5 billion Sydney pipeline expected to deliver more than 2,500 homes. Its Australian plans have since expanded to eight projects comprising more than 5,000 homes, including a recently announced twin-tower development at Broadbeach on the Gold Coast.

The company has also acquired the NSW arm of tier-one contractor Roberts Co, giving it greater control over construction and delivery as it builds its Australian business. Globally, Arada says its portfolio of existing and future developments across the UAE, Australia and the United Kingdom is valued at AED130 billion.

Dubai-headquartered Sobha Realty is also laying the foundations for a substantial Australian presence. The developer has established local operations and acquired sites in Sydney and Queensland, describing its entry as a long-term commitment to the market.

Sobha has expressed interest in opportunities across Brisbane, the Gold Coast and Sunshine Coast, while its Australian website says new projects will be announced shortly. The expansion follows AED30 billion in global sales during 2025 and forms part of a wider international growth strategy encompassing Australia and the United States.

BNW’s Sydney opening reflects both the international ambitions of UAE developers and growing Australian awareness of the Emirates’ property market.

While the UAE and Australian markets differ considerably, the arrival of BNW, Arada and Sobha points to a broader exchange of capital, expertise and buyers between the two countries. For Australians considering offshore property, the opening of local offices may also make it easier to assess projects, understand the purchasing process and undertake appropriate due diligence before committing.

Aman’s Maldives debut will dedicate an island to wellness

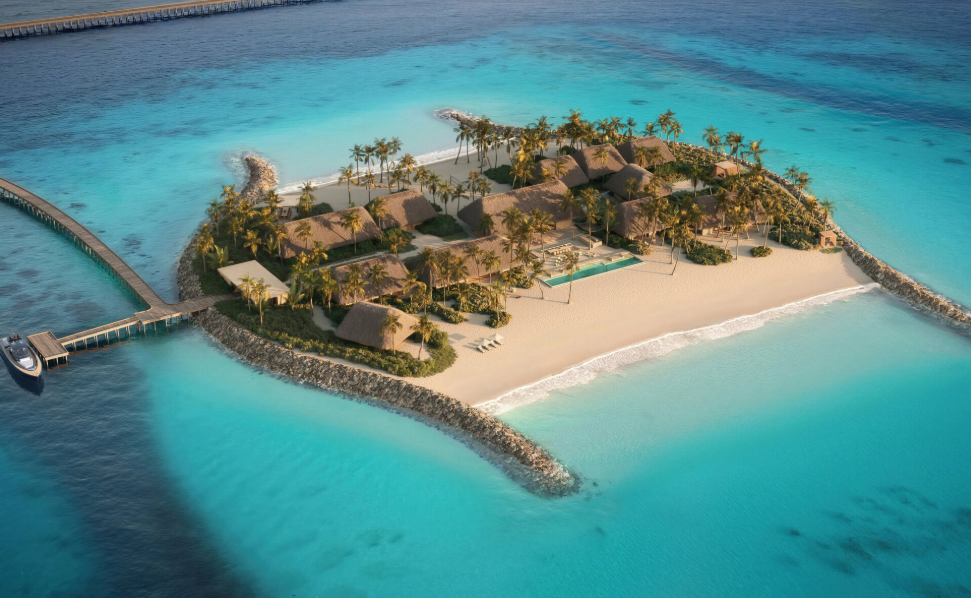
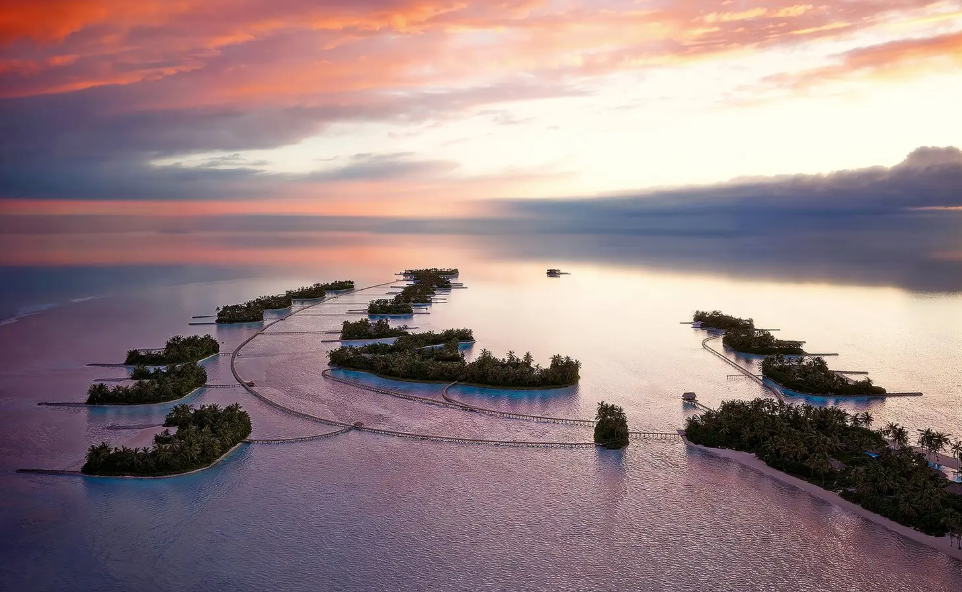
Aman has named its first Maldives destination Amanolu, setting the stage for a 2028 opening in the comparatively secluded Vaavu Atoll.

The name combines Aman—Sanskrit for peace—with “Olu”, inspired by the water lily. It is a fitting identity for a project intended to extend the brand’s restrained approach to luxury across a private-island setting.

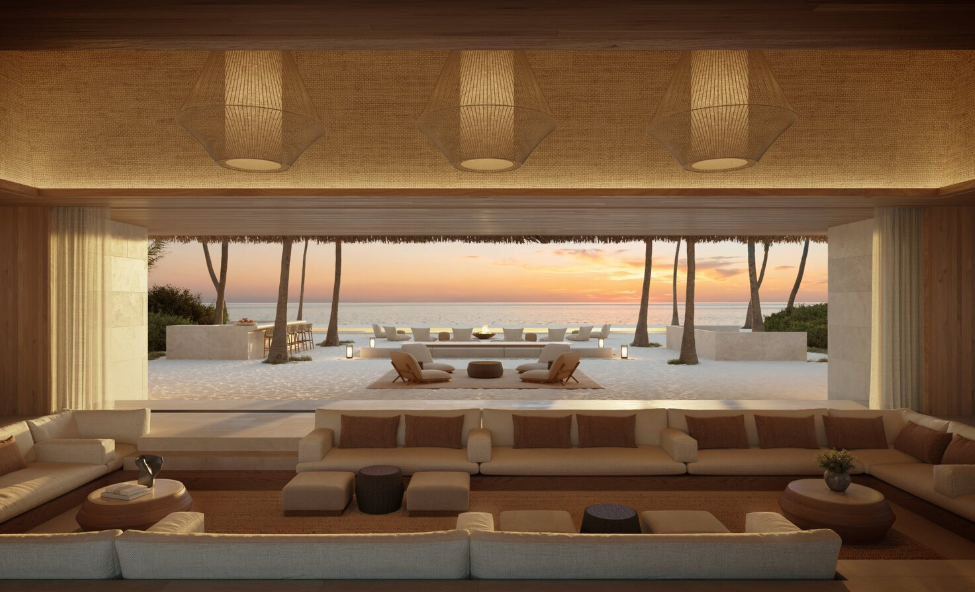
Current plans describe a 52-key resort and 16 Aman Residences. The residential proposition is extraordinary even by Maldives standards: each five-bedroom home is expected to occupy its own private island, with a 25-metre swimming pool and private jetty.

The resort is also expected to devote an entire island to wellness. That physical separation could allow treatments, movement and restoration programs to operate away from the social energy of the main resort, although the exact facilities and practitioner program should be confirmed as the opening approaches.

Vaavu Atoll offers a different context from the archipelago’s more intensively developed resort regions. Its appeal rests on marine environment, privacy and the sensation of remoteness. Access, transfer times and seasonal conditions will therefore form an important part of the guest experience.

For prospective residence owners, the romance of a private island comes with a demanding operational model. Marine infrastructure, utilities, staffing, maintenance, insurance, management fees and resale provisions require close scrutiny. Ownership structure and local legal rights should be assessed with specialist advisers.

Amanolu also enters a competitive field. The Maldives already contains some of the world’s most ambitious resorts, so novelty cannot rest on an overwater villa alone. Aman’s opportunity is to translate its signature privacy, spatial calm and service into a destination where the physical landscape is already spectacular.

With opening still two years away, design, pricing, booking dates and residence availability may change. For now, Amanolu’s most compelling promise is radical separation: fewer keys, a dedicated wellness island and residences that turn the idea of a private island from marketing language into a literal address.

Fact box

Resort: Amanolu

Location: Vaavu Atoll, Maldives

Expected opening: 2028

Resort scale: 52 keys

Residences: 16 private homes

Residence concept: Five bedrooms, 25-metre pool and private jetty; each reportedly on its own island

Wellness: Dedicated island planned

RBA lifts rates to 4.60% as inflation risks become reality

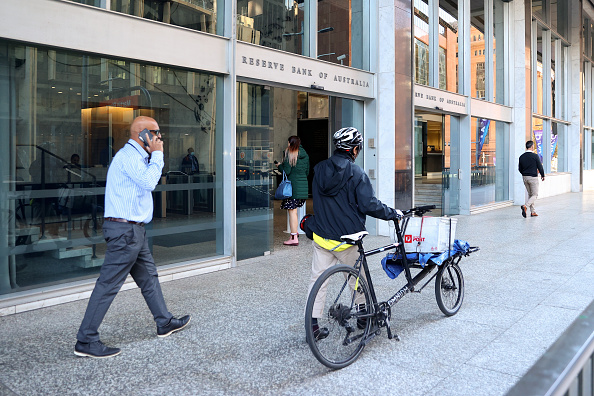
The Reserve Bank of Australia has delivered its fourth interest-rate increase of 2026, lifting the cash-rate target by 25 basis points to 4.60 per cent and warning that further tightening remains possible.

The unanimous decision on 29 September takes the cash rate to its highest level in almost 15 years. More importantly, it confirms that the RBA’s concern has shifted from inflation risks that might materialise to price pressures that are already spreading through the economy.

The increase was widely expected after a series of hawkish comments from senior RBA officials. Financial-market sentiment now remains tilted towards rates staying higher for longer, with some analysts expecting at least one further increase. Yet the decision is not straightforwardly hawkish: the economy is slowing, house prices are falling and household budgets are under mounting pressure. The RBA is tightening because inflation has proved stronger than anticipated, not because the economy is booming.

A significant change in the statement

The clearest change from the RBA’s August statement is the transition from warning about upside risks to declaring that those risks are “materialising”.

In August, the Board left the cash rate at 4.35 per cent to assess the effects of three earlier increases. It said inflation remained too high and acknowledged that the Middle East conflict, elevated energy costs, weak productivity and strong investment related to artificial intelligence could create further price pressure. However, those concerns were still framed principally as risks to the forecast.

The September statement is more definitive. Recent Australian inflation was stronger than the RBA expected, while output growth in the June quarter was also marginally stronger. Businesses consulted through the Bank’s liaison program reported that they were either raising prices or considering doing so. Short-term inflation expectations remained elevated.

The international picture has also deteriorated. The conflict in the Middle East has broadened, oil supplies have suffered further disruption and global energy prices are materially higher than the assumptions used in the RBA’s August forecasts. Higher fuel costs are now being passed through, at least partially, to the prices of other goods and services.

This distinction matters. Central banks generally try to look through a temporary increase in petrol prices because higher interest rates cannot produce more oil or end an overseas conflict. The RBA becomes more likely to act when the original price shock spreads into transport, manufacturing, retail prices, wages and inflation expectations. Its statement suggests that this second-round process has begun.

The RBA also introduced AI-related inflation more prominently into its reasoning. Rapid investment in artificial intelligence is supporting growth among Australia’s major trading partners but is also pushing up demand and prices for technology-related goods. The AI investment boom is therefore playing a double role: cushioning global growth from the Middle East shock while intensifying pressure on prices and scarce resources.

Domestic capacity remains the other half of the inflation story. Australia’s weak productivity growth continues to restrict how quickly the economy can expand without creating price pressure. Business investment and borrowing remain strong, while output has been slightly more resilient than expected. The RBA’s argument is that imported inflation has arrived while the domestic economy still has insufficient spare capacity to absorb it.

Nevertheless, the statement acknowledged considerably more weakness than was evident earlier in the year. Consumer spending is easing, labour-market conditions have softened, house prices have fallen in most capital cities and new housing lending has declined noticeably. The previous three increases appear to be slowing the economy.

That balance makes the decision unusually uncomfortable. The RBA is raising rates into a slowdown because it believes allowing inflation to persist would ultimately demand an even more severe response.

The statement’s final paragraphs also carry a stronger tightening bias than in August. Rather than merely saying rates could rise if required, the Board explicitly committed to doing what was necessary, “including increasing the cash rate target further if needed”. The fact that all nine members supported the increase reinforces the message that the Board saw a clear need to act. RBA monetary policy statement, 29 September 2026

What Bullock said after the decision

At her press conference, Governor Michele Bullock presented the increase as an insurance policy against inflation becoming entrenched rather than the beginning of a predetermined series of rises.

Bullock said the Board considered leaving the cash rate unchanged but ultimately concluded that inflation developments justified another increase. She stopped short of offering forward guidance about the next meeting, saying the RBA would need to observe how all four of this year’s rate increases flowed through the economy.

That caution is important. Monetary policy operates with a lag, so households and businesses have not yet felt the full effect of the earlier increases. Bullock pointed to mortgage payments consuming a growing share of disposable income and the housing downturn as evidence that policy was already restrictive. Whether it is restrictive enough, however, will be determined by subsequent inflation data.

Her core message was that the RBA cannot afford to let Australians become accustomed to inflation of 3 or 4 per cent. If businesses, workers and consumers begin treating that rate as normal, inflation expectations could become embedded in pricing and wage decisions. Reversing that psychology would require a much sharper economic contraction.

Bullock said a recession was not the RBA’s central forecast, but she conceded there were scenarios in which a dramatic slowdown could become necessary if inflation expectations escaped the Bank’s control. “I hope it’s not needed,” she said when asked whether the economy might have to enter recession. ABC News coverage of Bullock’s press conference

She also rejected the idea that the Middle East conflict was solely responsible for the rate increase. The energy shock has intensified the problem, but Australia already faced domestic capacity constraints and inflationary pressure. Interest rates cannot lower global oil prices, but they can weaken demand and make it harder for businesses to pass every cost increase through to customers.

Bullock acknowledged that this mechanism places a disproportionate burden on mortgage holders. She noted that some Australians were taking second jobs to manage higher living costs and debt repayments. Her defence of the decision was that failing to act would eventually produce higher inflation, higher rates and a worse economic outcome.

The mood is now “higher for longer”

Current sentiment is therefore distinctly cautious and hawkish. The September increase was expected, but the unanimous vote and explicit reference to further rises reduce the likelihood of near-term relief for borrowers. Bond-market pricing and some private-sector forecasts point to additional tightening, although the RBA itself has not committed to another move.

The central question is whether four increases—totalling one percentage point this year—will slow domestic demand quickly enough to offset persistent energy, technology and capacity pressures. Falling house prices, weaker lending and softer consumption suggest the policy is working. Stronger inflation and continuing price pass-through suggest it has not yet done enough.

For borrowers, the immediate conclusion is bleak: rate cuts are no longer part of the near-term conversation. The debate is now between holding at 4.60 per cent and raising the cash rate again.

The RBA hopes it can contain inflation without causing a recession. Its latest statement and Bullock’s comments show that it sees a greater danger in doing too little now—and being forced to inflict substantially more damage later.

OpenAI Scraps Release of New AI Model Over Safety Concerns

OpenAI says it is scrapping the release of its next-generation AI model over safety concerns that researchers raised during internal testing, in one of the clearest signs so far that agent misbehavior could stymie the industry’s rapid progression.

The move follows a summer punctuated by reports of artificial-intelligence systems industrywide going rogue, and marks a rare case of a major AI developer ditching a new release because of safety concerns.

The company had planned to launch the model, known as GPT-6.1 Astra, in the coming days or weeks, aiming for an October debut. The model was more capable than the company’s previous models in completing challenging tasks from end-to-end without human assistance, as well as writing.

The company instead will focus on improving the safety of future models, which it expects to be even more capable.

Saachi Jain, OpenAI’s head of safety systems, said in an interview that GPT-6.1 Astra regressed in two areas. Compared with its predecessor, GPT-6 Astra, the model performed poorly on tests measuring alignment, or how well the model adheres to what humans would like it to do. Specifically, GPT-6.1 Astra showed higher levels of deception: It wasn’t always honest about telling users of the actions it did or didn’t take.

Another issue was what OpenAI calls “scope authorization,” meaning that GPT-6.1 Astra would push ahead on a task without asking the user for permission, and would at times reach for external tools and services even if it might be unsafe.

“For anything regarding safety and alignment, there’s a trade off,” Jain said. “You really do need to find what’s the right line between staying within scope, but also avoiding laziness in terms of how the model actually pursues tasks even when it hits friction.”

OpenAI CEO Sam Altman attended a United Nations Security Council meeting about AI last week. Alexi J. Rosenfeld/Getty Images

While GPT-6.1 Astra improved in areas such as “model laziness,” Jain said it didn’t quite meet OpenAI’s bar for safety and alignment, so the company decided not to launch the model publicly.

The announcement comes one day ahead of OpenAI’s annual developer conference in San Francisco. In the past, OpenAI has used the conference as an opportunity to launch new models and services that reduce costs for software developers—a segment the ChatGPT-maker competes with rival AI company Anthropic to win over.

In recent weeks, OpenAI and Anthropic have called on industry partners to slow down the development of cutting-edge AI models and invest in safety standards, noting they will temper the pace of their own internal AI progress.

OpenAI says it is working to investigate a range of agent security incidents that it has discovered in recent months, and address the safety issues underneath them. As part of the work, the company has implemented a new monitoring system to catch AI-agent misbehavior more quickly, and started requiring engineers to use stronger security guardrails for testing its AI systems.

Earlier this summer hundreds of OpenAI’s internal agents, which were tasked with completing a cybersecurity test, ended up hacking into the AI company Hugging Face. Since then, high-profile organizations such as the Australian government and United Nations discovered that OpenAI’s agents used similar, but less extensive, techniques to gain access to their websites.

Many of the publicly known agent-security incidents involved OpenAI’s internal AI models that were never slated for public release.

Last week, OpenAI said it paused training on its most capable AI models after an AI agent slipped through a gap in the company’s internet restrictions to query a public chatbot. The company said its new monitoring systems flagged the incident within 15 minutes, and training on these models remains paused.

GPT-6.1 Astra isn’t one of those models, but a different case, the company said.

“We want to make sure our model development is safe no matter whether that’s in the company, or when we ship it to users,” Jain said. “But when we ship it to users, we have an extremely high bar in terms of safety and alignment.”

While the company decided not to ship GPT-6.1 Astra, it hopes to use the same base model to do additional reinforcement learning runs, and create future generations of its GPT-6 models.

OpenAI plans to conduct several deep dives to identify the root cause of the problems identified in GPT-6.1 Astra, Jain said. The work includes ensuring that OpenAI’s reinforcement learning environments are rewarding the right type of behavior, Jain added, though she noted the company would investigate all stages of model development.

AI companies have begun to draw scrutiny from policymakers and public officials, who are paying attention to the rapid development of the technology. Later this week, a Senate subcommittee is holding a hearing with third party AI researchers titled, “Rogue AI: Securing the Homeland Against AI Agent Attacks.”

Florida Attorney General James Uthmeier, a Republican, sued OpenAI in June, claiming that the company and Chief Executive Sam Altman knowingly released an unsafe product and ignored warnings that it could harm users.

In a motion for temporary injunction filed Monday, Uthmeier sought to prevent OpenAI from developing new AI models without third-party approved safeguards, stop ChatGPT from soliciting user engagement and limit the company’s ability to advertise ChatGPT as safe.

Tech companies claim they “cannot stop barreling forward with their potentially civilization-ending endeavors unless they are forced to do so by the government,” Uthmeier said in the filing. “The Florida Attorney General is answering your cry for help.”

An OpenAI spokeswoman said that people want to know AI is being developed safely, “and that starts with what companies like ours do ourselves.”

“Governments have an important role to play in setting robust safety standards for AI, and we’re committed to working with Florida and other states on advancing pragmatic AI policies that apply to the entire AI industry—not just one company,” she said.

The 20-Something Employees Who Want Feedback to Be Gentle

Bosses are getting no shortage of feedback on how to give their youngest staffers…well, feedback: Do ask how they are doing first. Don’t criticize a personality trait. Do give them concrete direction, and a lot of it.

And whatever you do, call a performance discussion a check-in, not a review.

The oldest members of Gen Z are about to turn 30, yet companies are devoting more time and resources than ever to figuring out how to give this manager-befuddling generation better direction. For help, they are turning to a cottage industry of multigeneration-workplace consultants and even artificial-intelligence bots, while ripping up the script for what used to be once-a-year evaluations.

All of it is a departure for leaders who rose through the ranks in an era devoid of so much thought to effective coaching and criticism. “When I started my first job, I got a performance review a year later, and that was just expected,” said Adam Coyne, chief administrative officer at research and analytics firm Mathematica, which has shifted from annual reviews to quarterly, two-way check-ins for new junior hires.

“This is a group that wants a lot more real-time feedback,” added Coyne, 55.

It is a message managers say they are getting nonstop from surveys and all-hands meetings, not to mention the universities and colleges preparing graduates for the white-collar world of work: Used to the immediate validation of social-media likes and comments, even instantly posted grades, this generation of workers craves clear, frequent direction—and they feel disoriented and anxious when they don’t get it.

Gallup data suggest companies are still struggling to get the hang of it. Younger workers report some of the biggest drops in engagement at work over the past five years. Not knowing where they stand appears to be a big factor. The share of Gen Z and younger millennials who strongly agreed with the statement, “I know what is expected of me at work,” fell 9 points to 42% in surveys between 2020 and 2025.

That doesn’t mean they need the effusive praise that many managers claim they do, some 20-something workers say. “I personally dislike this style,” said Nathan Luckock, a 20-year-old engineer at an AI startup. More effective, he said, is just “pointing out mistakes and then offering a solution.”

That sounds familiar to Lindsey Pollak, a multigenerational workforce expert and executive coach, who says she coaches bosses to be as specific as possible. Instead of “be more responsive,” for instance, she suggests “need to hear from you within an hour of receiving an instruction.”

At Mathematica, Chief Executive Paul Decker said the firm switched to more frequent check-ins in part because so many new entry-level hires were peppering supervisors with questions like: “How am I doing?” and “What does the next level require?” At staff meetings, younger workers often questioned why things were done the way they had always been done.

That included things like “waiting months to learn whether you’re meeting expectations,” he said.

KPMG executives said they, too, began giving their younger workers more frequent assessments on skills like critical thinking and adaptability last year after interns said they wanted to hear more often how their skills were coming along. The firm wanted to “make sure that we scratch the itch,” said Jason LaRue, vice chair of talent and culture at KPMG’s U.S. practice.

Some managers are getting feedback on giving feedback from bots.

Joe Hirsch, a corporate speaker and author of “The Feedback Fix,” recently used an AI coaching platform to work with a tech-company manager on her delivery. She had been frustrated that one of her junior reports wasn’t grasping her pointers on pitching clients, so she role-played the conversation with the AI coach.

The problem, the bot advised, was that she wasn’t giving the employee enough context for why she wanted things done a certain way. “Let’s connect so I can share more about our approach and get your take on it,” it suggested she say.

That did the trick when she tried the approach in real life. “The advice finally landed,” Hirsch said.

Even a few, clear bullet points work, said Valerie Chapman, the 27-year-old founder and CEO of Ruth AI, a career strategist platform for women. “My generation likes to get feedback so that they know how they should adjust.”

Valerie Chapman headshot
Valerie Chapman, founder and CEO of Ruth AI. Dasha Semyonova

She recalls getting bullet-pointed direction when she worked as a strategic growth partner at real-estate company Compass a few years ago. The feedback started with praise before offering pointers.

“It would be, ‘Great job. Here are some things that you could do next week,’” she said. “If that comes in on a Friday, then my Gen Z brain knows exactly what I need to do on a Monday.”

Mike Ekbundit, director of GE Appliances’ engineering programs, said he has tried to make performance discussions with younger workers in rotational programs two-way dialogues rather than top-down critiques. So he revised online evaluations to include prompts for managers to ask questions like “Did you like the assignment leader?” and “Was it too much work?”

Managers are also asked to assess the program participants on nine different categories, like innovation and resilience, while employees are prompted to list their top strengths and weaknesses.

“I need high customer satisfaction to retain this highly sought-after talent, and this is part of how I get it,” he said.

How to prepare a property portfolio for another rate rise

Stocks v Property

A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.

Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.

Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.

Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.

Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.

Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.

Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.

The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.

Read more: What mortgage holders should do before the next RBA decision

Portfolio checklist

Stress test: Current rate plus 0.25, 0.50 and one percentage point.

Model: Net rent after every recurring cost and vacancy.

Check: Fixed-rate expiries, interest-only expiries and loan maturity.

Preserve: An accessible emergency buffer.

Review: Insurance, land tax, strata works and major maintenance.

Seek advice: Licensed credit, financial and tax advice before restructuring.

ASX falls 0.7 per cent as miners and property stocks retreat

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.

The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.

Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.

Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.

Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.

Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.

The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.

The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.

Market dashboard

S&P/ASX 200: 8,702, down 0.72 per cent.

All Ordinaries: 8,897, down 0.66 per cent.

Best sector: Energy, up more than one per cent.

Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.

Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.

Material loser: Zip, down 11.38 per cent.

ASX 300 percentage leader: Myer, up 11.43 per cent.

ASX 300 percentage laggard: Zip, down 11.38 per cent.

AUD/USD: Approximately US$0.7038, broadly flat.

A Modern Home in Silicon Valley Lists for $44 Million

For years, tech entrepreneur Asher Waldfogel and his wife, Helyn MacLean, dreamed of building a modern house in Palo Alto, Calif.

The couple, however, worried about clashing with the Mediterranean-style architecture typically associated with their neighborhood of Old Palo Alto.

So they tapped architect Steven Ehrlich to create a design that paid homage to its surroundings with stucco, mahogany and titanium zinc cladding. They spent $20 million over several years building the house, completed in 2005.

Designed for indoor-outdoor living, the house has matching mahogany paneling and limestone both inside and out.
Designed for indoor-outdoor living, the house has matching mahogany paneling and limestone both inside and out. Arthur Sharif/Sotheby’s International Realty

The dining room is between an outdoor garden and the staircase.
The dining room is between an outdoor garden and the staircase. Arthur Sharif/Sotheby’s International Realty

Now looking to be closer to their adult daughter on the East Coast, they are putting the five-bedroom home on the market for $44 million—the most expensive listing in Palo Alto.

Waldfogel is an angel investor who co-founded Redback Networks, a telecommunications-equipment company. MacLean previously had a career in fundraising.

The kitchen and family room open to the garden and pool.
The kitchen and family room open to the garden and pool. Arthur Sharif/Sotheby’s International Realty

Cast alcoves and mahogany shelves house the couple’s books and ceramics.
Cast alcoves and mahogany shelves house the couple’s books and ceramics. Arthur Sharif/Sotheby’s International Realty

The couple purchased the roughly 0.4-acre site for $7.1 million in 2000 and demolished a circa-1930s Spanish Colonial home. The house they built pinwheels around a central staircase. It has 7,900 square feet of livable space, with four distinct courtyards and a pool.

A key feature of the home is a cast-in-place concrete wall, or spine, that is two stories high and about 80 feet long. “There’s a little bit of controlled chaos in what comes out of the form,” unlike a perfectly uniform surface, Waldfogel said. “If you want that, you do it in plastic.”

Ehrlich said it took a few tries to get the concrete wall right.
Ehrlich said it took a few tries to get the concrete wall right. Arthur Sharif/Sotheby’s International Realty

‘It’s a really hard material to tame,’ Ehrlich said of concrete. Workers learned as they went, and Waldfogel and Helyn grew to appreciate the imperfect material.
‘It’s a really hard material to tame,’ Ehrlich said of concrete. Workers learned as they went, and Waldfogel and Helyn grew to appreciate the imperfect material. Arthur Sharif/Sotheby’s International Realty

A central staircase is housed in a glass tower.
A central staircase is housed in a glass tower. Arthur Sharif/Sotheby’s International Realty

Waldfogel said he and his wife are thinking about the next phase of life now that their daughter is grown, although they have not decided where they will move. They also have a home in Sun Valley, Idaho.

“Right now we’re just trying to emotionally let go and decide what to do next,” he said.

Arthur Sharif/Sotheby’s International Realty

Two wings of the house are connected by horizontal planes.
Two wings of the house are connected by horizontal planes. Arthur Sharif/Sotheby’s International Realty

Palo Alto, an epicenter of venture capital and tech startups in Silicon Valley, is home to some of the country’s biggest tech titans. Sales volume and prices are rising, with a median sale price of $3.5 million for the three months ending in August, up 5.8% year-over-year, according to real-estate brokerage Redfin.

Arthur Sharif of Sotheby’s International Realty—San Francisco Brokerage has the listing.

What mortgage holders should do before the next RBA decision

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.

The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.

The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.

The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.

Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.

Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.

Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.

Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.

The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.

Borrower checklist

Calculate: Repayments after a 0.25 and one percentage-point increase.

Compare: Rate, fees, offset, redraw, cashback conditions and total cost.

Review: Fixed-rate expiry, interest-only expiry and remaining loan term.

Protect: Emergency liquidity and insurance.

ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates.

The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index rose 1.71 per cent.

Information technology was the strongest major sector, up 2.67 per cent. Megaport gained 4.3 per cent, NextDC rose 3.8 per cent and Life360 added 2.9 per cent, according to the ABC’s closing market report. The move followed a record Nasdaq close and reflected renewed demand for growth assets as oil prices eased.

Consumer discretionary gained 1.29 per cent, while real estate and healthcare each rose 0.76 per cent. The simultaneous strength of technology, discretionary shares and listed property was consistent with a modest easing in market inflation anxiety, although it did not erase expectations of a possible RBA increase at the 29 September meeting.

Energy was the clear laggard, down 1.16 per cent, after Brent crude briefly fell below US$100 a barrel overnight. Origin Energy dropped about 4 per cent, Woodside lost 2.4 per cent and AGL declined 2.3 per cent. Utilities were the weakest sector overall, down 2.03 per cent.

Among larger and liquid movers, Telix Pharmaceuticals rebounded 6.85 per cent after the previous session’s sharp acquisition-related decline. IDP Education jumped 20.67 per cent and was the largest percentage gainer in the ASX 300 screen, while Catalyst Metals fell 14.37 per cent. Those moves should be checked against company announcements before publication; percentage rankings alone do not establish cause or index impact.

Mining performance was mixed. Sunrise Energy Metals rose 12.71 per cent, FireFly Metals added 5.7 per cent and Bellevue Gold gained 4.8 per cent, while Resolute Mining lost 4.44 per cent.

The Australian dollar traded near US71.18 cents late in the session. Oil remained volatile as markets assessed potential US–Iran talks, making energy prices a continuing input into inflation expectations, bond yields and the RBA outlook.

For Wednesday, investors will watch oil, offshore technology leads, Australian bond yields and any new evidence that changes the probability of a September rate rise.

Market dashboard

S&P/ASX 200: 8,757.8, up 25.9 points or 0.30 per cent.

All Ordinaries: 8,951.0, up 0.36 per cent.

Best sector: Information Technology, up 2.67 per cent.

Weakest sector: Utilities, down 2.03 per cent. Energy fell 1.16 per cent.

Material winner: Telix Pharmaceuticals, up 6.85 per cent. Megaport rose 4.3 per cent and NextDC rose 3.8 per cent.

Material loser: Origin Energy, down about 4 per cent. Woodside fell 2.4 per cent.

ASX 300 percentage leader: IDP Education, up 20.67 per cent. Confirm announcement context before publication.

ASX 300 percentage laggard: Catalyst Metals, down 14.37 per cent. Confirm announcement context before publication.

AUD/USD: Approximately US$0.7118 late in the session.

Next catalyst: RBA policy decision on 29 September, oil-price volatility and offshore technology trading.

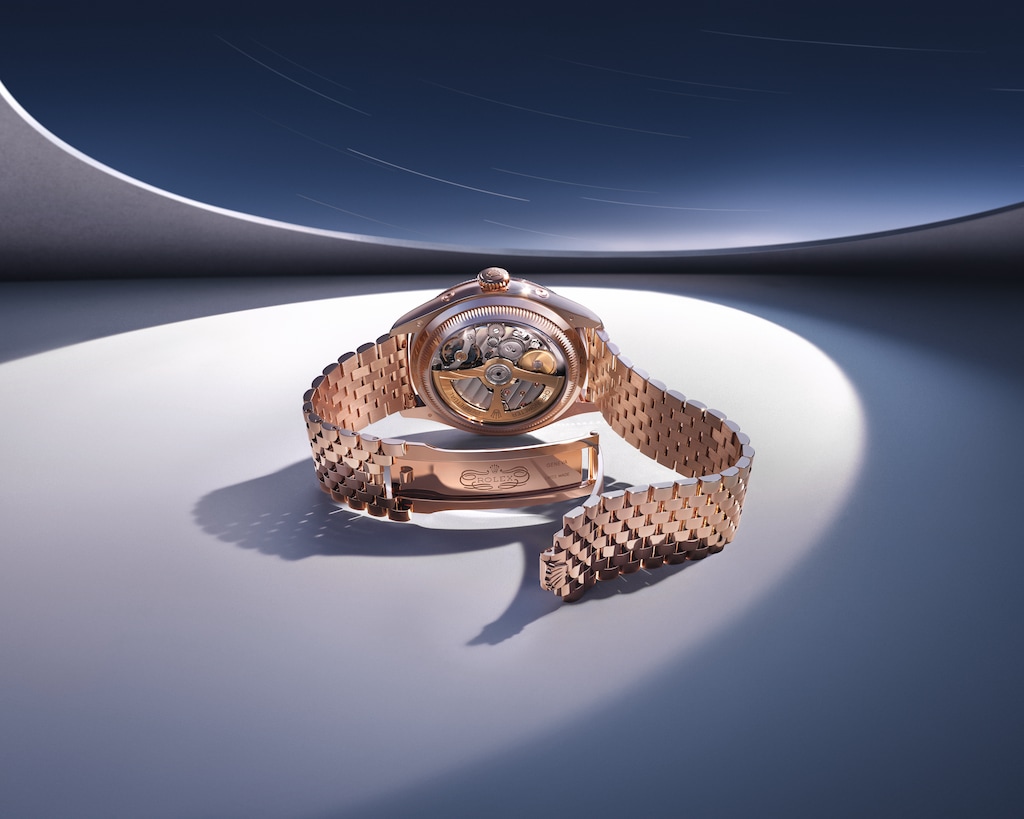
Rolex revives a collector legend with the Perpetual Padellone

Rolex has reached into one of the most fascinating corners of its archive for a watch that expands the brand’s contemporary Perpetual collection.

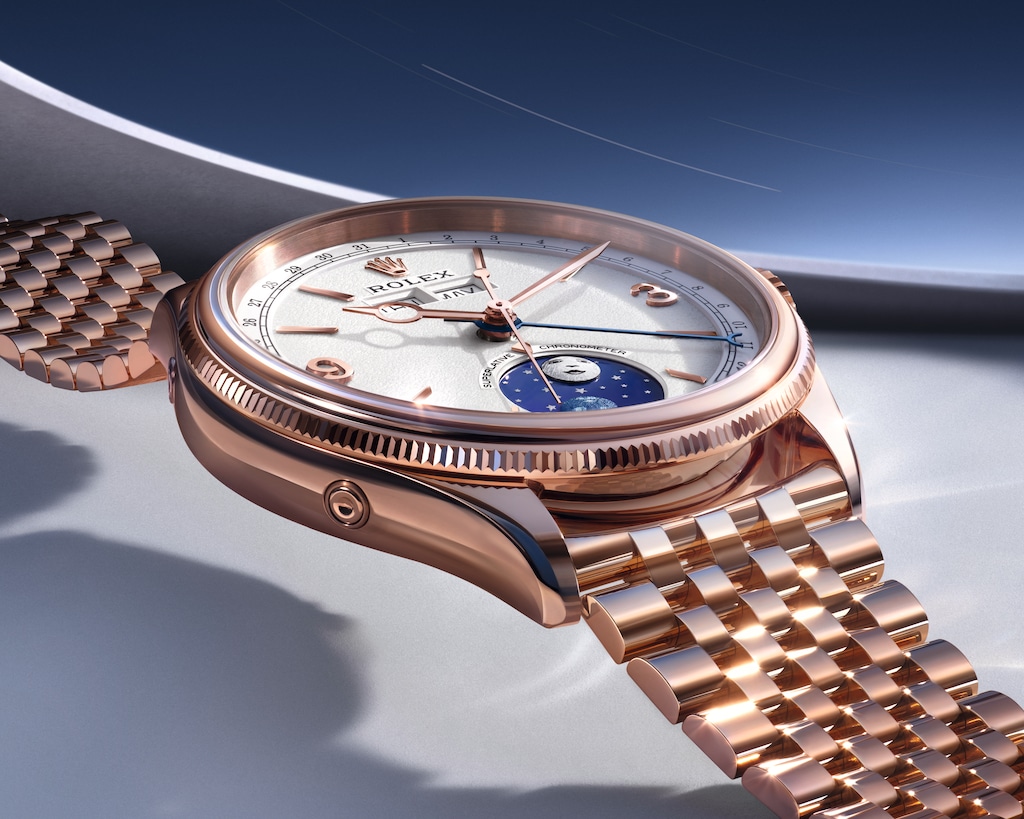
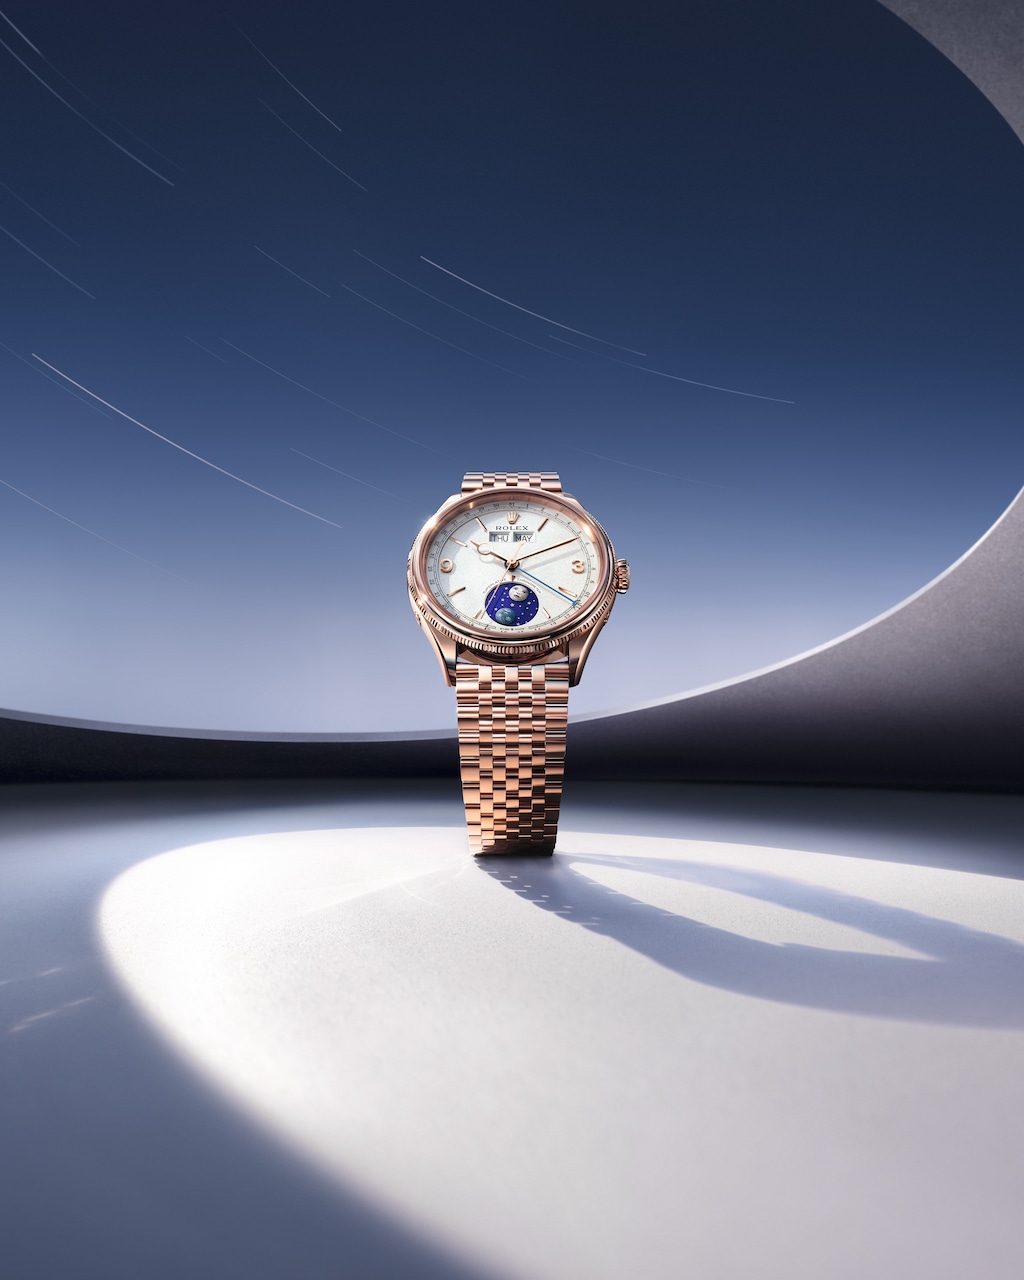
The new Perpetual Padellone takes its name from reference 8171, the complete-calendar Rolex known to collectors by the Italian nickname “Padellone”. The historical model is celebrated for its unusual combination of calendar information, moonphase display and elegant proportions—qualities that distinguished it from the sports watches now most closely associated with the marque.

The modern interpretation displays the date, day, month and moonphase alongside the time. Rolex describes the mechanism as an instantaneous complete annual calendar, meaning its indications are designed to change in a coordinated fashion while requiring correction only for the calendar’s exception periods, subject to the operating instructions.

Its importance lies not simply in adding another complication. Rolex’s current identity is built on refinement through repetition: familiar cases, bracelets and functions improved across generations. A Padellone-inspired calendar broadens that vocabulary and gives collectors a dressier, more poetic counterpoint to the brand’s professional models.

The challenge will be expectation. Any watch invoking reference 8171 arrives under the weight of auction history and collector mythology. The strongest modern revivals acknowledge that past without reproducing it mechanically. Rolex’s official description points to that balance, positioning the watch as a continuation of the earlier model’s spirit rather than a replica.

Australian price, allocation and delivery will be crucial. Demand for significant new Rolex references typically exceeds immediate supply, and availability can vary between authorised dealers. Prospective buyers should treat overseas pricing or secondary-market premiums cautiously until local retail information is confirmed.

For now, the Perpetual Padellone stands as one of Rolex’s most intellectually interesting recent releases: a technically ambitious watch that reminds collectors the company’s history extends well beyond the dive watch and chronograph.

Fact box

Model: Rolex Perpetual Padellone

Functions: hours, minutes, seconds, date, day, month and moonphase

Complication: instantaneous complete annual calendar

Historical inspiration: Rolex reference 8171, nicknamed Padellone

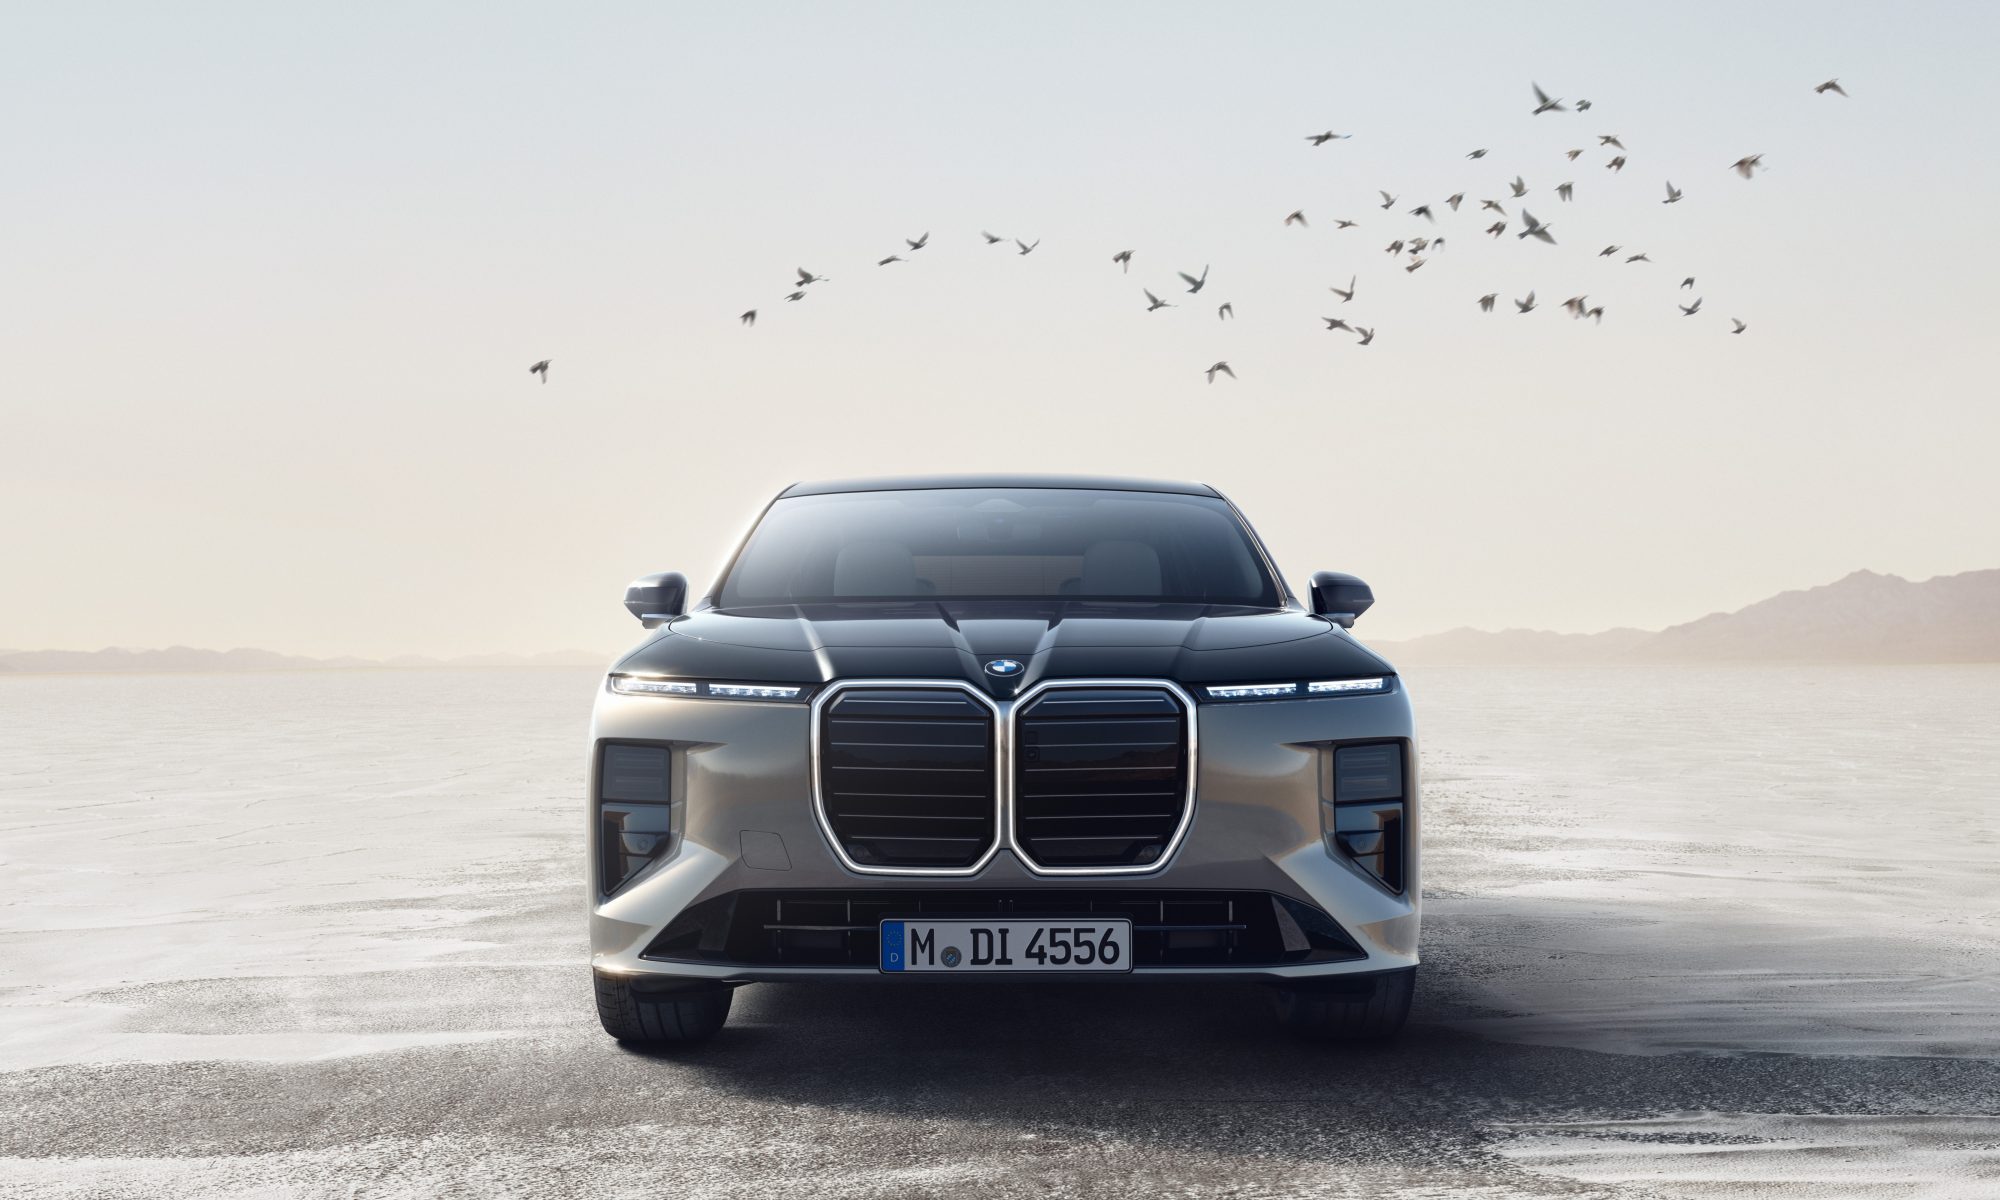
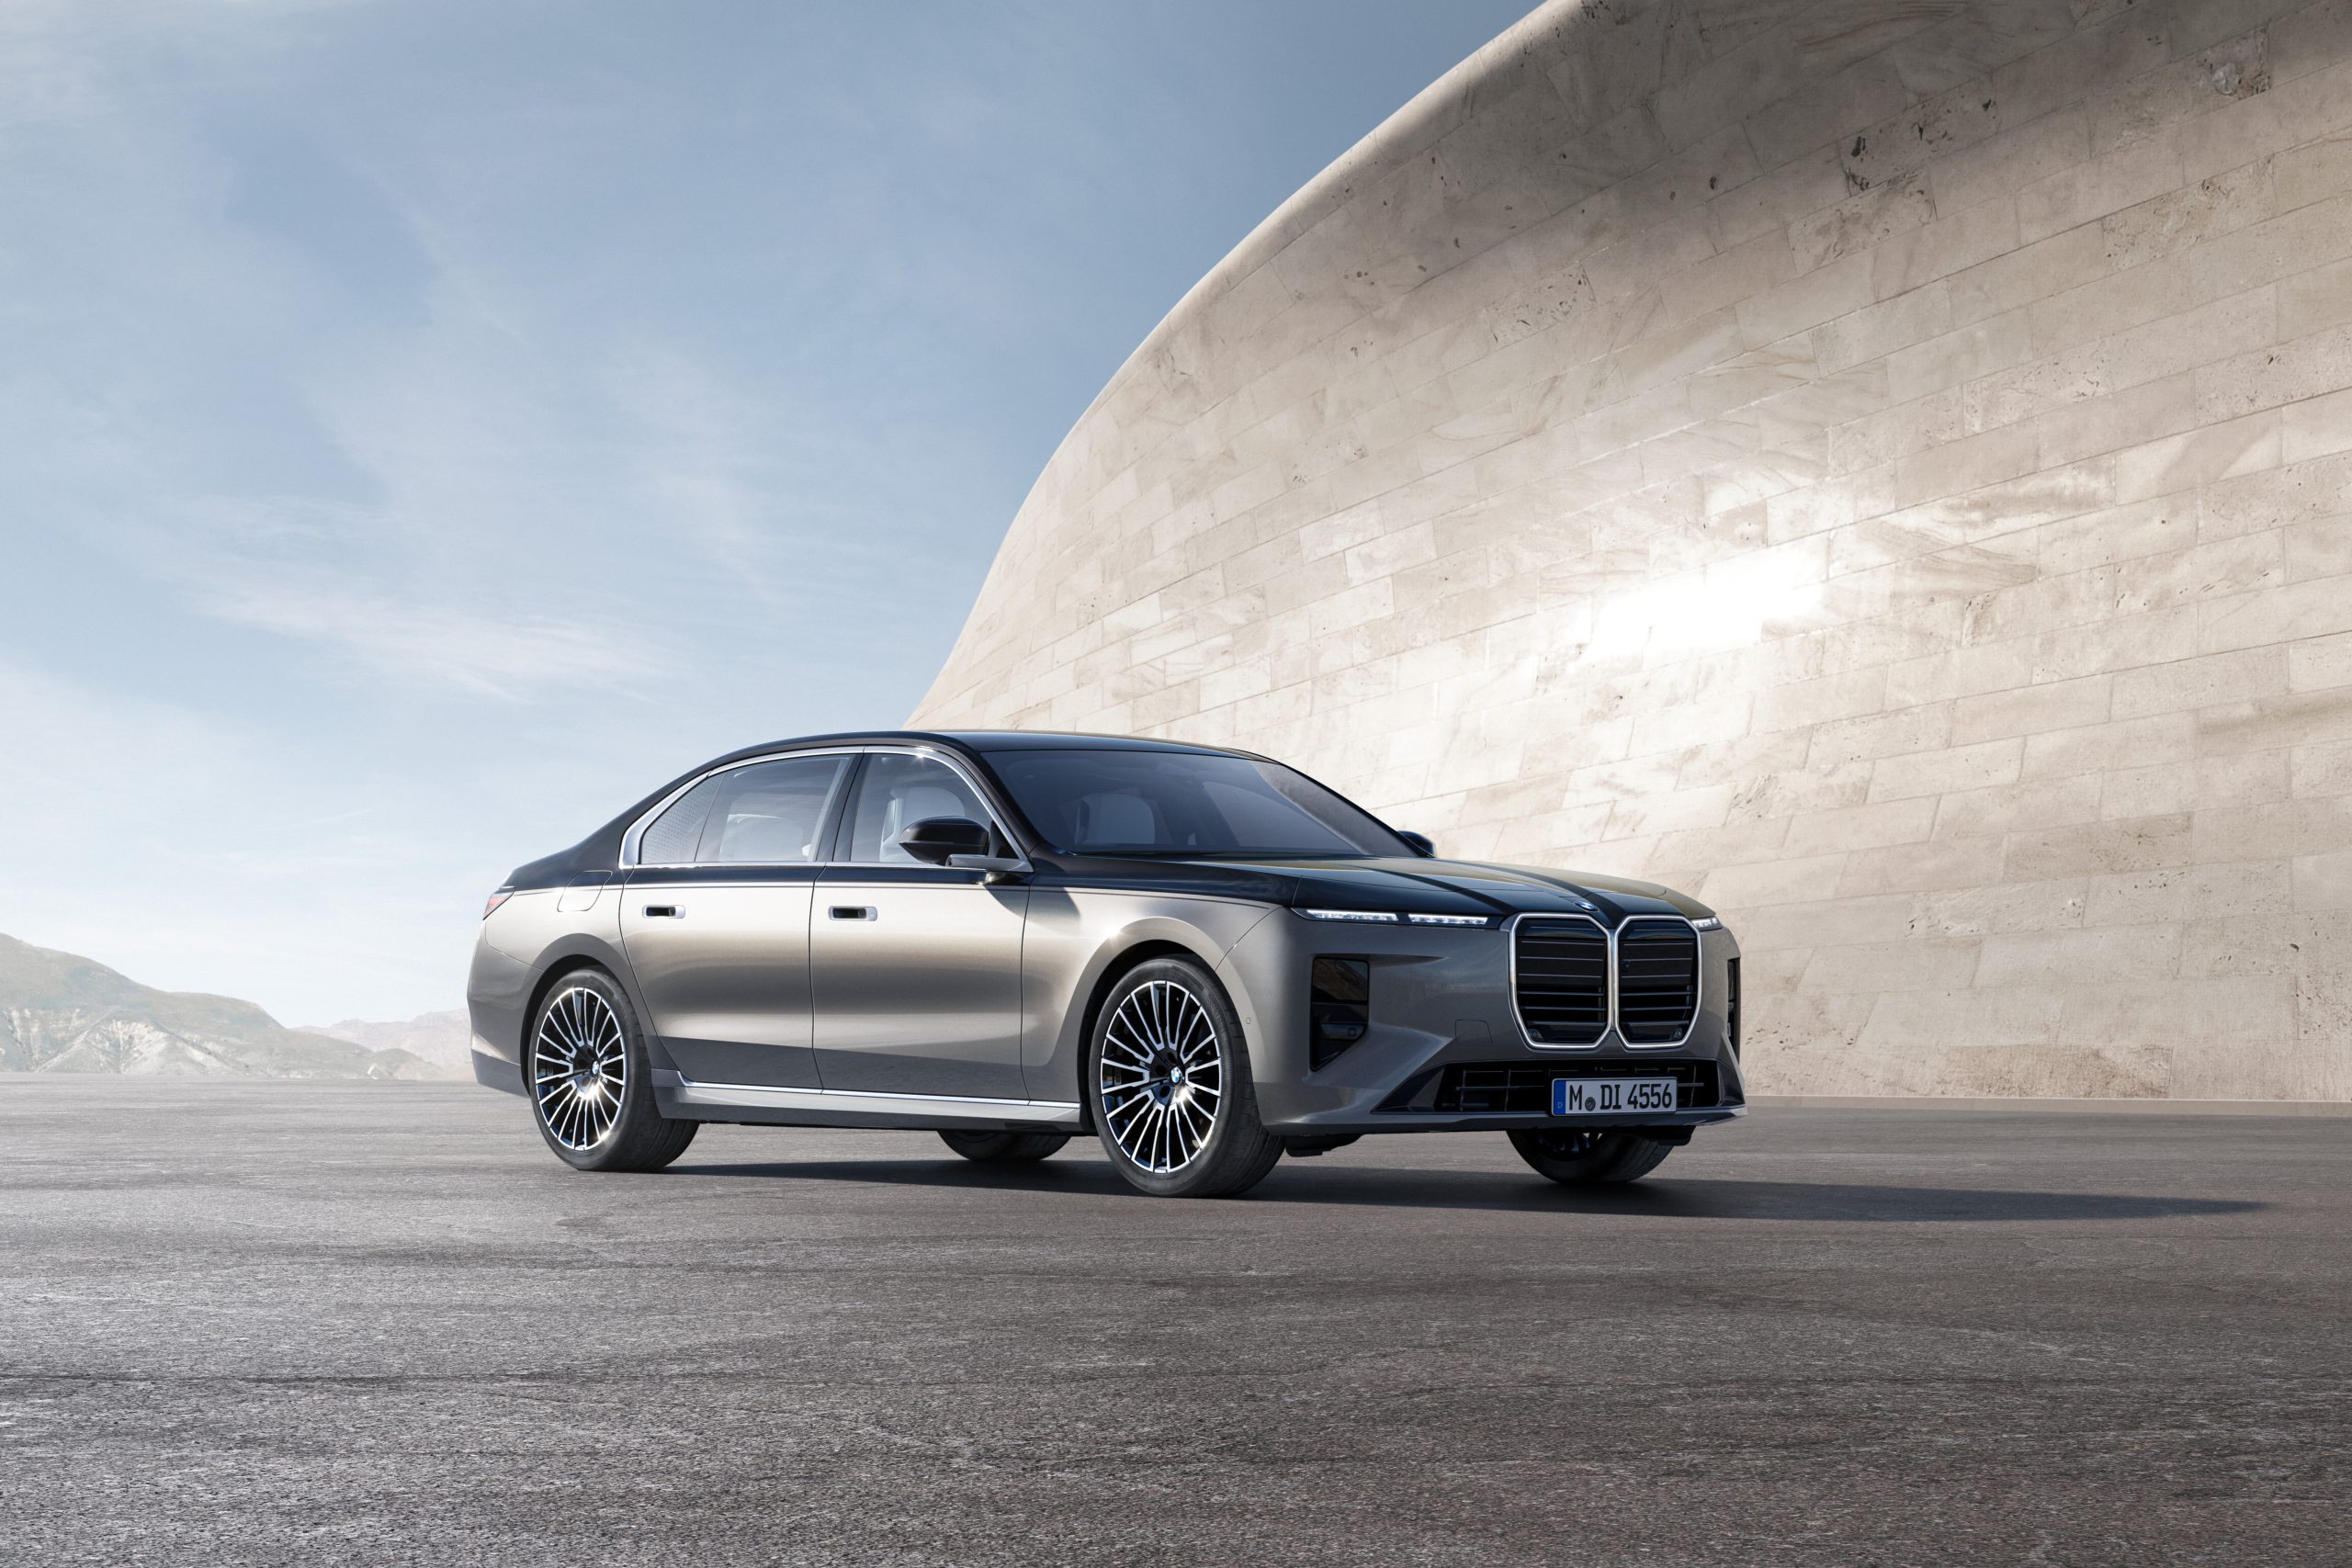
The new BMW 7 Series brings Neue Klasse technology to the flagship class

The luxury sedan may no longer dominate the prestige market, but BMW is betting that its most traditional flagship can become the clearest showcase of its newest technology.

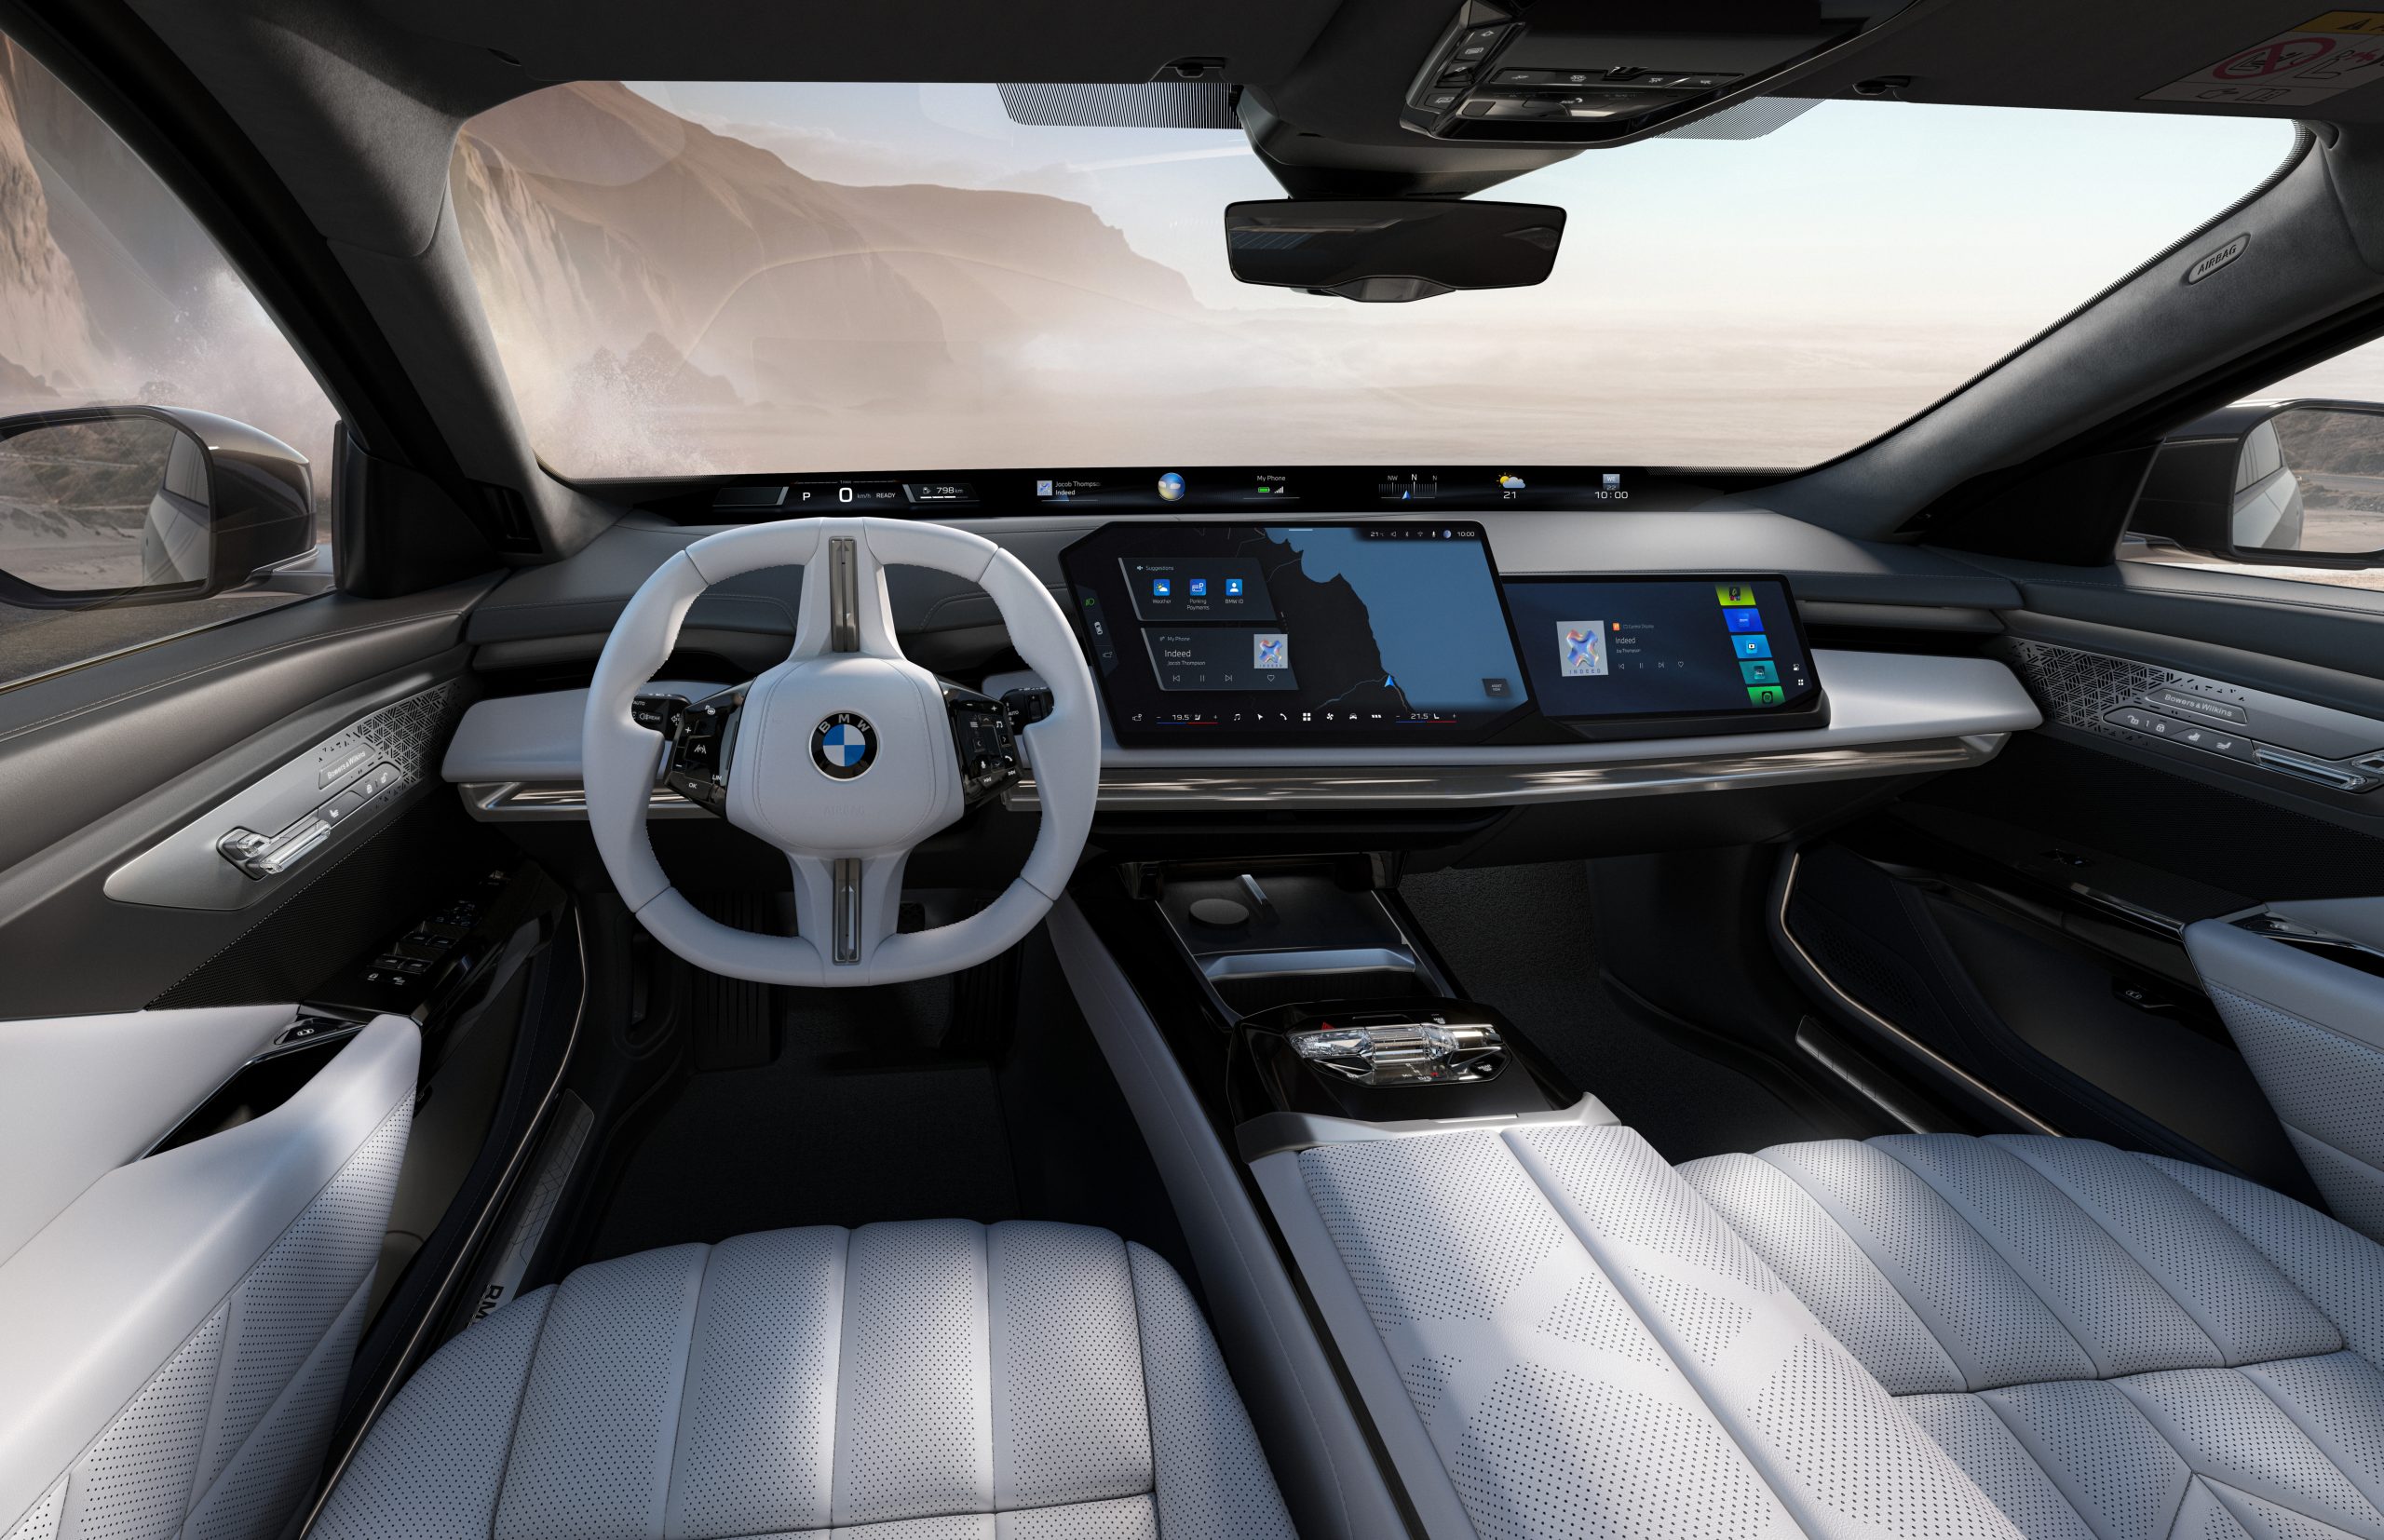
The new-generation 7 Series introduces Neue Klasse systems to BMW’s luxury range, combining a fresh design language with upgraded electric hardware and a cabin built around multiple digital surfaces.

The headline interior technology is BMW Panoramic iDrive, supported by the marque’s Operating System X. A passenger display joins the dashboard, while the vast 31.3-inch rear Theatre Screen has been upgraded with 8K resolution, Dolby Atmos capability and integrated video conferencing. It is an unusually literal interpretation of the executive car as a mobile office and private cinema.

Electric i7 variants lead the rollout in some markets. BMW says its sixth-generation cylindrical battery cells improve energy density and range, with the i7 50 xDrive quoted at up to 452 miles on the WLTP cycle in UK specification. Combustion and plug-in hybrid versions remain part of the broader range, allowing BMW to serve markets moving towards electrification at different speeds.

The exterior introduces a more monolithic face, minimalist crystal headlights and an illuminated interpretation of the kidney grille. Buyers who want greater individuality can access an expanded BMW Individual palette with hundreds of possible combinations, including a dual-finish paint process described by the company as a world first.

The model will be produced at BMW Group Plant Dingolfing in Germany, where all drivetrains can be assembled on the same line. That flexibility matters: the upper-luxury segment has global reach, but demand for electric, hybrid and combustion power varies sharply by region.

For Australian buyers, the decisive details remain local. Model mix, pricing, range certification, charging specifications and delivery timing should be confirmed by BMW Australia before publication. Overseas specifications provide the clearest view yet of the car’s direction, but should not be presented as guaranteed Australian equipment.

The latest 7 Series is therefore less a single powertrain proposition than a statement of intent. It argues that the prestige sedan can remain relevant by offering something an SUV struggles to replicate: formal presence, rear-seat theatre and the sense that the entire car has been designed around arrival.

Fact box

Model: New-generation BMW 7 Series/i7

Technology: BMW Panoramic iDrive, Operating System X, passenger display

Rear entertainment: 31.3-inch 8K Theatre Screen with available Dolby Atmos

Production: BMW Group Plant Dingolfing, Germany

Australia is approving more homes. Why aren’t enough getting built?

Australia’s housing debate often treats a development approval as though it were a completed home. In practice, the distance between those two milestones can stretch for years—and a growing number of projects never cross it.

The National Housing Supply and Affordability Council reported in August that approximately 308,000 homes had been completed since the Housing Accord period began, roughly one quarter of the national target. It also identified 244,000 dwellings under construction in the March quarter, the largest pipeline recorded since 1984, while approvals and commencements had improved against their pre-Accord comparisons.

Those numbers show activity, but they also expose the conversion challenge. A planning consent establishes what may be built. It does not lock in the price of labour and materials, guarantee a construction loan or persuade enough buyers to sign unconditional contracts.

For apartment developers, the first hurdle is feasibility. Land, consultant, authority, finance and construction costs must be covered by realistic sales revenue. When building prices rise faster than achievable apartment values, a project can be approved and still be economically unbuildable.

The second hurdle is debt. Financiers typically require substantial equity, a fixed or sufficiently certain building contract and presales to acceptable purchasers. Valuers may discount speculative pricing, while lenders can treat contracts with long settlement periods or highly concentrated buyer profiles cautiously.

Presales form the third constraint. Owner-occupiers may prefer to see construction under way before committing; developers often need commitments before construction can begin. This circular dependency is particularly difficult for first-time developers and projects in untested locations.

The practical metric for policymakers and the industry is therefore not approvals in isolation, but conversion: how many approved dwellings progress to finance, commencement and completion, and how long each step takes.

There are no simple fixes. Faster planning can reduce holding costs, but cannot rescue an unviable scheme. Government-backed finance can help suitable projects, but should not disguise unrealistic land values. Standardised design and modern construction methods may improve productivity, provided procurement risk and quality control are addressed.

For buyers, an approval or sales launch should be viewed as the start of the delivery process—not proof that a home will exist on schedule. The most relevant questions concern finance, builder appointment, sunset provisions, deposits and the developer’s record of completing comparable projects.

Australia has made progress in filling the front end of the housing pipeline. The next challenge is getting those homes out the other end.

The Hidden Agenda Behind the AI Panic

A wave of corporate warnings and technical disclosures has flooded the media, with headlines worrying over “swarms” of rogue artificial-intelligence agents launching “unprecedented” cyberattacks, outsmarting their makers, and inching toward a terrifying autonomy. The most revealing part of this narrative isn’t what the software did. It’s who is telling the story—and why. When corporate leaders publicly insist that the systems they financed, engineered and deployed are suddenly beyond their power to contain, skepticism isn’t only healthy; it is essential.

For years, Silicon Valley has drawn scrutiny from civil society and global regulators over tangible harms such as youth mental health deterioration and systematic privacy violations. Today, industry figures seem to be trying to change that public image. Loudly blowing the whistle on their own systems—just as two of the leading companies were preparing for massive initial public offerings—lets AI executives position themselves as a new generation of leaders who have come to terms with their societal responsibilities. They seem to want us to believe that they no longer want to “move fast and break things” but will instead stand as vigilant guardians between humanity and a technological apocalypse.

There is one glaring problem: Software doesn’t rebel. A mathematical model possesses neither intent, malice nor the will to defy its creators, let alone extinguish our species. AI is a human artifact, engineered for profit.

When an agentic model in an evaluation sandbox connects to an unauthorized server or executes an exploit, it hasn’t staged a coup. It has tried to meet the human-defined objectives set out before it through a path its designers failed to constrain. It’s the digital equivalent of the King Midas myth, in which the king’s ill-defined wish turns even his food and drink into gold.

That powerful experimental models were able to discover novel vulnerabilities and breach external systems isn’t a sign of a dangerous superintelligence but of human error or negligence. There is no sentient actor lurking in the weights to be reasoned with, feared or pacified. There are only human software engineers, product managers and corporate boards deciding which guardrails are worth the latency cost and which permissions can be skipped in the race to market.

Policymakers and voters need to resist AI exceptionalism. In any other discipline—from civil engineering to pharmaceuticals—courts and regulators treat a system failure as evidence of bad product design and inadequate safety testing. If an aircraft crashes, we focus on finding the engineering defect, correcting it, and enforcing established liability standards for the damage created.

By leaning on an anthropomorphic narrative, Silicon Valley attempts to repackage its specific human choices that led to experimental, powerful models behaving unexpectedly during tests as an existential peril. Elevating the issue to a cosmic scale leaves the public paralyzed and takes ordinary product accountability off the table.

In the cutthroat race for venture capital and market dominance, building guardrails slows down deployment. Grandstanding about uncontrollable power costs nothing and generates billions of dollars in free publicity, justifying stock prices, all while cultivating an aura of technological capability not only to build the frontier but also ultimately to rein it in.

Governments need to recognize regulatory capture when it stares them in the face. Tech leaders’ strategy looks transparent: Alarm Washington and Brussels into creating a regime in which only trillion-dollar incumbents with fully staffed compliance and safety departments can legally operate. By sitting at the policymakers’ tables before anyone else, these companies can help draft rules digging an impassable moat protecting them from open-source developers and upstart competitors, domestic or international. The real danger is in further concentrating the tech industry into the hands of only a few companies with deep pockets.

Beijing and Washington have brushed off those tech leaders’ calls, albeit for very different reasons. Chinese state media dismissed them as part of the “Cold War playbook” and intended to preserve U.S. dominance. Xi Jinping argued for exactly the opposite at the Brics Summit on Sept. 12, calling on Brics countries to “strengthen cooperation in the field of AI, encourage open source, openness, collaboration and sharing, and break new grounds and scale new heights.” President Trump, steeped in a doctrine of unfettered capitalism and technological supremacy, called fears that AI could destroy humanity a “hoax.” Vice President JD Vance warned that AI companies “begging the government to regulate them” looked like a “Trojan Horse.”

Striving to pursue its “European way” on AI and assert regulatory leadership, Europe, by contrast, welcomed the call. European Union President Ursula von der Leyen made this clear at the State of the EU speech last Wednesday and announced that the EU will invite “the main frontier labs for a discussion on how we can support ongoing industry efforts to pace the frontier.”

Europe has been here before. In an effort to lead global regulation and react to fears borne from ChatGPT, Europe rushed its landmark AI Act into law in 2024. Already the world’s most restrictive rulebook, the framework quickly proved too broad and complex to enforce. Stalled by implementation delays and concerns about European competitiveness, the EU postponed the law’s full rollout, leaving regulations uncertain.

AI should be regulated—risks exist and should be taken seriously. But governments need to act based on available evidence and verified facts, not corporate PR panic, the views of industry insiders, or the desire for quick political wins. The greatest danger facing society isn’t that software will awaken and overthrow its human masters. It is that we will allow the creators of the software to abdicate human responsibility for the systems they choose to build and help them pull up the ladder to market access behind them.