Europe’s Stagnating Economy Falls Further Behind the U.S.
Europe’s economy stagnated in the final three months of last year, expanding a divide between a booming U.S. economy and a European continent that is increasingly left behind.

The fresh economic data showed higher borrowing costs had compounded the earlier impact of higher energy prices in the wake of Russia’s invasion of Ukraine.

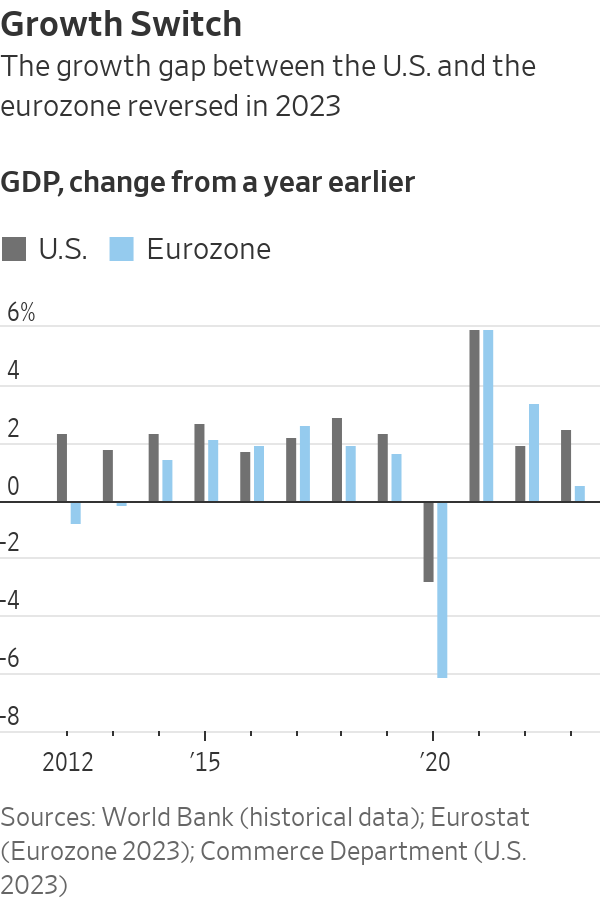
By contrast, the U.S. economy has been expanding robustly and enjoyed its strongest performance relative to the eurozone since 2013—with the exception of the Covid-19 pandemic.
One factor that is threatening to weigh further on the European economy is its proximity to geopolitical flashpoints. Russia’s war on Ukraine sent energy prices rocketing in 2022, hitting European manufacturers. The U.S., as an energy producer, was comparatively unaffected, and its natural-gas industry even benefited when it became Europe’s energy supplier of last resort after Russia throttled gas deliveries to the region.

Now the crisis in the Middle East, which has gummed up cargo traffic through the Red Sea, is adding costs to European importers and disrupting European supply chains. There too, the U.S. hasn’t suffered as much since it has alternative routes for goods coming from Asia.

Europe’s Stoxx 600 index rose 12.64% last year, a little over half the performance of the S&P 500, which rose 24.23% over the same period.

The European Union’s statistics agency Tuesday said gross domestic product in the eurozone was unchanged in the final three months of last year. That followed a decline in the three months through September. During 2023 as a whole, Eurostat recorded growth of just 0.5%, while the U.S. economy expanded by 2.5%.

Still, the divergence between the giant economic blocs is more a story of surprising U.S. strength than unanticipated weakness in the eurozone. The U.S. grew much faster than economists had expected it would at the start of 2023, while the eurozone was about as badly hit by high energy prices and rising interest rates as had been expected. Economists forecast the growth gap will narrow somewhat in the course of the year.

Europe’s policymakers don’t expect the stagnation in output to extend deep into 2024. Instead, they see a pickup in activity as wages rise faster than prices, reversing the declines in real incomes that followed the war in Ukraine and a rise in energy and food bills.

“We have the conditions for recovery that are coming into place,” said European Central Bank President Christine Lagarde Thursday. “I’m not suggesting that it’s going to pick up radically, but it’s coming into place from what we see.”

Helping Europe is the fact that energy prices are falling from post-invasion highs faster than policymakers had expected. That should help boost household spending on other goods and services and lower costs for Europe’s hard-pressed factories.

With inflation easing, the ECB is expected to lower its key interest rate later this year, which would also jolt growth by easing the pressure on household spending and business investment.

Yet the eurozone faces fresh threats too, mainly from the conflict that began with the attack on Israel by Hamas on Oct. 7. Disruptions to shipping in the Red Sea have pushed freight costs sharply higher and led to delays for European manufacturers that rely on Asian suppliers for parts. A further escalation of the conflict could reverse the decline in energy costs and stall the anticipated recovery.

The International Monetary Fund now expects the eurozone to grow by 0.9% this year, a downgrade from its previous 1.2% growth estimate, according to the Fund’s quarterly World Economic Outlook report published on Tuesday. By contrast, it sees the U.S. growing by 2.1% against its earlier 1.5% forecast.

Strong U.S. growth and an estimated 4.6% increase in China’s GDP according to the IMF should more than offset Europe’s disappointing performance and translate into a soft landing for the world economy this year. The IMF now sees the world economy growing at 3.1% this year, the same rate as last year and faster than the 2.9% growth projected in October.

“We find that the global economy continues to display remarkable resilience,” Pierre-Olivier Gourinchas, IMF Chief Economist, told reporters, pointing to the speed at which inflation had receded as a positive surprise.

He warned, however, that geopolitical distortions could reignite price increases. Core inflation—which excludes volatile energy and food prices—isn’t quite back to the pre pandemic trend, particularly for services sector prices, he said.

IMF economists also cautioned that financial markets have been overly optimistic in anticipating early rate cuts by central banks. They project policy interest rates to remain at current levels for the U.S. Federal Reserve, the European Central Bank, and the Bank of England until the second half of 2024, before gradually declining as inflation moves closer to targets. Some investors and analysts expect a Federal Reserve rate cut in the first half of this year.

Back in Europe, Tuesday’s GDP data showed Germany was the weakest of Europe’s large economies at the end of last year, with output falling in the final quarter. However, revised figures showed it avoided a contraction in the three months through September.

“The economy remains stuck in the twilight zone between recession and stagnation,” said Carsten Brzeski, an economist at ING Bank.

While Italy’s economy expanded slightly, the French economy flatlined for the second straight quarter. Ireland, which had been a major source of growth for the eurozone over the previous decade, saw its GDP fall by 1.9% in 2023 as a pandemic-driven boom in its key pharmaceutical industry ended.

In a rare bright spot, Spain finished the year with another strong quarter and matched the U.S. growth rate over 2023 as a whole, thanks to a surge in international tourism as the last of the Covid-19 restrictions were lifted.
The top Australian super funds of 2023 revealed

Impressive share market gains in 2023 boosted the performance of Australian superannuation funds last year. All-growth super funds primarily invested in Australian and international shares delivered an outstanding 13.1 percent return, while conservative super funds containing fewer shares and more defensive assets such as bonds and cash booked a respectable 6.2 percent return.

Chant West has released its annual review of superannuation funds and revealed the top 10 performing funds among those with the median growth strategy. Super investors can choose between several types of strategies depending on their risk tolerance and stage of life. Typically, young Australians may prefer higher growth strategies because they have a longer time horizon to grow their super and can therefore tolerate more risk. Older workers closer to retirement tend to prefer balanced or conservative strategies that aim to preserve capital and deliver lower-risk gains.

Chant West revealed the performance of five different fund strategies common among Australian superannuation funds. All–growth super funds, which comprise 96 to 100 percent growth assets such as shares, delivered a median 13.1 return for investors. High-growth super funds with 81 to 95 percent growth assets delivered an 11.4 percent return. Median growth funds with 61 to 80 percent growth assets delivered 9.9 percent. Balanced funds with 41 to 60 percent growth assets returned 8.1 percent and conservative funds with 21 to 40 percent growth assets returned 6.2 percent.

Chant West senior investment research manager Mano Mohankumar said share markets in Australia and overseas performed well in 2023 and this was the biggest factor in super funds’ gains last year.

Mr Mohankumar said: “International shares was the standout asset class with a tremendous 23 percent return over the year, led by the tech sector which benefitted from advancements in AI. While Australian shares didn’t reach the same level, it still delivered a healthy 12.1percent over the same period.”

Share market returns include share price growth or capital gains, as well as dividends. Defensive assets also provided solid returns last year, with Australian bonds delivering 5.1 percent, international bonds 5.3 percent and cash 3.9 percent.

The top 10 median growth super funds are listed below, with the returns shown being net of investment fees and taxes but before administration fees and financial advisor commissions.

1. Mine Super Growth (11.8 percent)
2. Vision Super Balanced Growth (11.7 percent)
3. IOOF Balanced Investor Trust (11.2 percent)
4. Aware Super Balanced (11 percent)
5. TWUSUPER Balanced (MySuper) (10.6 percent)
6. HESTA Balanced Growth (10.5 percent)
7. Brighter Super MySuper​ (10.4 percent)
8. UniSuper Balanced (10.3 percent)
9. Prime Super MySuper (10.3 percent)
10. Australian Retirement Trust – Super Savings Balanced (10.2 percent).

Chant West said the 9.9 percent delivered by median growth funds erased their 4.6 percent loss in 2022. That was the first year in 11 years that median growth funds recorded a fall in value. Mr Mohankumar said super funds had proven their resilience and robustness, particularly during recent years amid a once-in-a-century pandemic, rapidly rising interest rates and a global economic slowdown.

He pointed out that over the long term, Australian super funds have delivered above-target outcomes. He said the typical long-term objective for growth funds is to beat inflation by 3.5 percent per annum, which translates to just over 6 percent returns. “Since the introduction of compulsory super, the annualised return is 7.9 percent and the annual CPI increase is 2.7 percent, giving a real return of 5.2 percent per annum – well above that 3.5percent target,” he said.

“Even looking at the past 20 years, which includes three major share market downturns – the GFC in 2007-2009, COVID-19 in 2020 and the high inflation and rising interest rates in 2022 – super funds have returned 7.3 percent per annum, which is still comfortably ahead of the typical objective.”

China’s Wobbles Could Throw the Global Economy Off Its Axis

About the author: Desmond Lachman is a senior fellow at the American Enterprise Institute. He was previously a deputy director in the International Monetary Fund’s Policy Development and Review Department and the chief emerging market economic strategist at Salomon Smith Barney.

Today, a Hong Kong court ordered the liquidation of Evergrande, a Chinese company that was one of the world’s largest property developers. After years of fruitless negotiations between the company and its creditors over the restructuring of its $300 billion debt mountain, a Chinese court said that “enough was enough.” In a blow to an already troubled Chinese housing market, it ordered that the company’s assets be liquidated to pay back its creditors.

How mainland China handles Hong Kong’s court order could have major implications for Chinese property prices and foreign investor confidence. If it enforces the court’s order, that could see an acceleration in Chinese home-price declines by adding to supply in an already glutted market. It could also heighten social tensions by disappointing around 1.5 million Chinese households who have put down large deposits for homes that are yet to be completed.

If it ignores the Hong Kong court’s order, it risks dealing a further blow to waning investor confidence. Questions would arise about China’s willingness to abide by the rule of law and to offer a safe economic environment for investors.

The Evergrande liquidation comes at an awkward time for the Chinese economy. It is already in deep trouble and could be headed for a Japanese-style lost economic decade. The news also suggests that China will disappoint the consensus view that the Chinese economy is headed for only a minor economic slowdown this year. This could have major implications for the U.S. and world economic outlook, considering that China is the world’s second-largest economy and until recently was its main engine of economic growth.

Even before Evergrande’s liquidation order, a whole set of indicators suggested that the former Chinese economic growth model was dead. Chinese home prices have been falling for more than a year; both wholesale and consumer prices have been falling; stock prices have plummeted as foreign investors have taken fright; and youth unemployment has risen to around 20%.

There have also been questions about President Xi Jinping’s economic stewardship. First, his disastrous zero-tolerance Covid policy contributed to the country’s slowest economic growth in 30 years. Now his increased economic intervention is undermining the underpinnings of the Chinese economic growth miracle unleashed by Deng Xiaoping’s economic reforms in the 1980s.

Chinese stocks rose last week on news that authorities are taking steps to stimulate the economy. But anyone thinking that the Chinese economy will respond favourably to yet another round of policy stimulus has not been paying attention to the size of that country’s housing and credit market bubble that has now burst. Nor have they been paying attention to the troubling degree to which that country’s economy has become unbalanced.

According to Harvard’s Ken Rogoff, the Chinese property market now accounts for almost 30% of that country’s GDP. That is around 50% more than that in most developed economies. Meanwhile, over the past decade Chinese credit to its non financial private sector expanded by 100% of GDP, according to the Bank for International Settlements. That is a larger rate of credit expansion than that which preceded Japan’s lost economic decade in the 1990s and that which preceded the 2008 bursting of the U.S. subprime and housing market.

The overall Chinese economy is highly unbalanced in the sense that it has become overly reliant on investment demand. The Chinese investment-to-GDP ratio is over 40%, according to the Organization for Economic Cooperation and Development. That’s sharply higher than the more normal 25% ratio in most other developed and mid-sized emerging market economies.

The consensus forecast is that Chinese economic growth this year will continue at a 5% clip. Anyone relying on that forecast should reflect on the many failures by the U.S. Federal Reserve and other central bankers to foresee the grave problems of the subprime housing market in the U.S. in early 2008. It would seem that most economists are downplaying indications of major Chinese economic problems that are plain sight. Chinese economic problems could unleash serious deflationary forces for the U.S. and global economy. The Federal Reserve would be ignoring them at its peril.

Guest commentaries like this one are written by authors outside the Barron’s and MarketWatch newsroom. They reflect the perspective and opinions of the authors.

Costumes and Props From ‘The Crown’ Head to Auction

Fans of The Crown will soon have the opportunity to own a piece of the royal drama as Bonhams is auctioning off a range of items from the Netflix series, which ended its six-season run in December.

More than 300 lots are currently available for online bidding through Feb. 8, and an additional 160 will go under the hammer during a live sale at Bonhams’ London headquarters on Feb. 7.

Since its debut in late 2016, The Crown has captivated viewers around the world with its visually stunning approach and dramatic portrayal of the British royal family’s tales of heartbreak. Throughout the show’s 60 episodes, viewers followed the twists and turns of the royals.

“The iconic costumes, props, and set pieces from The Crown are extensively researched and made with truly impressive attention to detail by master craftspeople,” Charlie Thomas, Bonhams U.K. group director for house sales and private and iconic collections, said in a statement. “Not only is this an incredible opportunity to own pieces from the landmark show, it is also the closest anyone can come to owning the real thing—be it the facade of 10 Downing Street or Princess Diana’s engagement ring.”

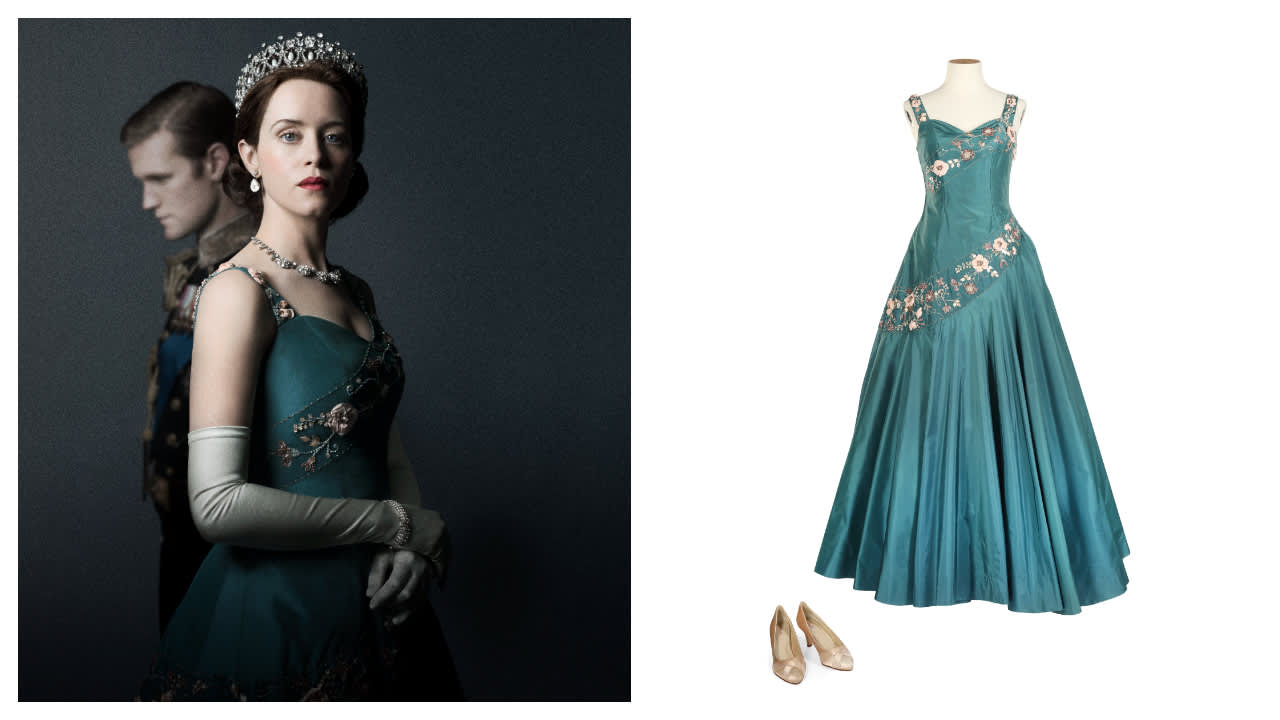
Claire Foy (as The Queen): Full-length teal ballgown, featured in the promotional poster (© Netflix 2020, Inc.) and pale gold satin pointed heels. Season 2 Episode 1 and Episode 4. Estimate: £3,000-5,000
Composite: Courtesy of Bonhams / Netflix

Highlights of the auction include recreations of Princess Diana’s iconic items, such as the sapphire engagement ring that actress Emma Corrin debuted as Diana in season 4 (presale estimate: £2,000 (US$2,537) to £3,000); the revenge dress actress Elizabeth Debicki wore as Diana during her split from then-Prince Charles in season 5 (estimate: £8,000 to £12,000); and the leopard swimsuit Debicki sported in season 6 while on vacation during Charles’ 50th birthday party for then-Camilla Parker Bowles (estimate: £800 to £1,000).

Emma Corrin (as Lady Diana Spencer): Engagement announcement, engagement ring. Estimate: £2,000-3,000. (Film still © Netflix 2020, Inc.)
Composite: Courtesy of Bonhams / Netflix

Expected to fetch the highest prices are a pair of life-size replicas from the set: the Gold State Coach, which is estimated to sell for between £30,000 and £50,000, and a facade of 10 Downing Street, the British prime minister’s office and residence (estimate: £20,000 to £30,000).

Described by Bonhams as a “rococo masterpiece,” the actual royal coach was built in 1762 for King George III and has been used at every coronation since 1831, when King William IV succeeded to the throne.

“We wanted to make something special, and Netflix had the money, ambition, and ability to go the whole hog. The Gold State Coach is fabulous,” said Andy Harries, CEO Left Bank Pictures and executive producer of The Crown, in the auction notes.

Gene D’Cruze, the series’ head of construction, said the items for sale are among the most impressive and accurate recreations ever committed to film.

Elizabeth Debicki (as Princess Diana): The ‘Revenge dress’, custom-made off-the-shoulder black cocktail dress. Season 5 Episode 5. Estimate: £8,000-12,000. (Film still © Netflix 2020, Inc.)
Composite: Courtesy of Bonhams / Netflix

“I’ve built every single set on every series—more than 1,000 of them—and employed 140 people. It’s all done old-school. I’ve done 80 TV series, but The Crown is the best—best production, best art department, best locations, best series, best people,” said D’Cruze in the auction notes. “I especially love the 10 Downing Street facade. Most sets only last six months, but this stood for seven years.”

Proceeds from the live auction will go toward establishing a new scholarship for students at the National Film and Television School (NTFS). According to the auction house, the program will support students at the globally renowned school over the next 20 years.

“The Crown’s huge global success has much to do with working with the best creative and production talent in this country and we want to invest the proceeds of this magnificent auction into the next generation of film and TV talent,” said Harries in a statement.

A special exhibition of items from the auction has been on a global tour—having already appeared in New York, Los Angeles, and Paris—and will remain on display at Bonhams London through Feb 5.

Global Emissions From Electricity Set to Fall Even as Power Demand Climbs, IEA Predicts

Global demand for electricity is set to grow at a faster rate over the next three years, but with record power generation from renewables and nuclear expected to cover the surge, emissions will likely go into structural decline, according to the International Energy Agency.

Electricity demand is on track to rise by an average of 3.4% a year through 2026, driven by robust growth in emerging economies, AI, cryptocurrencies and data centres, according to the Paris-based organisation’s latest report. However, global carbon-dioxide emissions from power generation are expected to fall, as low-emission energy sources—wind, solar, hydro and nuclear, among others—are likely to account for almost half of the world’s electricity generation by 2026, up from just under 40% last year.

“It’s encouraging that the rapid growth of renewables and a steady expansion of nuclear power are together on course to match all the increase in global electricity demand over the next three years,” IEA’s executive director Fatih Birol said on Wednesday.

“This is largely thanks to the huge momentum behind renewables, with ever cheaper solar leading the way, and support from the important comeback of nuclear power, whose generation is set to reach a historic high by 2025.”

In 2023, global CO emissions from electricity generation increased by 1%, but the IEA predicts a fall of more than 2% this year and smaller decreases in the next two years. Generation from cleaner energy sources is expected to rise at twice the annual growth rate seen between 2018 and 2023, while coal-fired generation is forecast to fall by an average of 1.7% annually through 2026, the IEA said.

Rapid growth of renewables will be supported by nuclear power. According to the report, nuclear generation is set to rise by roughly 3% a year on average to the end of 2026, despite a number of countries phasing out nuclear power or closing plants early.

France and Japan will restart several plants while new reactors begin operating in Europe, China, India and Korea. Asia will likely remain the main driver of growth, reaching a 30% share of global nuclear generation in 2026, the IEA said.

For years, nuclear power has been at the centre of the clean-energy debate. Proponents including France argue that it is a reliable, low-carbon alternative to fossil fuels, while opponents such as Germany say costs and risks from reactor accidents and waste are too high.

At the United Nations’ COP28 climate summit last year, the U.S. and 21 other nations pledged to triple nuclear power capacity by the middle of the century.

Most of the increase in electricity demand forecast by the IEA is set to come from emerging markets. China is expected to be the largest contributor to growth—with consumption boosted by the production of solar PV modules, electric vehicles and the processing of raw materials—while India is forecast to grow the fastest among major economies.

Rapid expansion of artificial intelligence, data centres and cryptocurrencies will also be a driver of growth, according to the agency, which predicts their power demand could double to roughly the equivalent of electricity consumption in Japan.

Last year, electricity demand growth slowed to 2.2% from 2.4% in 2022, as advanced economies suffered the impact of high inflation and lower industrial output, the IEA said.

Demand in the U.S. decreased by 1.6% after rising 2.6% in 2022, mainly because milder weather reduced the use of heaters and coolers, but demand is expected to recover this year to 2026. European Union power demand declined for the second consecutive year in 2023—despite a fall in energy prices—and isn’t expected to return to high levels until 2026 at the earliest, the IEA said.

Why Introverted Leaders Are Ideal for the Post pandemic Workplace

Leigh Thompson is the J. Jay Gerber Professor of Dispute Resolution and Organizations and a director of executive-education programs at Northwestern University’s Kellogg School of Management. She is the author of several books, including “Negotiating the Sweet Spot: The Art of Leaving Nothing on the Table.”

I’m an extrovert and I admit I’ve benefited from it.

Outgoing people are more likely to be noticed, selected as leaders and awarded “halo” traits—meaning that other people just assume extroverts are more likeable, intelligent and have other positive qualities. But as a social scientist, I can’t ignore the research: Most of these beliefs about extroverts simply aren’t true.

Studies show that introverts and extroverts are equally effective in academic and corporate environments, and that there is no actual relation between CEO charisma and firm performance.

Yet the misconceptions about extroverts persist, making them more likely to be chosen as leaders over their more introverted peers. That’s unfortunate because in our post pandemic world, replete with remote work, hybrid communication, far-flung team members, artificial intelligence and global disruption, introverts are particularly well-equipped to lead.

That may be hard to believe because of two persistent myths.

First is the widely held stereotype that effective leaders are gregarious, alpha and comfortable in the spotlight, even craving that attention. In reality, the social skills that extroverts display aren’t necessarily predictive of capable leadership.

Second is the belief that quieter people lack leadership skills. They are seen as less social, unassertive, sad and disconnected. Indeed, in a recent study in which people in different groups were instructed to “act like an extrovert” or “act like an introvert” regardless of their actual personalities, those who acted extroverted were disproportionately selected for leadership. And, interestingly, those who pretended to be introverted in that study reported feeling sad.

Both of these myths ignore the reality that introversion, far from being simply a lack of extroversion, is a distinct set of traits with its own large merits. This was true well before the pandemic, but the remote-work environment illuminated the bias even more and highlighted the need to change our perceptions.

Here are five reasons why introverts could be ideal leaders in the redefined workplace.

1. Remote-work performance. Extroverts’ job performance declined when the pandemic forced many businesses to go remote. A study of remote workers found that extroverted employees became less productive, less engaged and less satisfied with their jobs. A separate study found that team average extroversion had a large negative effective on team performance—that is, the more extroverted the team members were as a group, the worse they performed.

2. Dealing with adversity and change. Introverts show a greater capacity to engage, think through and make wise choices during periods of adversity and change. A recent investigation found that introverts had more positive attitudes toward AI and using AI overall than did extroverts. A separate study found that during periods of high conflict, extroverts develop fewer energising relationships with their teammates and aren’t viewed as proactively contributing to the team. Introverts, however, often possess a predisposition for things like empathy and thoughtful communication—all critical for navigating team dynamics and conflict in tough times.

3. Creativity. Introverts’ creativity flows well in the quiet aftermath of group interactions, positioning them as formidable leaders for innovative and reflective tasks. In studies of communication and conflict, introverts’ tendency to think before speaking was seen to yield more creative solutions.

4. Avoiding avoidance. Most humans approach positive things and avoid negative things. Sounds like a good policy—unless we’re talking about workplace challenges. Research has shown that extroverts commit more passive avoidance errors—that is, when the going gets tough, they tend to avoid the situation altogether; meanwhile introverts are more likely to inspect the half-empty glass or the disappointing customer-satisfaction data, generating insights and solutions.

5. Resilience against quitting. A study of over 200 people revealed a correlation between extroversion and burnout—that is, the more extroverted a person reported themselves to be, the more likely they were to burn out. Introversion, on the other hand, was uncorrelated with burnout, suggesting better immunity.

Well Into Adulthood and Still Getting Money From Their Parents

Parents have always supported their children into adulthood, from funding weddings to buying a home. Now the financial umbilical cord extends much later into adulthood.

About 59% of parents said they helped their young adult children financially in the past year, according to a report released Thursday by the Pew Research Center that focused on adults under age 35. (This question hadn’t been asked in prior surveys.) More young adults are also living with their parents. Among adults under age 25, 57% live with their parents, up from 53% in 1993.

Parental support is continuing later in life because younger people now take longer to reach many adult milestones—and getting there is more expensive than it has been for past generations, economists and researchers said. There is also a larger wealth gap between older Americans and younger ones, giving some parents more means and reason to help. In short, adulthood no longer means moving off the parental payroll.

“That transition has gotten later and later, for a lot of different reasons. Now it’s age 25, 30, 35, 40,” said Sarah Behr, founder of Simplify Financial Planning in San Francisco.

Kami Loukipoudis, a 39-year-old director of design, and husband Adam Stojanik, a 39-year-old high-school teacher, knew they would need parental assistance to buy in New York’s expensive home market.

“We could pay a mortgage, but that down payment was the absolute crusher,” Stojanik said. “The idea of trying to save up on our own—as long as we were paying rents in NY, would’ve taken 300 years.”

Loukipoudis’s mother gave them the money for a 10% down payment on a two-bedroom apartment in the New York borough of Queens.

The young-adult allowance

Adult children aren’t necessarily getting larger checks from their parents, but they are staying on the parental payroll for longer than previous generations, according to Marla Ripoll, professor of economics at the University of Pittsburgh who studied the trend by analysing payments from parents to adult children over a 20-year span.

Ripoll found that 14% of adult children receive a transfer of money from their parents at least once in any given year, and roughly half get financial help at some point within that period. Those rates have been stable for years. What has changed is that the transfers now continue for much longer, she found. This longer-term help might be a drag on social mobility, as it becomes even harder for young people from lower-income families to catch up, researchers said.

Of the young adult children who said they received financial help from a parent in the past year, most said they put it toward day-to-day household expenses, such as phone bills and subscriptions to streaming services like Netflix, according to the Pew survey.

The amount of money and the frequency of help varies by age; those on the older end of the 18-to-34 cohort are far likelier to say they are completely financially independent from their parents compared with younger adult children, as many in the latter group are completing their education. Nearly a third of young adult children between the ages of 30 and 34 say they still get parental help.

Heather McAfee, a 33-year-old physical therapist in Austin, Texas, said she lived at home between 2019 and 2021; otherwise she wouldn’t have been able to make progress paying down her student loans while rent prices in her area remained so high. The plan worked—she has since reduced her student-debt balance from $83,000 to $15,000.

“It helped tremendously,” she said. “I didn’t have to take out more loans to pay for apartment living or anything like that. That stress was gone.”

Setting limits on financial help

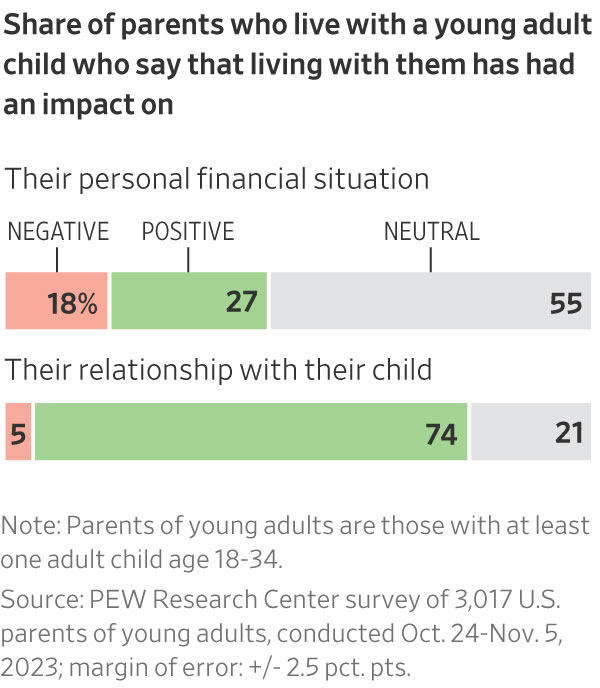
A little more than half of parents surveyed said that having their adult children home brought them closer together or improved their relationship, but nearly 20% said it dented their personal finances.

Financial advisers often find themselves in the tricky position of speaking to both ends of the equation: adult children who need assistance and the parents determined to help children well into middle age, within limits.

Whereas previous generations would step into a greater sense of financial independence in their early 20s, young adult children today are often unable to reach similar markers of such independence—living on their own or buying their first home, for example—without greater financial resources.

Families typically don’t set concrete rules around when financial help will happen and what the money is used for, which can result in surprises down the road, Behr said.

In one case, Behr’s clients received the down payment they needed to purchase a condo from a generous mother-in-law. Years later, that same mother-in-law told them she expected a payout once the couple sold the home.

The hand-me-down payment

Down-payment help from parents—a given for many first-time home buyers—is growing thanks to higher home prices and elevated mortgage rates.

About a fifth of first-time home buyers said they got help from a relative or friend when pulling together the money needed for a down payment, according to a 2023 survey of home buyers and sellers from the National Association of Realtors. And 38% of home buyers under age 30 received help with the down payment from their parents, according to a survey this spring by Redfin.

Wealthy families often go further than helping with the down payment. They become a true bank of mom and dad and write a mortgage. The Internal Revenue Service sets minimum levels of interest for such loans, which remain significantly cheaper than current mortgage rates.

Timothy Burke, chief executive at National Family Mortgage, which facilitates such loans, said parents are often frustrated on behalf of their house-hunting children. High interest rates and the cutthroat housing market are holding their children back from reaching a milestone the parents themselves were more easily able to access.

Mei Chao, a 41-year-old stay-at-home mom, and her husband, William Chao, a 44-year-old information-technology specialist, bought their first house as a couple in 2017. They relied on financial help from her husband’s two sisters and his mother to help them bridge a gap in their house-buying timeline. While they waited to sell William’s Manhattan condo, they used the money from the family to purchase the new house in Queens.

The structure of the agreements got tricky. After selling the condo in Manhattan, Mei and her husband were able to repay his sisters in full. But they didn’t have enough money left over from the sale to do the same for Mei’s mother-in-law. So they kept the mother-in-law’s name on the deed to the house—a concession Mei said they were both more than happy to make.

“Ultimately, it all worked out. I’m glad his mother pushed us,” Mei said. “Without her help, I could not say we would have this home.”

Inside the $800,000 Experiment to Turn a Frank Lloyd Wright Into a Net-Zero Energy Home

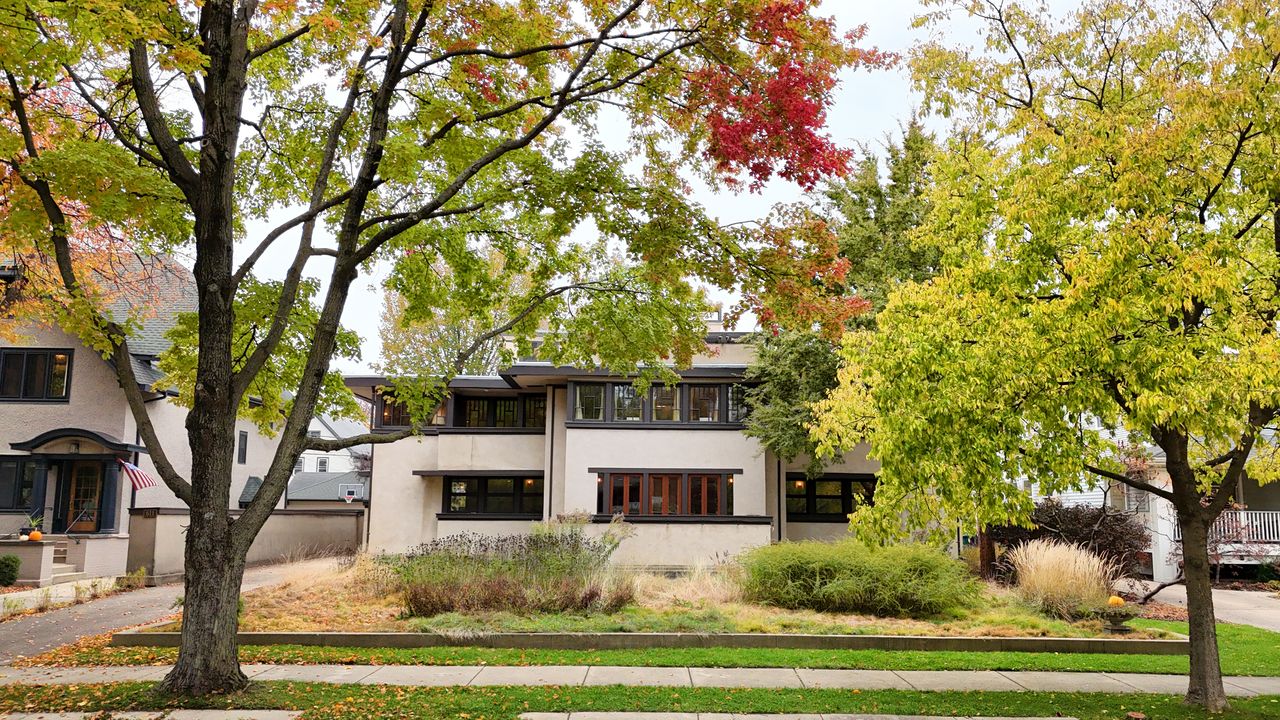
“I was not planning to buy a Frank Lloyd Wright house,” says Samantha Lotti, who grew up in a Manhattan apartment, studied at the University of Chicago, and then spent five post-college years running her family’s farm in Tuscany. So in 2016, when she heard that the Oscar B. Balch House, one of more than two dozen Wright buildings in Oak Park, Ill., was for sale, she was only vaguely interested. But she did go look. And when she entered the main living space of the 1911 prairie-style house, which is named for its first owner, she says, “I fell in love.” Among the things that moved her were the size of the windows and the proportions of the rooms. The ceilings are low, “almost compressive,” she says, “which is intended to force you to engage with what’s outside the house. And, thanks to the windows, you feel like you’re outside when you’re inside.”

Within weeks, she was in contract to buy the house for $1,126,800, about 10% below asking, which, to a New Yorker, seemed like a bargain. The house had a lot going for it. It is part of a gracious neighbourhood of historic residences, including Wright’s own Home and Studio. And it was in excellent condition, thanks to its previous owner, Tim Pearson, an accountant and construction company executive, who between 1999 and 2016 restored much of the original building while adding a very large kitchen and great room to the back of it. That increased the house’s size to 4,400 square feet without altering its symmetrical front elevation. Though the house is closely watched by Wright enthusiasts, the only parts of it with legal protection are two spectacular Wright-designed glass light fixtures that Pearson deeded to the Frank Lloyd Wright Building Conservancy. Lotti, 39, jokes that she could gut the entire house as long as she didn’t touch the fixtures.

But she’s not about to gut anything. Every morning, Lotti says, “I wake up in a work of art.”

Though not a very energy-efficient work of art. Its 49 single-paned windows, many with bits of coloured glass in abstract patterns, provided little insulation. Nor was there much insulation in the walls and roof. During a “polar vortex” in 2019, Lotti, who practices Chinese medicine in Oak Park, ran the gas-fired boiler-and-radiator heating system at full blast, and still couldn’t get the indoor temperature above 55 degrees. Air conditioning the house in summer was equally difficult. “It was so expensive,” she says. “At night I’d turn it on only if it was 90-plus degrees.” Lotti was disturbed not just as a homeowner paying the utility bills, but also as an environmentalist. So she set out to make the Wright house green. She hoped it could even reach “net zero,” meaning it produced as much energy as it consumed. Like most users of the phrase net zero, she didn’t count, on the consumption side, the energy that went into building and renovating the house, known as embodied energy.

“It is extremely unusual to do a historic restoration that is so environmentally focused,” says Marsha Shyer, who chairs the homeowner committee of the Frank Lloyd Wright Building Conservancy. Owners of historic houses often simply live with inefficiency as the price of authenticity.

Getting to net-zero would mean tightening the building envelope to reduce the need for heating and air conditioning. She began with the roof, which not only leaked when it rained but was also far from airtight. Redoing it cost about $55,000, which, Lotti says, is more than she would have paid if she had hired an ordinary contractor. Instead, she chose one who specialises in historic preservation. “You always have to go up a level for Frank Lloyd Wright,” she says. That’s true even though the roof, which is flat, is visible only from above.

Next she had to insulate the space below the roof. That meant tearing out the original second-floor ceiling, which gave Lotti a chance to solve another problem: The flexible ductwork over the house’s bedrooms rattled when the air conditioning was on. Lotti decided to install new, rigid ductwork for both heating and cooling. Once the ductwork was in place, it was time to fill the remaining ceiling cavities with insulation. Until recently, blow-in insulation often contained HFCs (hydrofluorocarbons) that emitted greenhouse gases far more damaging to the environment than CO2. Instead, Lotti’s contractor used recently developed hydrofluoro olefin (HFO) spray foams, which are far less greenhouse gas-intensive.

Then it was time to restore the second floor ceilings, which had a sandy finish specified by Wright. To Lotti’s surprise, rebuilding the ceilings and giving them just the right texture cost about $50,000.

The other big contribution to making the house tighter was insulating its 49 single-pane windows. After speaking to contractors and preservationists about how to best achieve that, she decided to install interior storm windows. A carpenter spent months during the pandemic making pine-framed storm windows for a house where no two windows were precisely the same size (mostly due to settling). The storm windows are stunningly well-made; they are barely visible from inside or outside the house. Lotti spent $142,000 on those and other window and door restorations.

Then came the biggest job of all: replacing her gas-burning furnace and water heater with a geothermal system. That involved drilling six 450-foot holes in the front yard, running pipes into and out of the holes, then surrounding the pipes with charcoal, a good conductor of heat, bentonite, a kind of clay that expands as it dries, and sand. Water circulating through the pipes reaches a temperature of about 59 degrees. From there, just a bit of energy is needed to make it slightly hotter, for heating, or colder, for air conditioning. Digging the geothermal wells, running the pipes through them, and connecting those pipes to the forced-air system cost about $64,000, which was reduced by a 26% Illinois rebate. Lotti had to redo part of the basement floor ($29,000) to support the manifolds, which connect the geothermal wells to the house’s heating and cooling systems, as well as three big water-storage tanks, two bilge pumps, and other new equipment ($49,000). It cost $132,000 to add ductwork throughout the house—allowing for forced air heating and cooling. Electrical wiring for the system was another $26,000. Altogether, the heating and air conditioning improvements—from geothermal wells to ductwork—cost about $300,000.

Installing the geothermal system means Lotti no longer uses gas to heat the house, but it didn’t lower her electric bill. “It takes electricity to pump the water down 450 feet and back up 450 feet,” she says.

Lotti also took on several projects purely for aesthetic reasons, such as repainting the Greek key motif on the house’s exterior in its original grey colour. Another improvement was sybaritic: Lotti turned an enclosed porch on the back of the second floor into a sauna. Pearson had laid the groundwork for that and other nonessential projects.“ It’s because of him that I could do what I did,” Lotti says.

Before the renovation began, Lotti subjected the house to a blower door test, which measures the permeability of the building envelope. She performed another one almost three years later. The goal, she says, was to see if installing custom interior storm windows, insulating the second-floor ceilings and replacing the roof made the house tighter. It did, but not enough. “We failed,” says Lotti, “but we came much closer to passing than before.” The house still leaked like a sieve, mostly through the exterior walls. But the cost of insulating those walls, she says, was “prohibitive.” As a result, she says, “The house may never be net zero.”

Installing rooftop solar panels would have helped the house meet that goal. But she couldn’t have installed the solar panels while the roof and the ceiling (including the new ductwork) were being repaired. Once the ductwork was in place it made sense to complete the geothermal system. Then, when it was finally time to install the solar panels, workers had been in and out of the house nearly every day for three years. Lotti decided she needed a break.

She still hopes to install the solar panels, which, she believes, will cost about $27,000 before tax rebates. She expects utility bill savings would defray that cost over a period of years.

Altogether, Lotti spent about $800,000 on the house, a figure that includes engineering and site management fees and the cost of replacing a sewer line that broke when the geothermal wells were being dug.

So what had she accomplished? She had made the house all electric, with the exceptions of her two wood-burning fireplaces. An all-electric house has the potential to operate with almost no carbon emissions. It just takes a clean source of electricity, like the solar panels she hopes to install on the roof. Lotti also gained a lot of experience, which Shyer, herself the owner of a Frank Lloyd Wright house, has chronicled on the website of the Frank Lloyd Wright Building Conservancy, savewright.org. Says Shyer, “Samantha is using her house as a model for environmentally conscious historic preservation. It has certainly caught the attention of the Frank Lloyd Wright homeowner community.”

Lotti herself has chronicled her efforts in a series of highly informative Instagram posts. Looking back on the three years she dedicated to upgrading the house, she says, “We discovered what was possible, which is that the house could become significantly more energy efficient.” She adds, “Just like in medicine, we experiment. We come up with an idea that we think is going to be a solution, and then we discover that it isn’t. Humanity is all about trial and error. You don’t know unless you try.”

Frugal and proud of it: how ‘loud budgeting’ became cool

Young Australians are embracing global ‘cash conscious’ trends popularised via social media to proudly cut back on increasingly expensive non-essential items, not only to cope with the cost-of-living crisis but also to prioritise saving and reduce debt while interest rates are high. A consumer sentiment survey conducted by National Australia Bank (NAB) revealed a 24 percent annual increase in the number of NAB Reward Saver accounts opened by Gen Z customers and an average 5.3 percent growth in their account balances over the past 12 months.

On average, NAB says their Gen Z customers are saving $450 per month by cutting back on spending, with 56 percent putting spare dollars into high interest savings accounts or mortgage offset accounts. Young people are saving an average of $124 per month by not eating at restaurants, $96 per month by not using food delivery services and $73 per month by skipping coffees, snacks and café lunches. They are also saving an average of $70 per month on petrol by using their cars less frequently, $64 per month by foregoing entertainment and $30 per month by quitting streaming services.

NAB Personal Banking executive Paul Riley said: “In 2024, being ‘cash conscious’ is officially cool … ‘Loud budgeting’ is all about unapologetically prioritising your own financial goals, setting smart boundaries on spending, and feeling comfortable to talk about it openly and authentically. Rather than going out for an expensive dinner with friends, younger Australians are confidently opting to stay in and choose to put that amount into a high interest savings account or pay down debt.

“The other hot budgeting trend is ‘no or low spending months’ which involve giving up alcohol, takeaway food or shopping for clothes or beauty for the month, not booking holidays, food prepping or bringing your lunch to work or finally asking mates to repay cash you’re owed,” Mr Riley said.

Maya McIntyre, 23, is putting an extra $250 into a high interest savings account each month.

“I’m definitely making some changes to what I’m spending money on and I’ve cut back on things like streaming subscriptions, I’m eating out less and I’m choosing cheaper or free things to do with friends rather than expensive meals and pub visits,” Ms McIntyre said. “Most of my friends are making some changes to the way we think about our finances and some of us are definitely more open to saying ‘no’ to things if we feel like we want to save money instead.”

Since mid-2023, NAB has seen a 62 percent increase in the number of customers using its personalised spending feature available on the NAB app and internet banking. This automatically categorises transaction data to help customers easily identify where their money is going. Categories include subscriptions, memberships, gym and health, insurance and supermarket spending.

The sports lover’s trip of a lifetime

Imagine being at the centre of the world’s best football and basketball action in the most famous and exclusive sporting venues in the world. Now imagine sharing it with a group of like-minded mates.

It’s the stuff that dreams are made of.

Golden Tickit’s USA Sports Experience offers a once-in-a-lifetime chance for exclusive access to NFL, NBA and NRL experiences – all in amazing Las Vegas.

The package kicks off with an exclusive private tour of SoFi Stadium, hosted by the LA Rams where guests will enjoy all the behind the scenes action of one of the best sporting stadiums in the world.

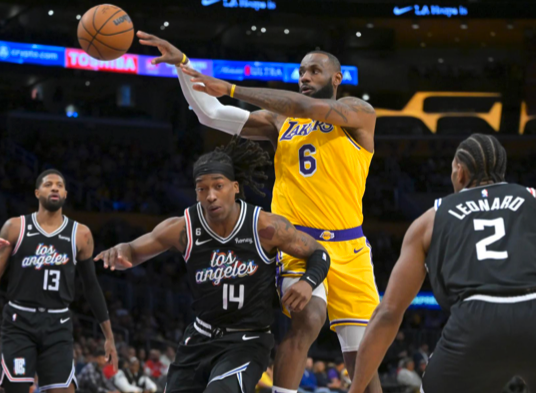
As if that’s not enough, catch the LA Lakers vs the La Clippers at Crypto.com Arena with exclusive pre-game court-side access to watch both teams warm up.

Catch the LA Lakers and LA Clippers court-side in a private pre-game warm-uo

Rounding out the trio of events, enjoy fully catered seats in an Owner’s Club Suite at Allegiant Stadium for the double header of the NRL season opener.

This ultimate experience also includes premium accommodation, with one night at the Ritz Carlton in Los Angeles and three nights at the Encore at Wynn, Las Vegas.

What happens in Vegas…is unforgettable in Vegas

For sports enthusiasts, it’s an opportunity not to be missed. And it’s one even better when shared with friends.

Priced at $8,990, the event runs from February 28 to March 3. Flights can be booked at an additional cost.

See more information at Golden Tickit or email tim@goldentickit.com.au

Offer exclusive to Kanebridge News

A New U.K. Race Car Boasts Zero to 60 in 1.4 Seconds. And You Can Buy One in the U.S. Next Year.

The fastest cars you can buy are all electric. Cars with zero-to-60 times under two seconds are the Rimac Nevera and its close relative the Pininfarina Battista, the Tesla Model S Plaid Edition, and the Lucid Air Sapphire.

Now, add one more: the British-made McMurtry Spéirling. At a Silverstone track event in December, Mat Watson of the YouTube channel Carwows drove the electric, rear-wheel drive Spéirling PURE model to 60 miles an hour in 1.4 seconds, with zero to 100 in 2.63 and a quarter mile in 7.97. The PURE is a racer in an edition of 100, but McMurtry said it will eventually be producing a street-legal version.

The price in the U.K. for the handmade PURE is £895,000, and in the U.S. around US$1 million. McMurtry Automotive was founded in 2016 and based in England’s posh Cotswolds region of Gloucestershire. Managing Director Thomas Yates comes from Formula 1, and the company’s focus is on race-bred technology. Testing, in secret, occurred in the U.K. at tracks such as Castle Combe and Donington Park. The first reveal to the public was at the Goodwood Festival of Speed in 2021, with racers Derek Bell and Alex Summers giving demonstration runs. The next year, the PURE set a hill climb record at Goodwood (going up in 39.08 seconds).

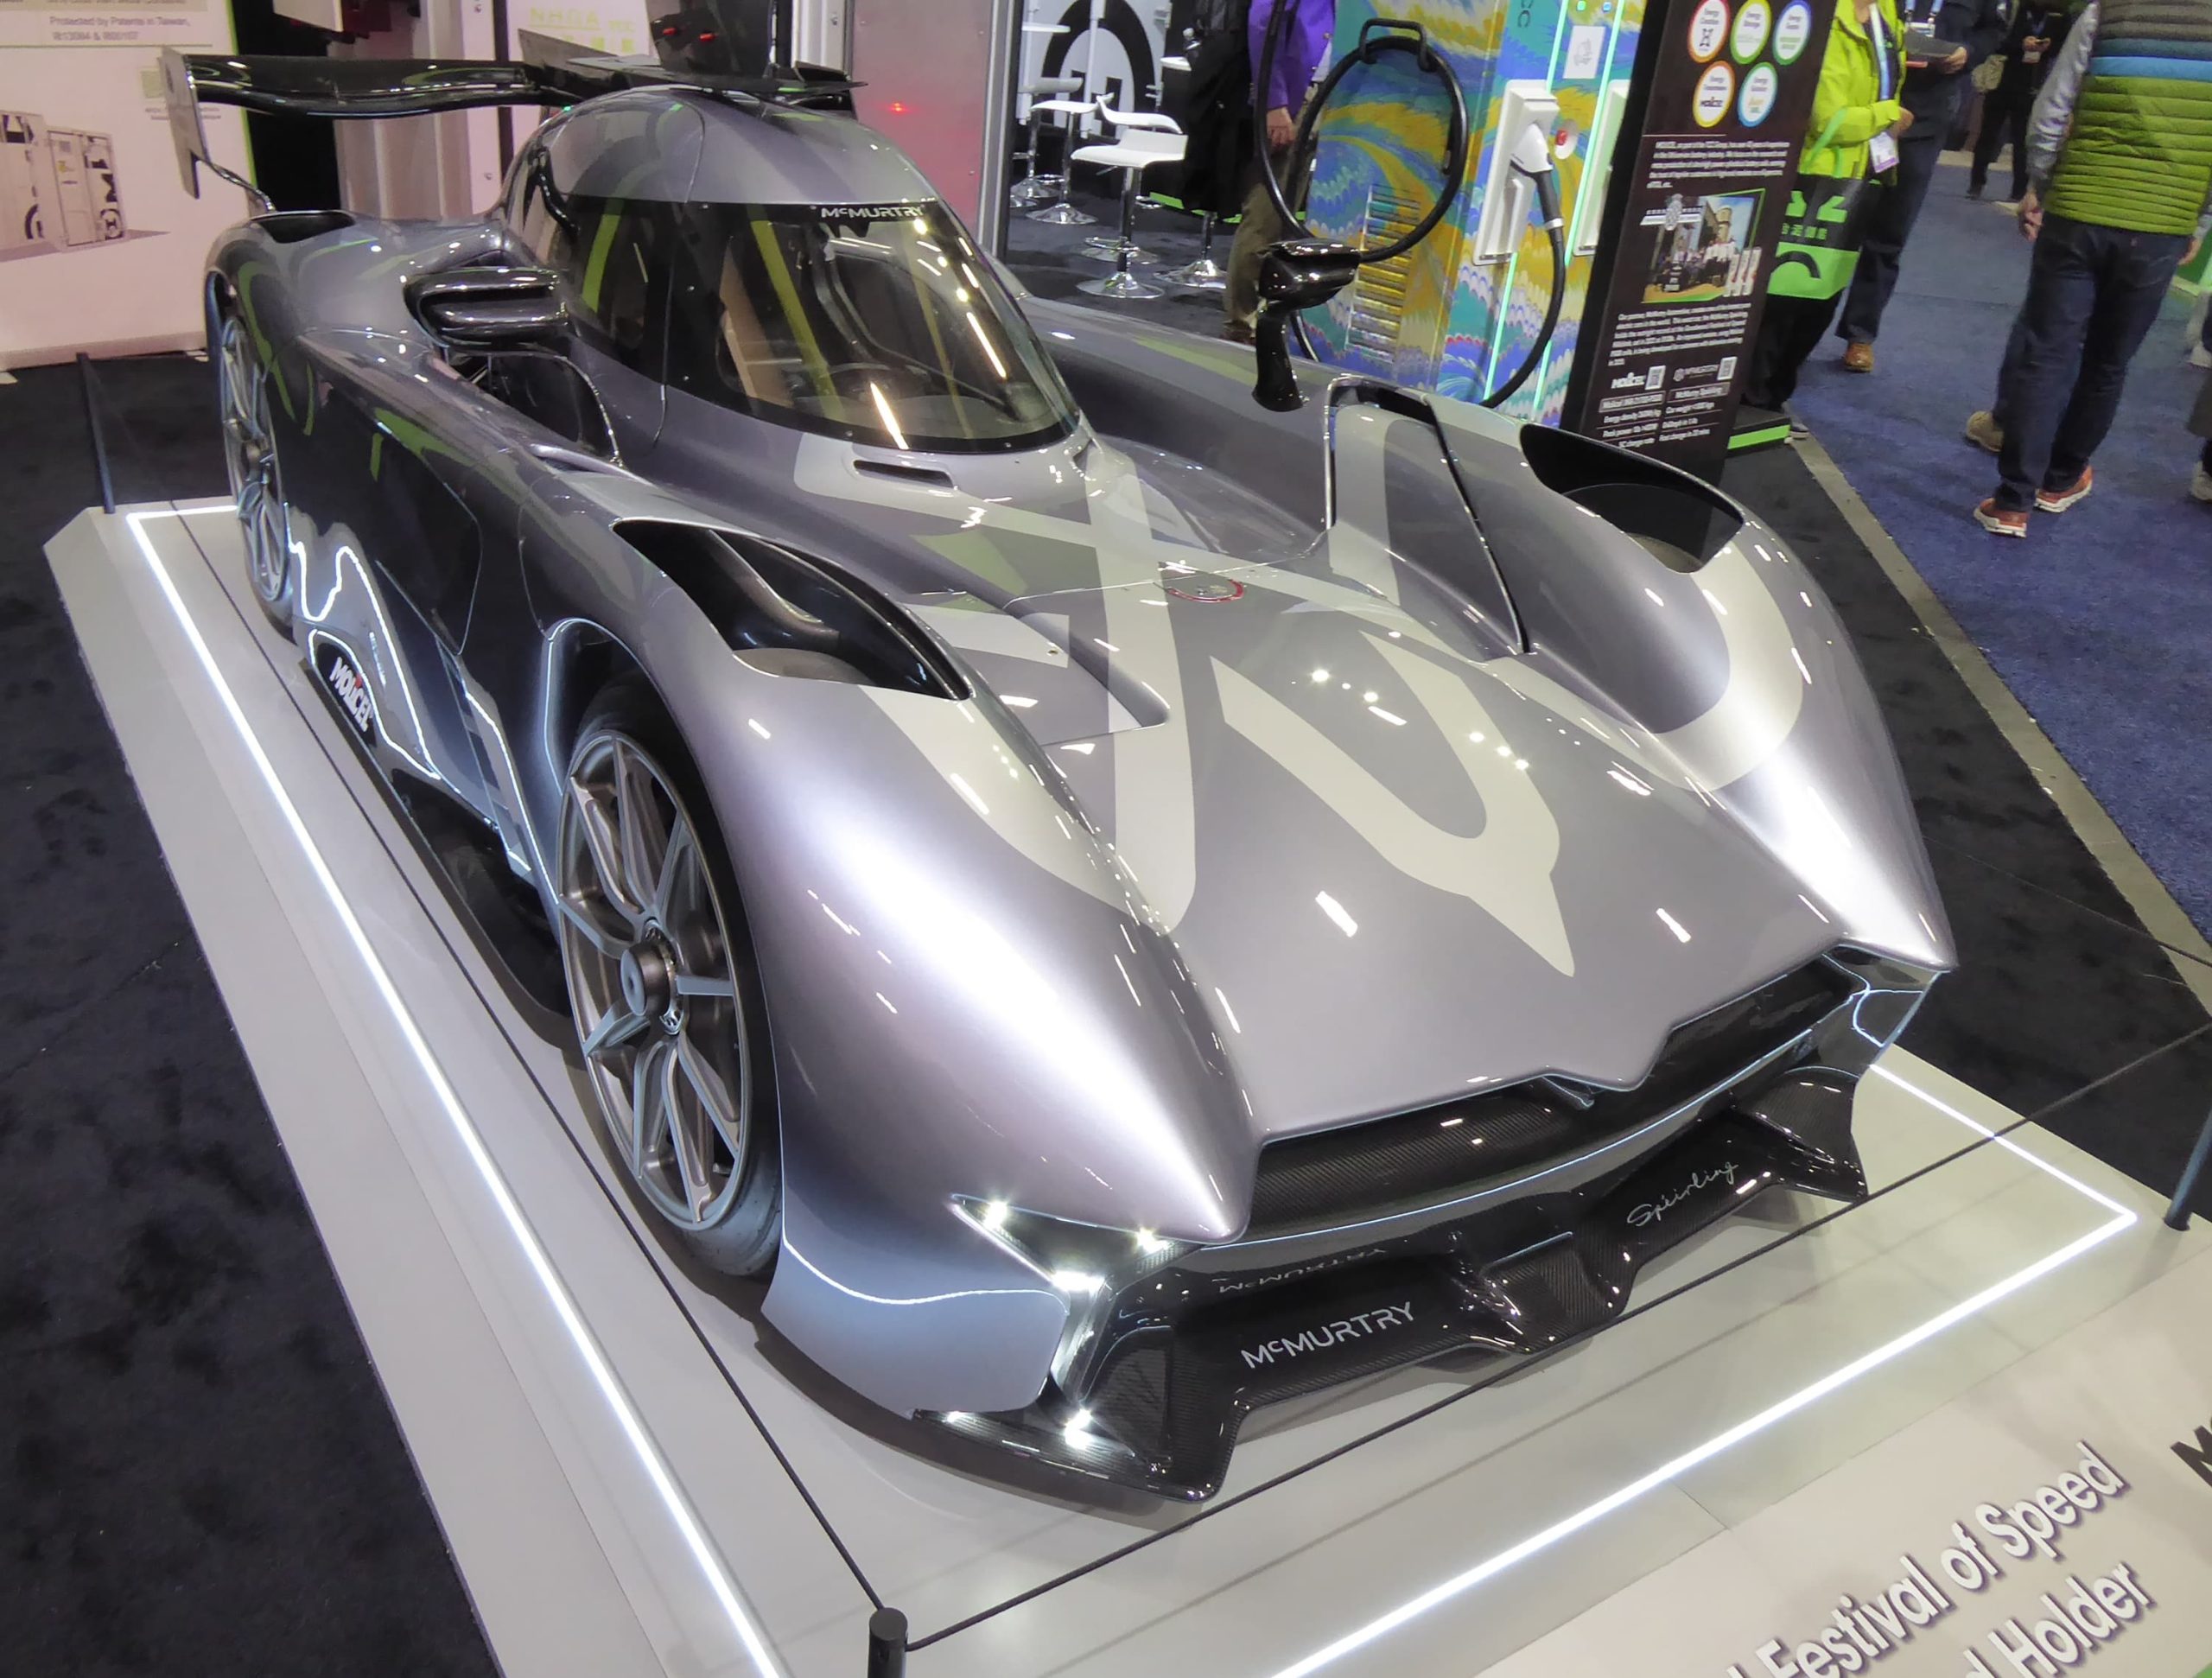
Miller Motorcars of Greenwich, Connecticut, which also handles Ferrari, Bugatti, Maserati, Rolls-Royce, and other luxury brands, announced it was taking on McMurtry in January. The record-breaking car was shown by its battery supplier at CES in Las Vegas earlier this month, but will also be making an appearance in Greenwich, with an open house Feb. 3. The West Coast dealer is O’Gara Motorsport, and the star car was in California at Thermal Raceway earlier this month for a demonstration.

The record-setting McMurtry Spéirling PURE on display at CES this year.
Jim Motavalli

Evan Cygler, director of special projects at Miller, tells Penta he was “completely dumbfounded” to encounter the rear-wheel drive McMurtry PURE in England. “They purposely came out with a finished car at Goodwood to break a record, and achieved the goal,” Cygler says. “The sound of it is incredible, as is the tiny size. We are passionate about our business, so we told them that if there was an opportunity to sell these cars, we’d love to be involved.”

Miller will support these track-only cars with its own track days at Connecticut’s Lime Rock Park, Cygler says. “It is less than two hours away and a fun place to host our customers for a day,” he says. “The Spéirling PURE is a cool weekend racer, and definitely something different. Whether you are into EV products or not, you have to love this.” Miller expects to get one or two PURE cars in 2025, he added. McMurtry will also host customers at private track events in the U.K.

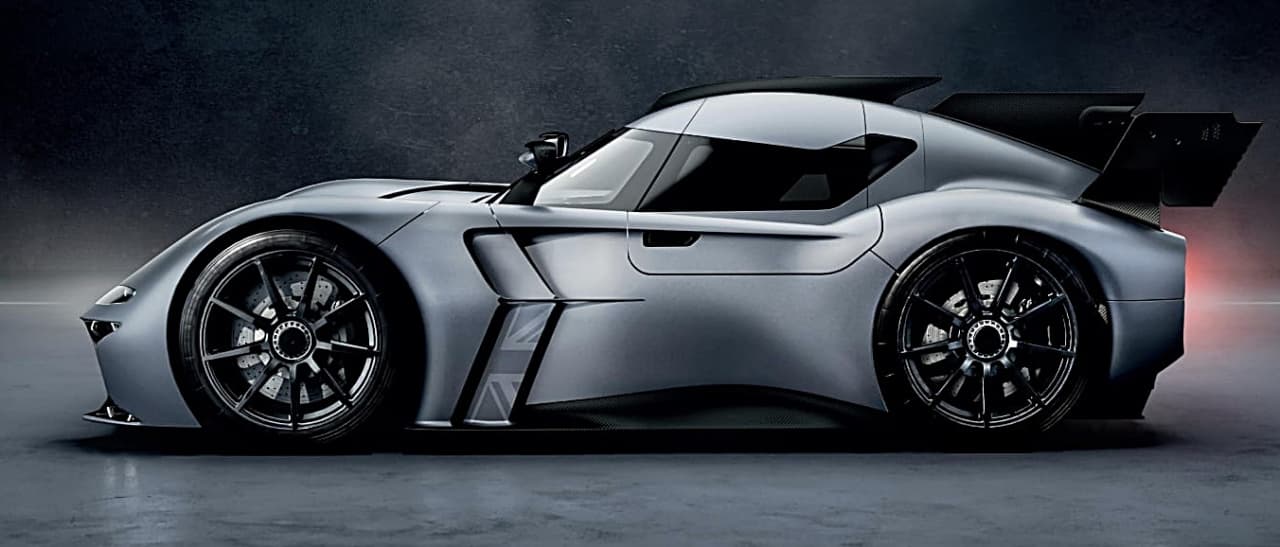
The Spéirling reportedly offers 1,000 horsepower and 1,033 pound-feet of torque from two electric motors. Keeping it on the track are a pair of huge turbines (adapted from Formula 1 and Can Am) located behind the single occupant that extract air from under the car and produce more than 4,000 pounds of downforce. The battery is relatively small at 60 kilowatt-hours, but the carbon fiber-bodied car is so light at approximately 2,200 pounds that it has an estimated 300 miles of range (driven lightly, and on the forgiving European WLTP cycle). Top speed is around 200 mph.

The battery pack in the PURE prototype uses Molicel cells that can fast charge in 20 minutes, with rapid cell cooling. A charge can get the car around Silverstone track for 10 laps. Customer cars will use next-generation cells that are still in development.

The cockpit of the Spéirling PURE is a tight fit, and entry is made easier by a removable steering wheel. The single occupant sits on the rear fender and swings his or her body through the narrow opening, then drops into place. It’s a racer’s view forward, with no infotainment or anything else extraneous to ultra-high-speed driving. The Spéirling PURE may not be useful for getting groceries, but it offers the ultimate acceleration experience.

The Australian home sector outperforming the rest

Luxury houses have experienced a far stronger rate of capital growth than the rest of the market over the past 10 years, according to a historical analysis by Australia’s largest agency network, Ray White. Family houses at the median price point have increased by 78 percent in value over the past decade, while prestige houses priced within the top five percent of homes have doubled in value.

Ray White chief economist Nerida Conisbee said land was a large component of prestige homes’ value and this created stronger rates of capital growth.

“There are only so many properties you can build in our most expensive suburbs, which tend to be located close to beaches, bays and rivers,” Ms Conisbee said. “Anything with even more unique characteristics that are hard to replicate, such as a view or close proximity to the water, are likely to have increased even further.”

Strong renovation activity during and after the pandemic accelerated capital growth.

“Luxury homes have become even more expensive over time as more investment has taken place,” Ms Conisbee said. “And while it is not possible to measure, it is likely a higher proportion of well-located luxury homes have been renovated than the rest of the market and almost certainly true that more has been spent on them.”

Luxury apartments have also grown in value at a much higher rate than average units. Ms Conisbee said this indicated the rising popularity of apartment living among wealthy Australians. Developers are increasingly catering to this trend by producing high-quality lifestyle apartments with large floorplans, many luxurious inclusions and access to world-class amenities and services.

Ms Conisbee said prestige home values also had a higher rate of appreciation because Australia’s rich were getting richer.

“A recent report from Oxfam has found that the wealth of Australia’s richest people has increased at a rate of $1.5 million per hour since 2020,” she said. “A lot of this wealth has been invested in luxury homes around Australia.”

The most expensive homes in Australia

CoreLogic data shows the most expensive suburb in Australia for houses is Bellevue Hill in Sydney, with a median value of $9.73 million. Nearby Point Piper is the most expensive suburb for apartments with a median of $3.32 million. In 2023, Australia’s top five sales occurred in Bellevue Hill, nearby Vaucluse and Hawthorn in Melbourne, ranging from $39 million to $76 million.

In regional Australia, the most expensive suburbs are Sunshine Beach in Queensland with a median house price of $2.38 million, Gerroa in NSW ($2.34 million), Surfers Paradise in Queensland ($2.27 million), Burradoo in NSW ($2.25 million) and Noosa Heads in Queensland ($2.24 million).

During the pandemic, the highest capital growth was seen in the most desirable and expensive regional markets, as wealthy city dwellers bought large lifestyle homes and holiday residences in prime seachange and treechange areas. Last year, this trend reversed, with the greatest capital gains seen in more affordable regional coastal towns, according to a new CoreLogic report released today.

The report shows that 35% of Australia’s regional coastal markets had record-high median values at the end of 2023, despite rising interest rates and cost of living pressures. The study analysed 368 coastal markets located at least 50km from the nearest capital city to reveal the top 20 gainers. All of these suburbs had a median value well below $1 million and Western Australia dominated the list.

CoreLogic Research Director Tim Lawless said: “The performance of those with the largest gains and the highest growth rates are not the glamorous hot spots that rose to prominence during COVID. The past 12 months has seen markets that offer a combination of value and lifestyle attributes, such as commuting distance to a major city, great beaches, and quality housing at a more affordable price point, outperform more well-known areas.

“Suburbs in areas such as Western Australia and more northern regions of Queensland where it’s still possible to make a seachange for less than $1 million were the strongest performers last year. Although home values in these regions are mostly at record highs, they remain relatively affordable for seachangers selling out of more expensive metro markets.”

Highest annual capital gains in 2023 – regional coastal towns

1. Bouvard, Mandurah, WA (up 28% to record high of $560,138)
2. Augusta, Bunbury, WA (up 23.2% to record high of $717,573)
3. San Remo, Mandurah, WA (up 22.9% to record high of $678,940)
4. Halls Head, Mandurah, WA (up 22.8% to record high of $694,473)
5. Secret Harbour, South West Perth, WA (up 22.4% to record high of $699,469)
6. Golden Bay, South West Perth, WA (up 22.2% to record high of $613,265)
7. Mulambin, Central QLD, (up 22.1% to record high of $822,553)
8. Usher, Bunbury, WA (up 21.3% to record high of $418,780)
9. Silver Sands, Mandurah, WA (up 21.1% to record high of $592,355)
10. Singleton, South West Perth, WA (up 20.4% to record high of $657,632).

Source: CoreLogic

Gender pay gap greatest among Australian managers

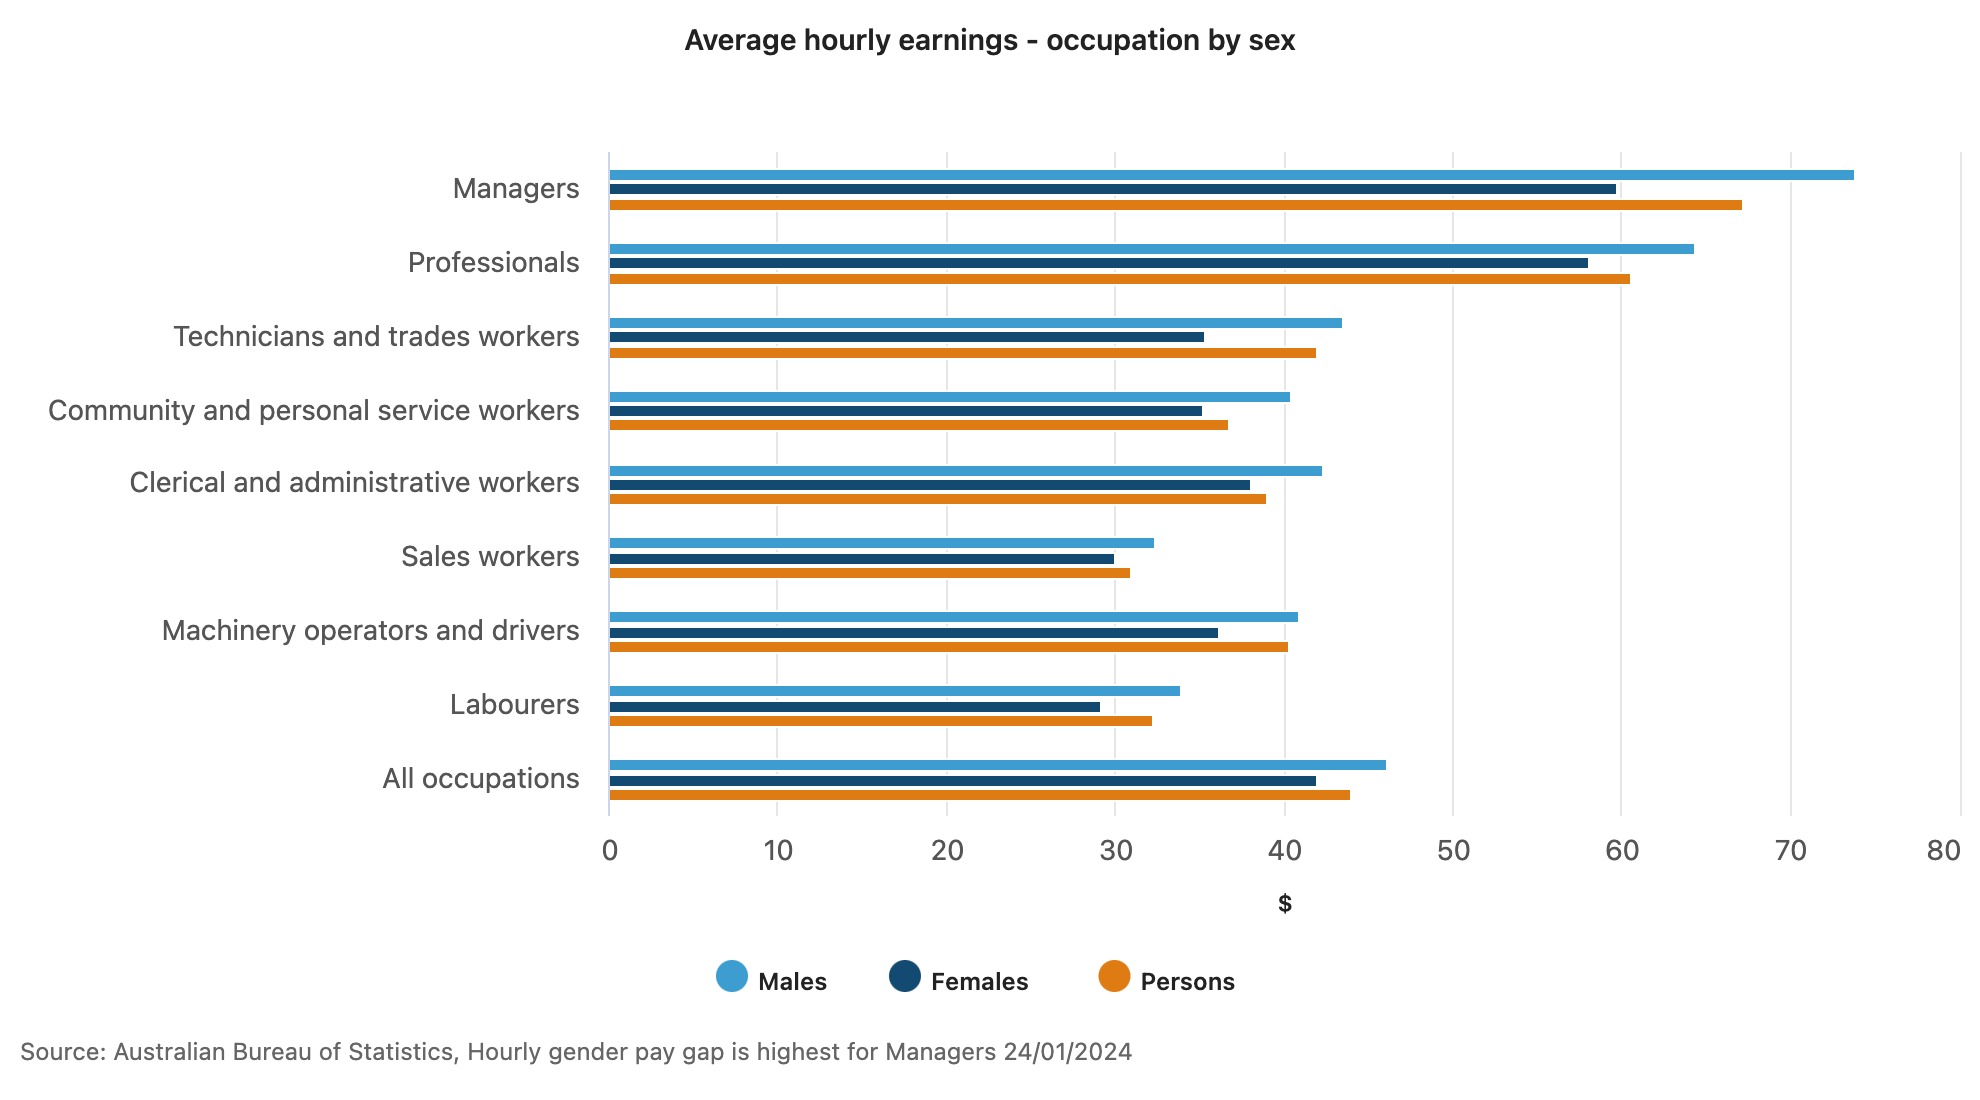
Women in management experience the greatest hourly pay gap, new data from the Australian Bureau of Statistics shows.

The Survey of Employee Earnings and Hours released today showed the difference between average hourly earnings for men and women in management roles in May 2023 was $14.10 per hour, ABS head of labour statistics, Bjorn Jarvis said. In percentage terms, that represents a 19 percent difference.

While the gap was starkest at the top level, men continued to earn more per hour across all eight major occupation groups, the statistics revealed, with the smallest gap among sales workers at 7 percent.

In terms of weekly earnings, men earned an average of $1,731 and women $1,261. The average pay for all employees was $1,490 in May 2023.

“Analysing the difference between male and female earnings is complex and there is no single measure that can provide a complete picture,” Mr Jarvis said. “Hourly earnings comparisons are particularly useful in understanding gender pay differences beyond weekly earnings measures, given women are more likely to work part-time than men.”

For part time workers, where women make up the majority at 69 percent of employees, women earn more on average at $817 compared with $759 for men.

“This reflects the greater use of part-time working arrangements by women in higher paying jobs, compared to men,” Mr Jarvis says.

Across the employment sector, distributional data showed that the top 25 percent of workers earned more than $1,956 per week in May 2023 while the lowest 25 percent earned less than $785. On an hourly basis, managers came out on top at $67.20 per hour, followed by professionals at $60.60, followed by labourers ($32.20) and sales workers ($30.90). 

Woman Arrested for Allegedly Stealing $2,500 of Stanley Drinking Cups

The Stanley cup craze has taken a criminal turn.

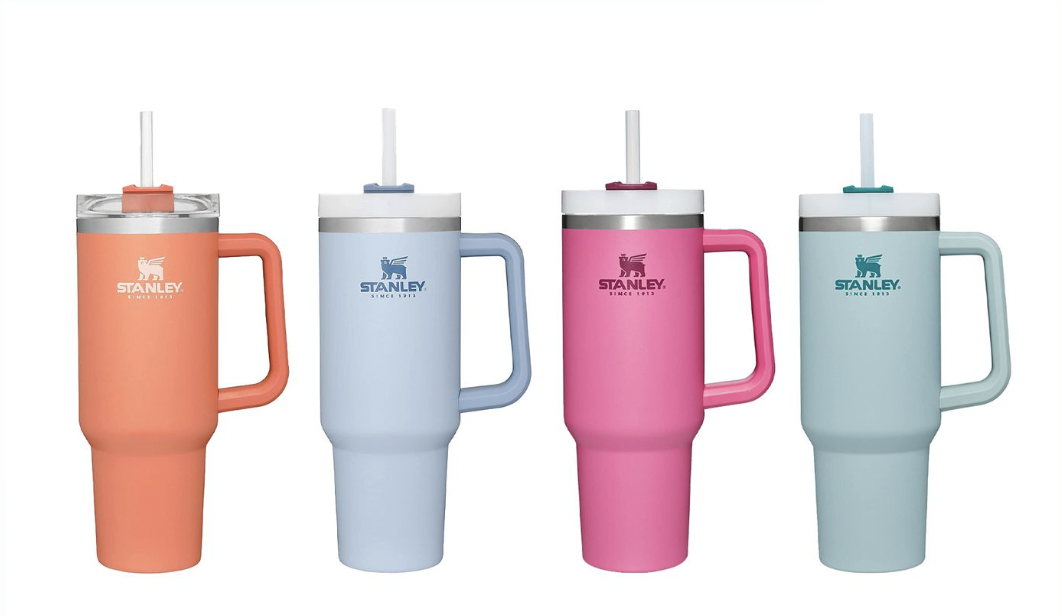
A 23-year-old Sacramento, Calif., woman was arrested after allegedly stealing nearly $2,500 worth of Stanley cups from a retail store, local police said. The woman allegedly filled her shopping cart with Stanley Quenchers—the insulated cups that have thrown social-media into a frenzy in recent months—and left without paying.

When police tracked her down, they found her car filled with 65 of the cups, according to Lt. Chris Ciampa of the Roseville Police Department. She was arrested on charges of grand theft and driving under the influence, Ciampa said.

The arrest was the latest episode in the viral craze over the water bottles. The stainless-steel tumblers—the popular, 40-ounce version of which sells for $45—have become a status symbol for many women and teens, sparking chaos at retailers and launching a resale market where certain colors sell for more than $200 apiece. The hashtag #stanleytumbler has more than a billion views on TikTok and has been used more than 180,000 times on Instagram.

Stanley, which has been in business for more than a century, has long been a popular brand for hikers, teachers and construction workers. But as the Quencher’s popularity skyrocketed in recent years, its maker capitalised on the new demand with collaborations and a wider, pastel-driven colour palette.

“We were a brand that was a $70 million brand that appealed to guys with a green bottle that was 107 years old and is one of the greatest products in history,” Stanley’s president, Terence Reilly, said in an interview earlier this month. He added: “There was a big opportunity to reposition the brand and appeal to new consumers. And that’s just what we set out to do in 2020.”

In 2022, the company said there was a 150,000-person long wait list for the Quencher and sales had more than tripled from the prior year.

The cups have sparked a collectors’ craze, with devotees amassing dozens of colors and fighting over limited-edition releases. Ahead of one such release, for the Starbucks x Stanley pink Quencher, shoppers camped overnight outside Target locations to ensure they got a cup. The products sold out in minutes at some stores, and a viral video of frenzied shoppers rushing a display in one location sparked consternation online.

Those limited-edition pink cups, which are currently not available on Target or Stanley’s website, are now retailing for hundreds of dollars on resale sites like eBay and StockX.

Ciampa, the police lieutenant, said he believes the woman likely intended to resell online the 65 cups that were in her car. The department warned any potential thieves against repeating her behavior.

“While Stanley Quenchers are all the rage, we strongly advise against turning to crime to fulfil your hydration habits,” it said in a statement.

Desperate Chinese Property Developers Resort to Bizarre Marketing Tactics

China’s real-estate crisis has dragged down the economy, caused massive layoffs and pushed multibillion-dollar companies to the point of collapse.

Economists think it is about to get worse.

Sales of newly built homes in China fell 6% last year, returning to a level not seen since 2016, according to China’s statistics bureau. Secondhand home prices in its four wealthiest cities—Beijing, Shanghai, Guangzhou and Shenzhen—declined by between 11% and 14% in December from the year before, according to the broker Centaline Property.

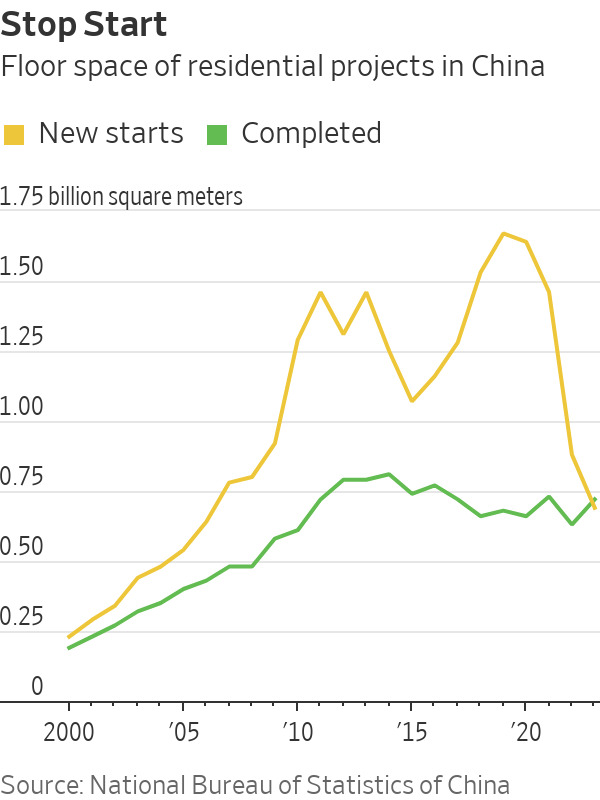
Developers are starting fewer projects. Homeowners are paying back their mortgages early and borrowing less. Once-thriving property companies are stuck in protracted negotiations with foreign investors, following defaults on about $125 billion of overseas bonds between 2020 and late 2023, according to figures from S&P Global Ratings.

Chinese developers and local governments are so desperate to attract home buyers that some have resorted to bizarre marketing strategies.

A property company in Tianjin ran a video advertisement featuring the slogan “buy a house, get a wife for free.” It was a play on words, using the same Chinese characters as the phrase “buy a house, and give it to your wife”—but presented in a sentence structure typically used to offer freebies for home buyers. In September, the company was fined $4,184 for the ad.

A residential compound in eastern China’s Zhejiang province promised last year to give home buyers a 10-gram gold bar.

Earlier this month, Sheng Songcheng, former head of the statistics department at the People’s Bank of China, told a local conference that the housing downturn would last another two years. He thinks new-home sales will fall more than 5% in both 2024 and 2025.

Wall Street economists are also ringing alarm bells about how long the real-estate slump will last.

“Not too many people are buying, can buy or want to buy,” said Raymond Yeung, chief China economist at ANZ. He said there had been a fundamental shift in the way Chinese people view the property sector, with housing no longer seen as a safe investment.

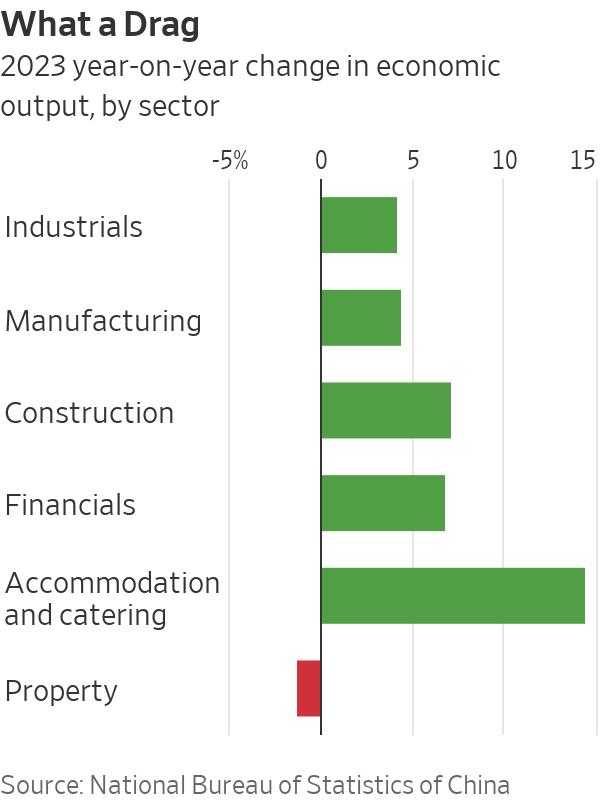
China’s real-estate sector and related industries once accounted for around a quarter of gross domestic product and the sector’s slump has been a significant drag on the world’s second-largest economy. That has increased calls for Beijing to do more to prop up the sector, but so far Chinese officials have stuck to piecemeal policies rather than introducing a landmark stimulus package.

A number of economists are making comparisons to Japan, which spent decades trying to rebound from a crash in real-estate and stock prices. China’s stock market is in a years-long slump.

China’s central bank can help make the situation less painful, but it will need to be aggressive, said Li-gang Liu, head of Asia Pacific economic analysis at Citi Global Wealth Investments. The central bank still has policy room and could take one big step to make a significant impact, he said.

Liu Yuan, head of property research at Centaline, said that without the government’s help, new-home prices will need to drop by another 50% from current levels before they reach a bottom. This is based on the assumption that the tipping point will only come when it is cheaper to buy than to rent houses, Liu said.

China’s real-estate downturn has claimed dozens of victims. More than 50 developers—mostly privately owned—have defaulted on their debt. Developers still have millions of unfinished homes that were sold but not delivered. Chinese authorities have set aside billions of dollars to help builders complete apartments but the logjam is growing.

The crisis has drained the coffers of some Chinese local governments, which previously relied on land sales as a main source of income. Economists estimate they have hidden debt worth anything from $400 billion to more than $800 billion. To quiet talk of potential defaults, the central government has set up debt-swap programs to help some of them refinance.

Some economists are optimistic. In the first half of this year, buyers of secondhand homes will gradually return to the new-home market and prop up the sector, said Helen Qiao, chief China economist at Bank of America. “Things will slowly get better from here,” Qiao said.

But most are still expecting more pain, and investors are bearish. A benchmark of Hong Kong-listed property stocks had fallen for four years in a row before the start of this year. Since Jan. 1, it is down another 15%.